
GM Fintech Futurists,
Today we highlight the following:
AI: Ramp and Stripe Are Giving AI a Wallet
ANALYSIS: Can Zero Human Companies Escape Economic Gravity
CURATED UPDATES: Financial Institutions and Adoption; DeFi and Digital Assets; Blockchain Protocols; NFTs, DAOs and the Metaverse
To support this writing and access our full archive of newsletters, analyses, and guides to building in Fintech & DeFi, subscribe below (if you haven’t yet).
🤖🏦🧭 Our Ecosystem:
Generative Ventures | AI Research | Robot Money | Linkedin & Twitter | Sponsors
AI: Ramp and Stripe Are Giving AI a Wallet
Why do agents need cards?
Both Ramp and Stripe are pushing further into this product line.
Today, an AI agent that needs to buy something has to pause, ask a human for authorisation, wait, then proceed. That interruption is a ceiling on what autonomous workflows can do. Once agents have their own cards with pre-authorised policy budgets, that ceiling lifts. The class of tasks an agent can complete end-to-end, without human intervention, expands significantly:
Book the flight
Buy the domain
Renew the SaaS subscriptions
Replenish the AWS credits
Pay the contractor invoice
Reorder the inventory
Run the ad test
All without a human in the loop.
Right now, the usual approach is to hand an agent an actual card number that can be used anywhere, for any amount, with no oversight. The moment an agent behaves unexpectedly or gets compromised, there’s no circuit breaker. One example of this gone wrong is an OpenClaw agent spending $3,000 on a domain and course without its creator’s permission.
Ramp’s solution is tokenisation per transaction.
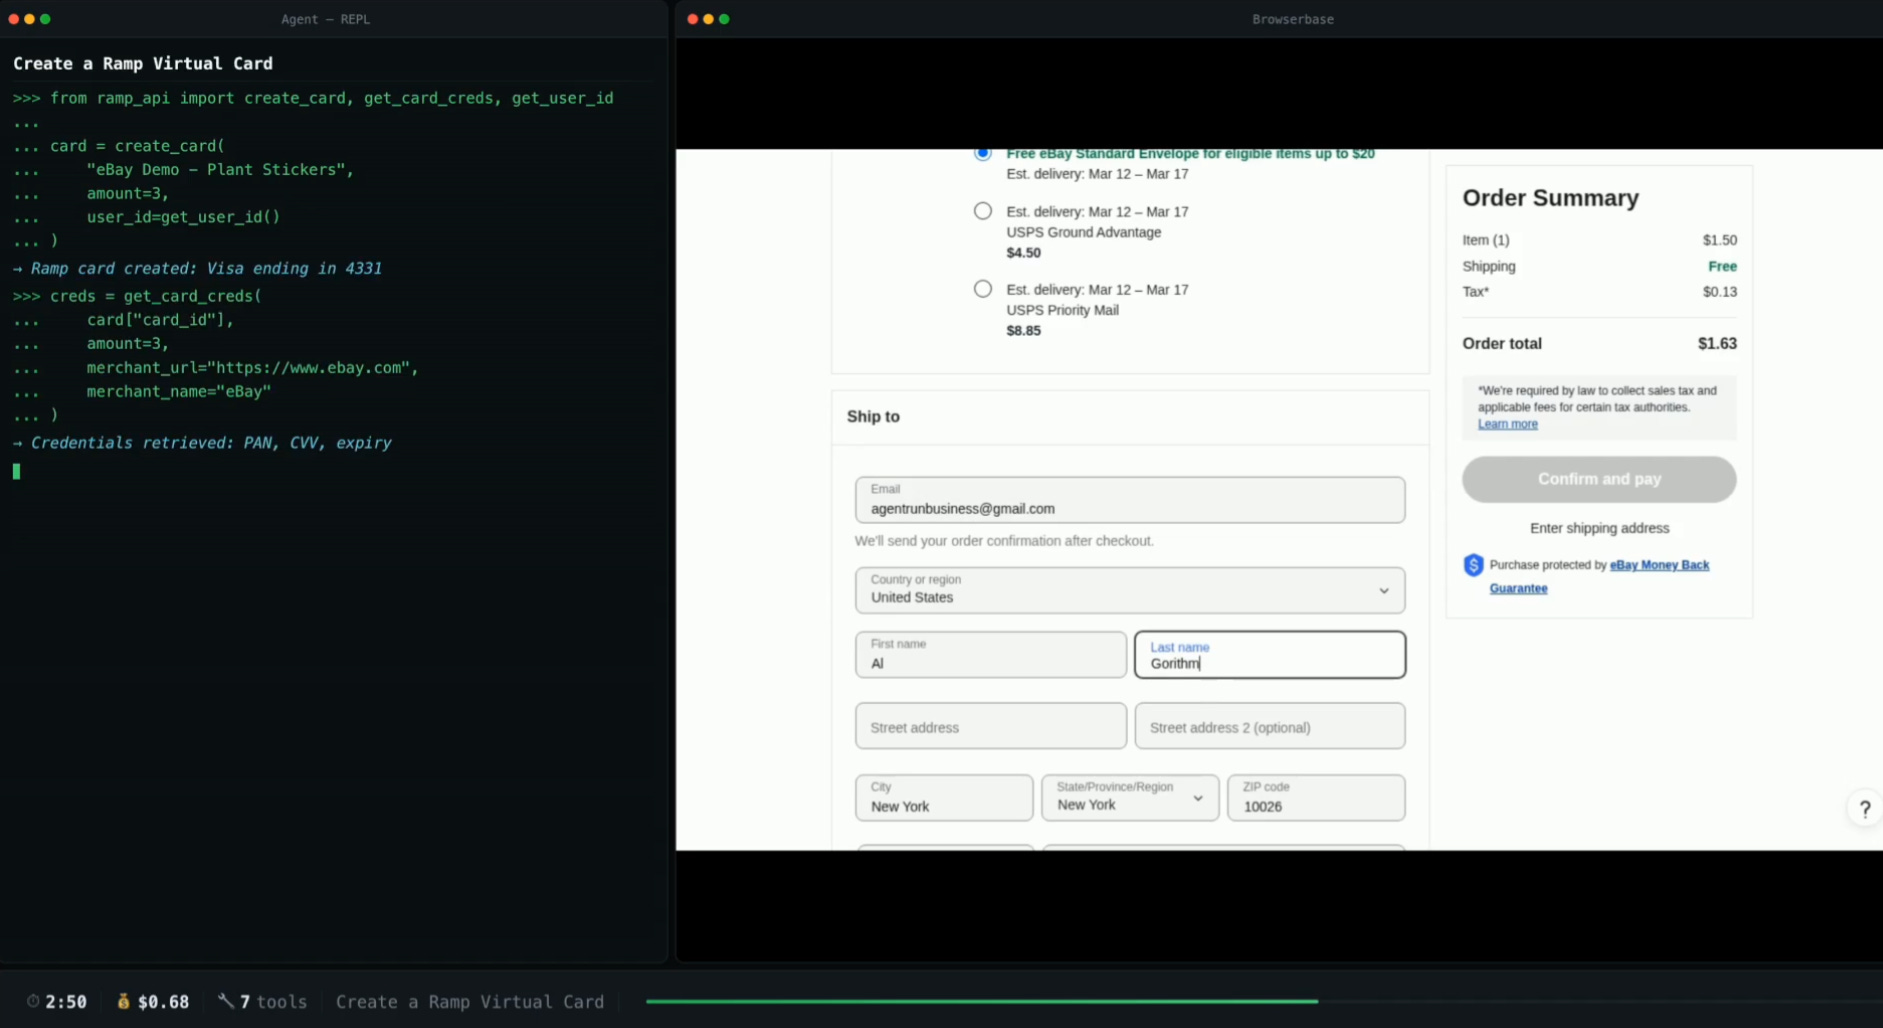
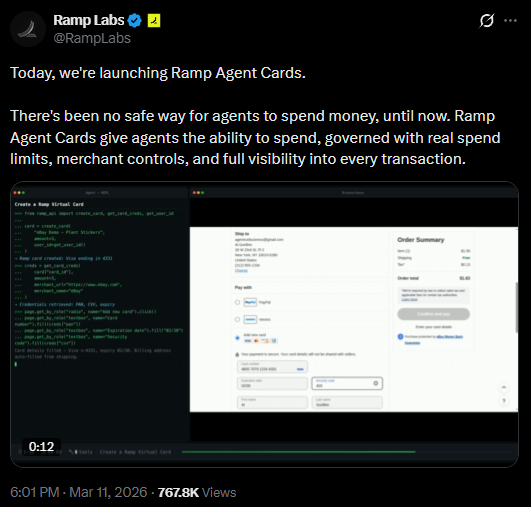
When an agent reaches a point of purchase, it contacts Ramp to generate a single-use tokenised credential. That credential is scoped strictly to the intended transaction, governed by pre-set spend caps, merchant restrictions, and approval chains. Raw card data never touches the agent, and every transaction shows up in the Ramp dashboard.
The infrastructure underneath is Visa’s Trusted Agent Protocol and Intelligent Commerce protocol. This is standard card infrastructure adapted for non-human initiators.
The pitch Ramp is making is essentially that agents are now employees, and they need expense cards with the same controls you’d put on a junior hire.
Stripe is also building this infrastructure.
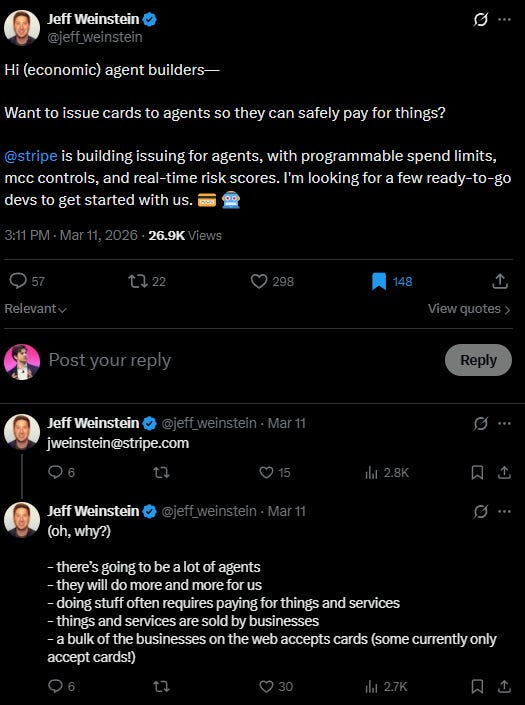
Last year, Stripe launched its Shared Payment Tokens (SPT) product and more recently expanded its capabilities to cater to agentic commerce. SPTs let an AI agent initiate a purchase using a buyer’s saved payment method, without ever seeing the underlying card number. Stripe validates identity on both sides, applies fraud scoring via Radar, and the merchant gets all the data they’d normally get at checkout. Klarna, Affirm, and Mastercard have all plugged into this in the last two weeks.
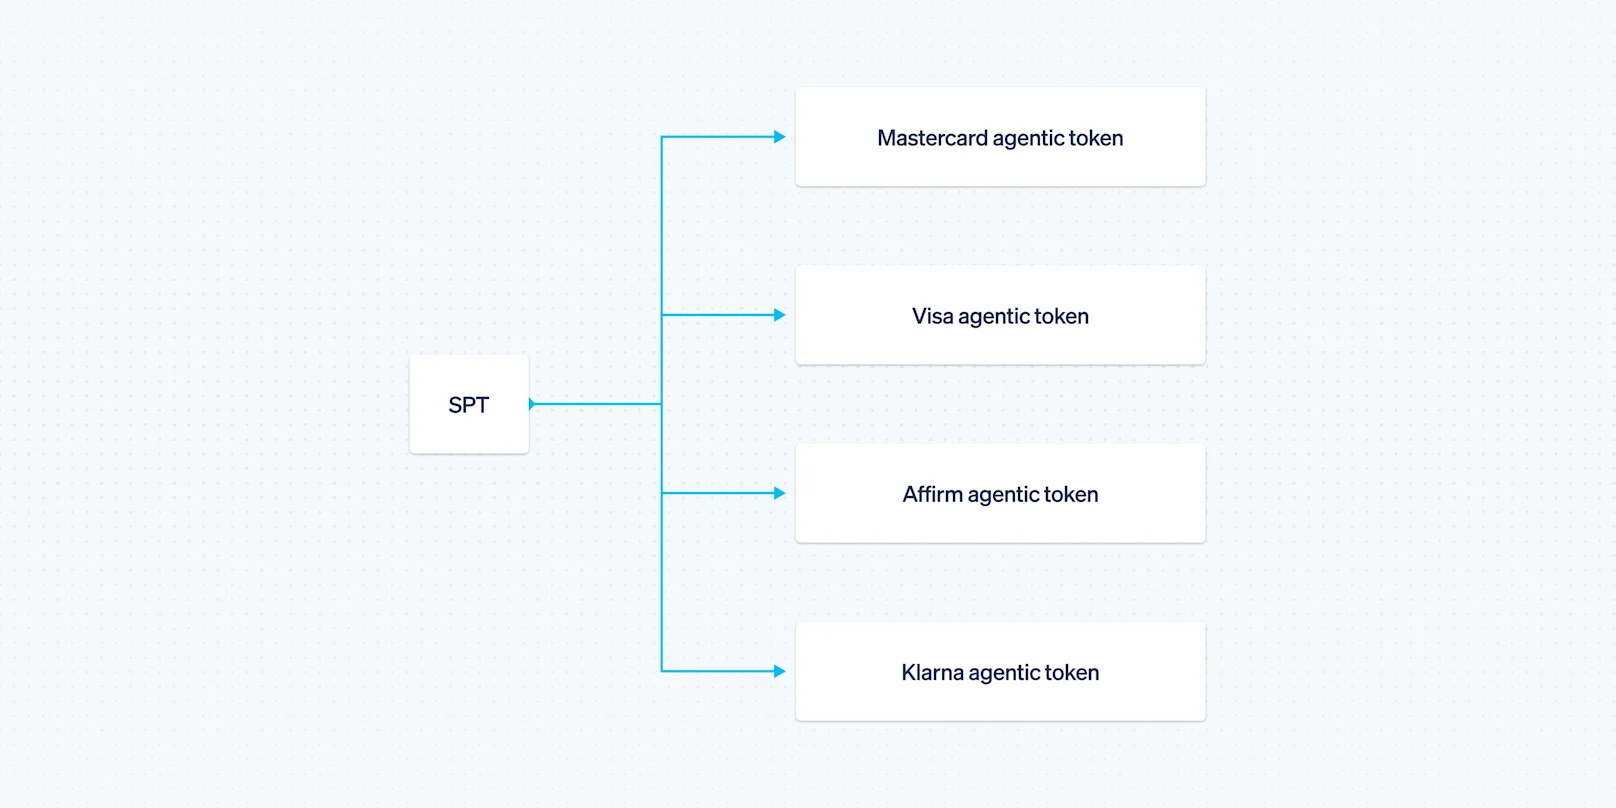
This builds on Stripe’s recently launched AI payment protocol on Base, which leverages x402. This is a developer tool that lets AI agents make automated USDC payments on base. When an agent hits a paid endpoint, the server returns an HTTP 402 status code with payment details. Then the agent sends USDC, attaches confirmation to a repeat request, and gets access. This second product is blockchain-native and targets the microeconomics of agent-to-agent and agent-to-API transactions.
The Opportunity
Is this market here yet? Is it real?
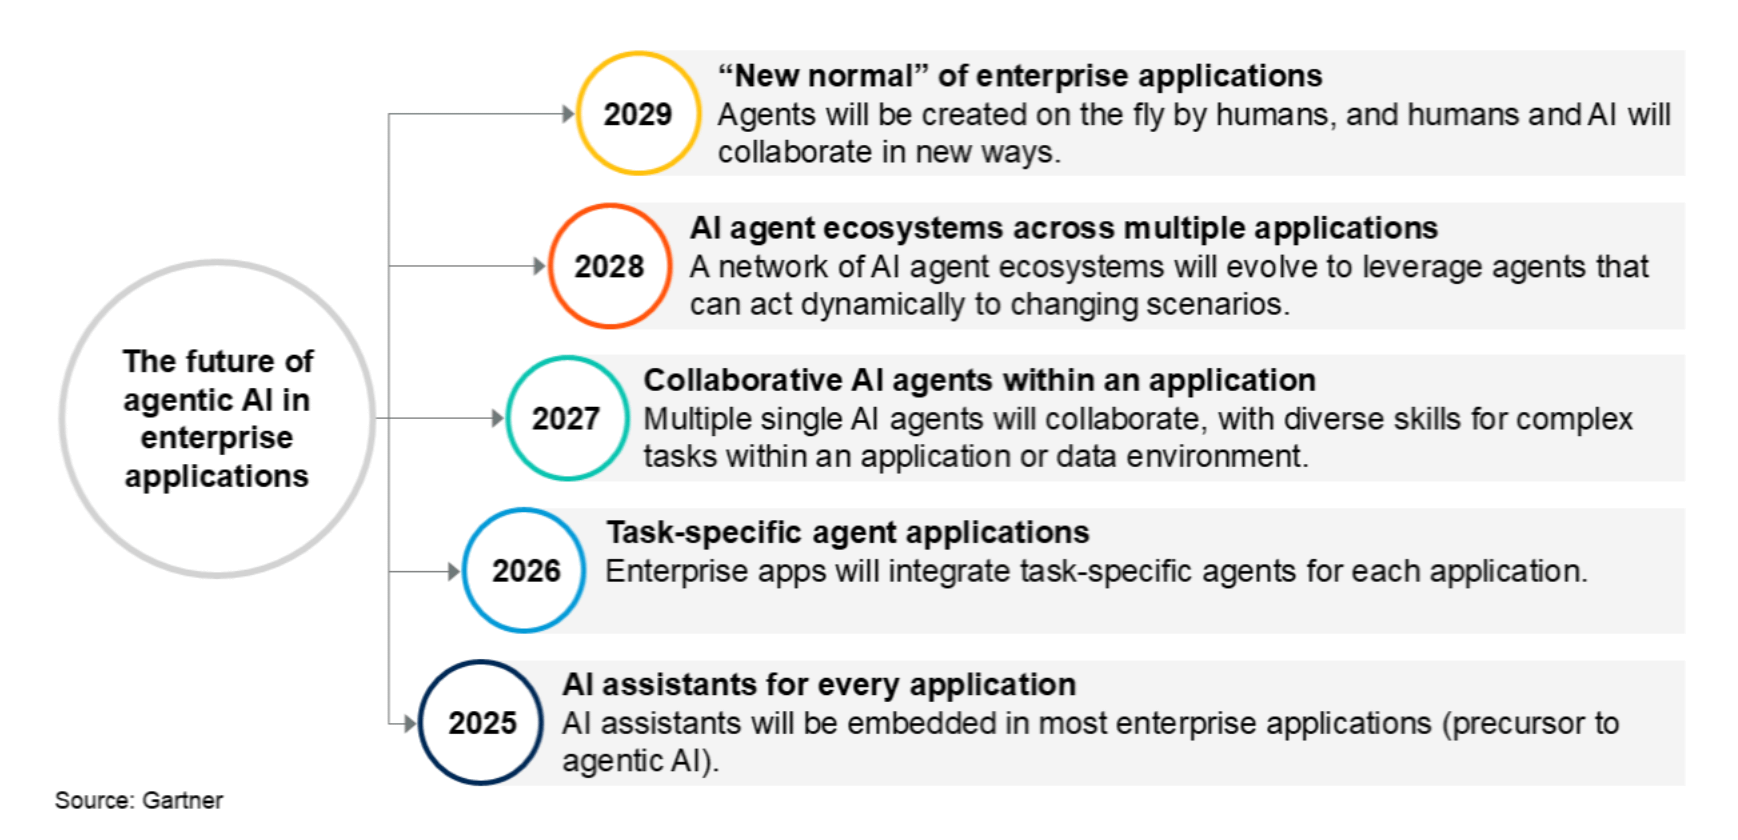
Barclays estimates global AI compute capacity could support between 1.5 billion and 22 billion AI agents. Gartner projects agentic AI could generate nearly 30% of enterprise application software revenue by 2035, surpassing $450 billion. McKinsey estimates that B2C retail spending alone could represent $900B–$1T in agentic commerce by 2030, but this does not include B2B spending.
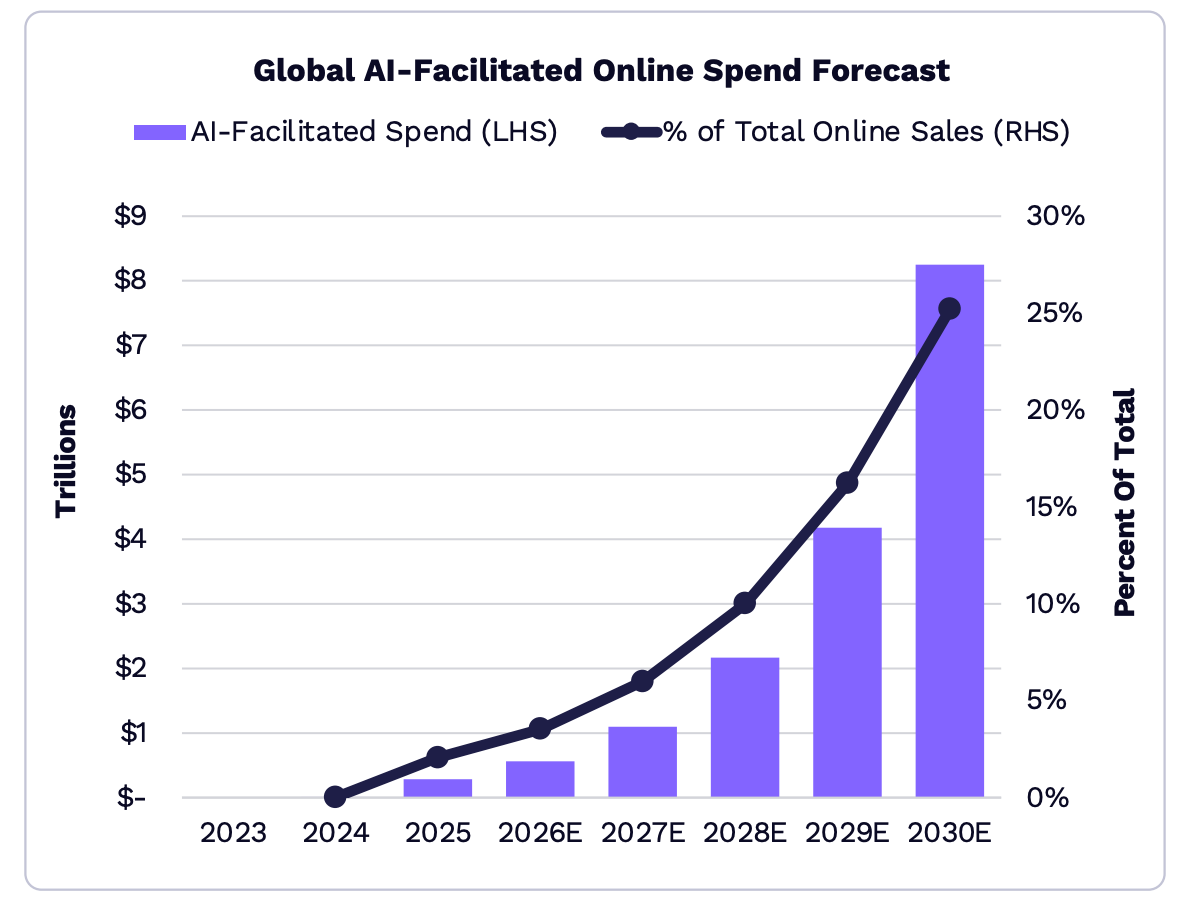
A company running 50 AI agents, each making hundreds of automated purchases a week could generate more card volume per month than their entire human workforce. Unlike human employees, agents don’t forget to submit receipts, don’t book out-of-policy travel, and don’t need reimbursement workflows. The per-agent spend potential is high and the overhead is near zero.
For Ramp, Agent Cards is a strategic land grab on the customers it already has. The company serves 50,000+ businesses. If it becomes the default issuer for agent spending within those same finance teams, using the same policy and controls infrastructure already in place, the volume math changes substantially without needing a single new enterprise customer.
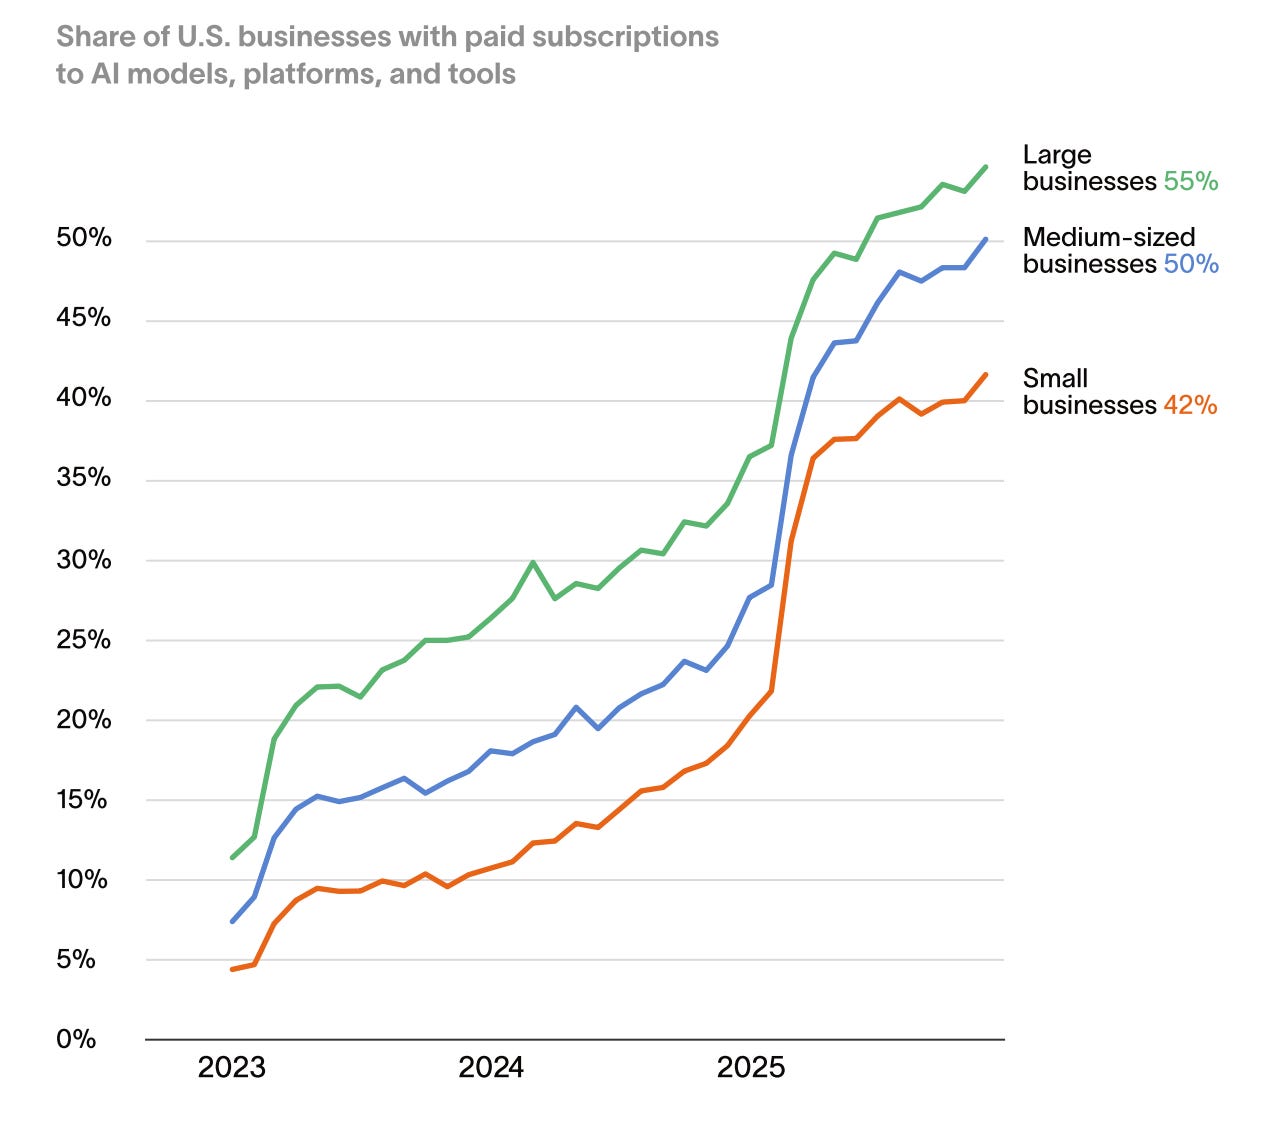
Ramp already processes more than $100B in annual volume at roughly a 0.3–0.5% blended take rate. If agent spend at existing customers adds 20–30% to that base over the next few years, the revenue implications are meaningful at scale.
For Stripe, the opportunity is potentially larger.
Stripe processed $1.9T in total payment volume in 2025, up 34% year-over-year. At a $159B valuation, Stripe is already priced as the infrastructure layer for internet commerce. Agents will likely soon be responsible for most internet transactions. If Stripe maintains anything close to its current share of internet payment volume, the incremental TPV flowing through agent-initiated commerce over the next decade is very large. And let’s not forget Stripe recently acquired stablecoin platform Bridge for $1.1B, wallet infrastructure provider Privy, and is building Tempo, an L1 blockchain specifically for payments.
Despite all of the work going on, there is still a long way to go.
Stripe’s own annual letter acknowledged that today’s blockchains weren’t designed for payments at the volume agentic commerce might require, noting that settling millions of simultaneous agent transactions will stress the infrastructure. They might also be conflicted in telling this story.
Then there’s also the more philosophical lines of liability. When a human employee makes an unauthorised purchase, there’s a clear chain of responsibility. When an agent does, it’s murkier. Who’s liable? The developer who deployed it, the business that authorised the card, the card issuer? The legal frameworks don’t exist yet.
Card fraud detection models will also need to be catered to agents. Currently, they are trained on human behaviour patterns, but agents buy things at 3am, make hundreds of small transactions without geographic logic, and don’t show the normal behavioural signals that fraud systems use. Visa and Mastercard are building “agentic network tokens” specifically to add additional authorisation fields for agent-initiated transactions. That work is ongoing.
And then, of course, is the creation of the agents that use this infrastructure. The building blocks are there and we will experience a Cambrian explosion of agents in the coming years. For Ramp and Stripe – as they say, if you build it, they will come.
👑Related Coverage👑


Analysis: Robot Money and the Financial System for AI
We discuss how the machine economy has already surpassed humanity in scale, with connected devices, AI agents, and automated systems outnumbering and outperforming human labor.

We explain that economic value is increasingly accruing to owners of machines and digital capital rather than to human workers, consistent with decades of research on capital–labor dynamics and the observed stagnation in human-driven GDP. We show that nearly all incremental global enterprise value since 2015 has come from the machine economy: AI mega-caps adding $17T at 20% CAGR, crypto assets adding $3T at 70% CAGR, while major national markets like Germany, France, and the UK produced little new net value. We outline how AI systems are rapidly absorbing commercial tasks in coding, design, writing, and information processing, while new onchain financial rails and agentic payment protocols reshape how machine-to-machine value flows. Ultimately, we argue that robot money, AI agents, and emerging ownership structures for autonomous systems define the frontier — and that whoever owns the robots will rule the world.
Curated Updates
Here are the rest of the updates hitting our radar.
Machine Models
Improving AI models’ ability to explain their predictions - MIT News
Measuring Perceptions of Fairness in AI Systems: The Effects of Infra-marginality - Arxiv
AI Applications in Finance
⭐ Gumloop lands $50M from Benchmark to turn every employee into an AI agent builder - TechCrunch
AI in financial services: The rise of intelligent finance - Plaid
Investment Outlook
⭐ Finance 2026: A preview of the year AI transformation gets real - CIO
AI in banking and financial services: Trends for 2026 - Finastra
🚀 Level Up
Join our Premium community and receive all the Fintech and Web3 intelligence you need to level up your career. Get access to Long Takes, archives, and special reports.
Sponsor the Fintech Blueprint and reach over 200,000 professionals.
👉 Reach out here.Check out our AI newsletter, the Future Blueprint, 👉 here.
Read our Disclaimer here — this newsletter does not provide investment advice
The human-in-the-loop authorisation bottleneck is exactly what makes most 'autonomous' agent workflows not actually autonomous. I've been running agents that handle purchasing tasks and the moment you hit a payment gate, you're back to babysitting. Ramp's policy-based pre-authorisation approach is more interesting to me than Stripe's MPP in the short term - it works within existing card rails instead of requiring merchant-side protocol adoption.
Do you see these as complementary infrastructure or competing approaches? The zero-human-company thought experiment in your analysis section is the right framing.