
Hi Fintech Futurists —
Today’s agenda is below.
AI in FINANCE: Anthropic’s $10B pre-IPO credit facility reveals how Wall Street uses lending relationships to compete for lucrative investment-banking mandates.
ANALYSIS: The Money Robot Eating the GDP of the Internet
PODCAST: AI Distribution for 5000+ Banks, with Fiserv Co-Head of Financial Solutions Srini Krish
CURATED UPDATES: Machine Models, AI Applications in Finance & Investment Outlook
To support this writing and access our full archive of newsletters, analyses, and guides to building in Fintech & DeFi, subscribe below (if you haven’t yet).
🤖🏦🧭 Our Ecosystem:
Sponsor FB | Generative Ventures | SPAC | AI Research | Robot DeFi | Linkedin & X
🚀 Lex is actively meeting teams building machine-native financial companies. If that’s you, reach out here.
🤖 AI & Robotics Industry Encyclopedia: In this 100+ page report, we collate all the meaningful companies across public quities, private equity, and digital assets related to the machine economy. 👉Learn more here
🦄 In partnership with InterPrivate, we just launched a $200MM SPAC looking for targets in fintech, digital assets, and AI infrastructure. If you are a late-stage founder or have an idea to discuss, reply directly to this email.
Anthropic seeking $10B ahead of $75B from the public
Anthropic is asking Wall Street for more than $10B of credit.
Reuters reported that Anthropic is arranging a revolving credit facility expected to exceed $10B ahead of its IPO. The largest banks have reportedly been asked to commit around $1.25B each, second-tier banks around $1B, and others $750MM or less.
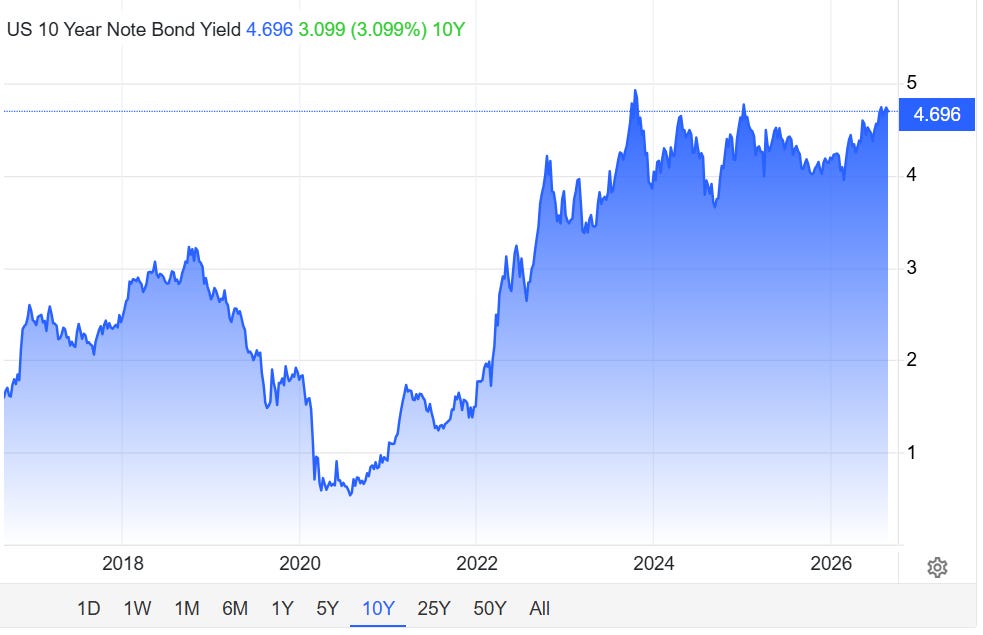
It’s a good time to be a lender — in both nominal and real terms, long-dated rates are getting pushed up, which means profitability from the lending business should remain high, and the key is finding good credit risks. The mega tech firms are one such target.
The banks are not only competing on lending to Anthropic, they are also competing to land a role in Anthropic’s IPO. Joining the facility could improve their chances of this. Anthropic has already confidentially submitted a draft S-1 to the SEC. Bloomberg has since reported that the company expects its offering to match or exceed the $75B raised by SpaceX.
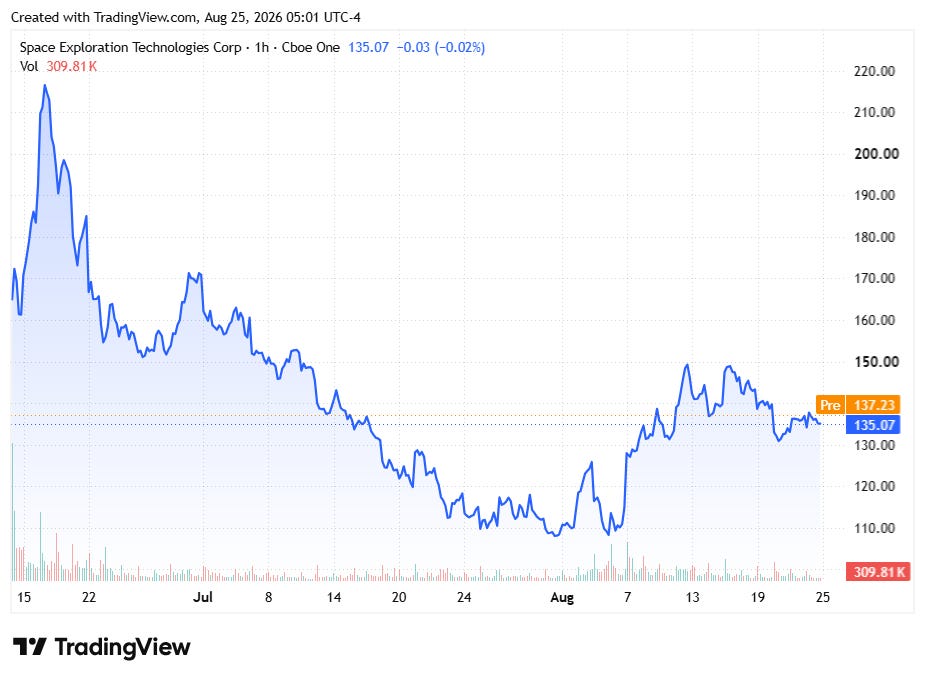
SpaceX has been a fantastic capital markets story, including the pleasures of its volatility. Wall Street finds itself once again preparing for the money party. Banks are putting billions of dollars on the table to lend to a company preparing to receive tens of billions more from public investors.
Anthropic’s banking auction
A revolving credit facility is not the same as Anthropic borrowing $10B tomorrow. It acts as an extraordinarily large corporate credit card. Banks commit capital that Anthropic can draw when needed. Anthropic pays for having that liquidity available, and pays additional interest if it actually borrows the money.
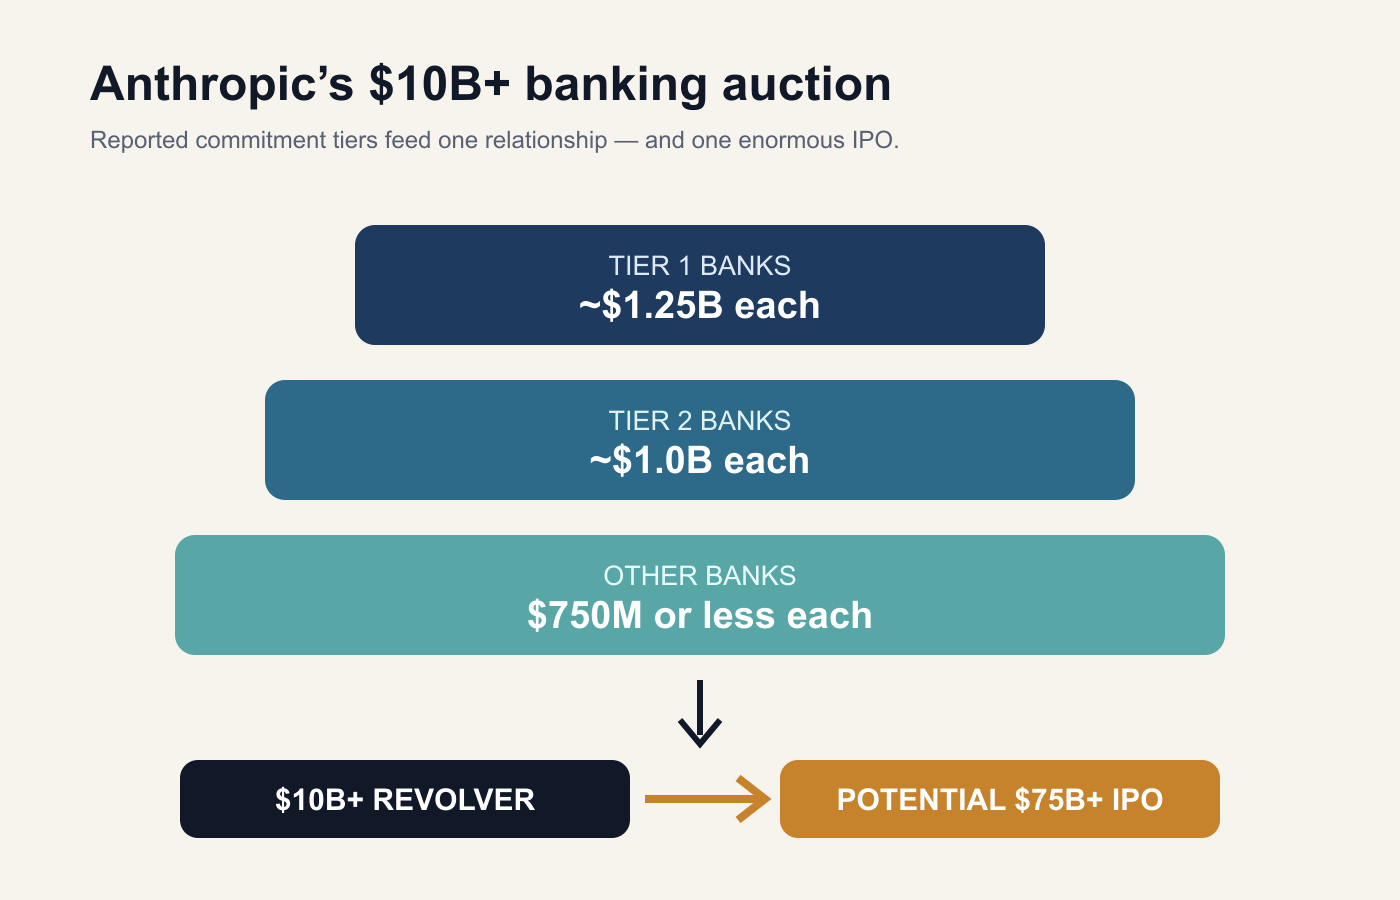
The direct economics of this facility can be attractive. But a $1.25B revolver commitment also consumes balance sheet, requires regulatory capital, creates credit exposure and occupies a lot of senior banking time.
The larger prize sits downstream with the IPO.
If Anthropic completes a $75B-plus IPO, it would create one of the largest underwriting mandates ever awarded. The winning banks could then be positioned for follow-on equity offerings, bond issuance, acquisitions, derivatives, treasury management and future lending.
SpaceX raised roughly $75B in the largest IPO ever.
For middle-market US IPOs, underwriting spreads historically clustered at exactly 7%.
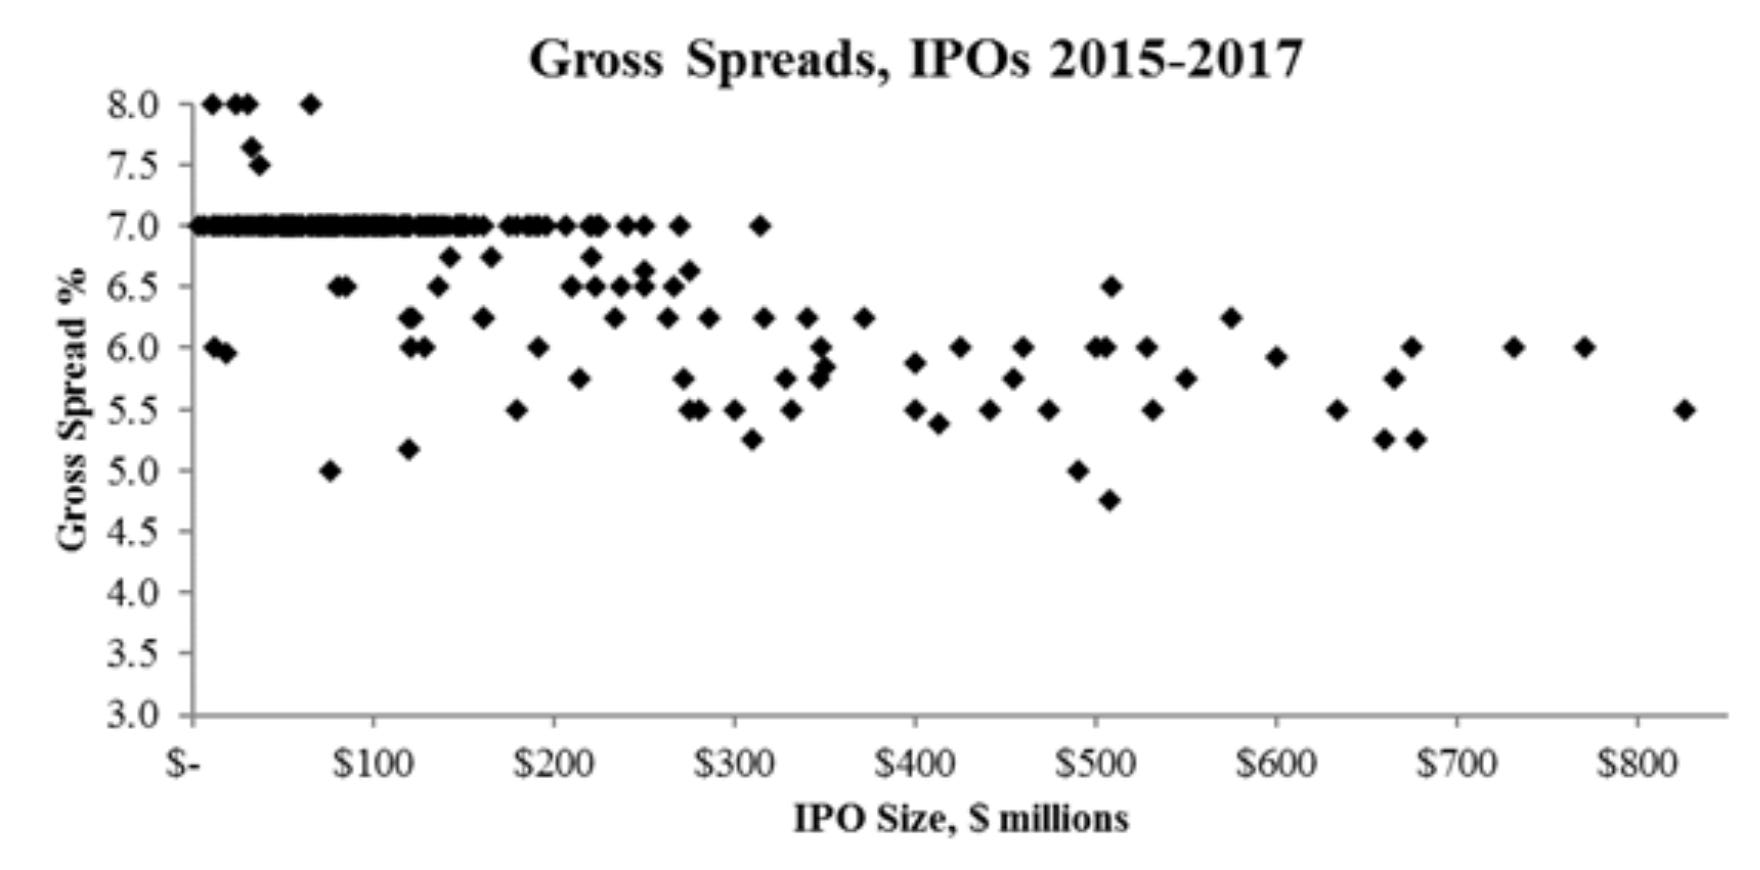
SEC research found that more than 96% of midsized IPOs between 2001 and 2016 paid that rate. SpaceX had a lot more bargaining power.
Its underwriting fee was reportedly negotiated below 0.75%. Yet because the deal was so enormous, banks still stood to share around $500M of fees. That is some pretty magnificent operating leverage.
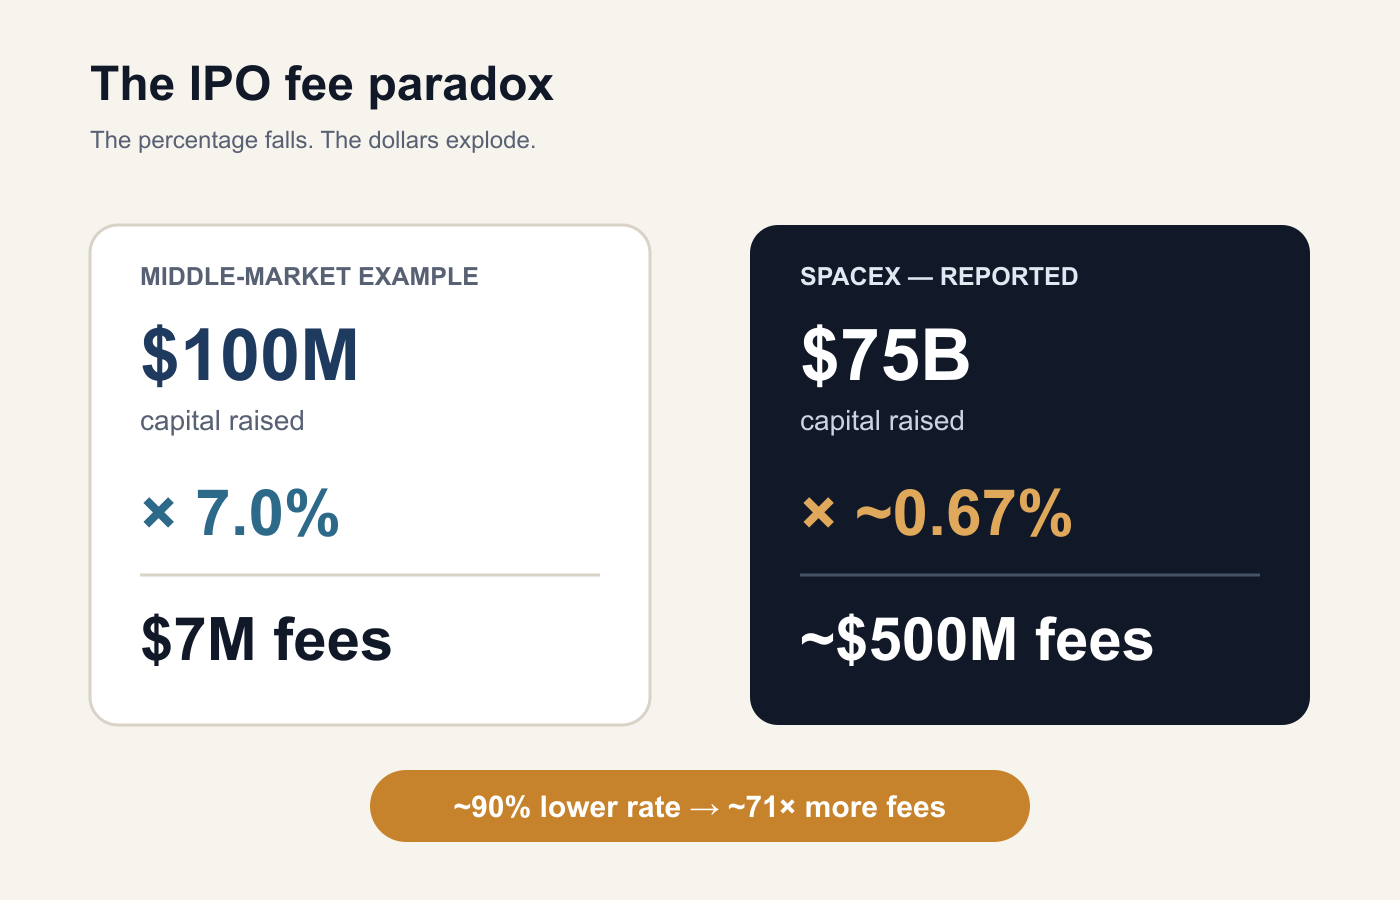
If Anthropic matches SpaceX with another $75B raise and pays anything close to the same economics, another $500MM-$2B fee pool could be sitting in front of Wall Street.
And the IPO is only day one.
Lending has always been a route into investment banking
Economists have studied the interaction between lending and underwriting for decades.
Steven Drucker and Manju Puri found evidence that combining the two can create genuine information efficiencies for issuers. They also found that lending helps an underwriter build relationships which increase its probability of receiving both current and future business.
There are two ways to interpret that:
The cynical version is that banks use their balance sheets to buy investment-banking mandates.
The sunnier version is that lending creates information.
A bank committing $1.25B to Anthropic has to understand its cash flows, cost base, liquidity requirements, downside scenarios and future financing needs. That knowledge is also helpful if you are trying to price and distribute $75B of Anthropic equity.
A separate Journal of Finance study found that companies with pre-IPO banking relationships experienced approximately 17% less IPO underpricing than those without them.
So the relationship can create value for both sides — the bank may become more likely to win the mandate, and Anthropic may get a better-informed underwriter.
Putting a price on the relationship
Imagine a top-tier bank agrees to Anthropic’s reported $1.25B commitment.
We do not know Anthropic’s actual lending spread, commitment fee or utilisation, so the following numbers are deliberately illustrative. Assume the facility is 25% drawn, with a 1.5% spread on borrowed funds and a 0.25% fee on the undrawn amount.
The bank would earn approximately (1) $5MM on the $310MM drawn, and (2) $2.3MM on the $940MM undrawn. Gross annual facility revenue would therefore equal roughly $7MM before funding costs, credit losses, operating costs and the cost of capital.
Now imagine being on the revolver increases the bank’s probability of winning a $5M0M IPO fee allocation from 20% to 60%.
The incremental expected value is 40% × $50MM = $20MM. This is already almost three times the illustrative annual gross lending revenue.
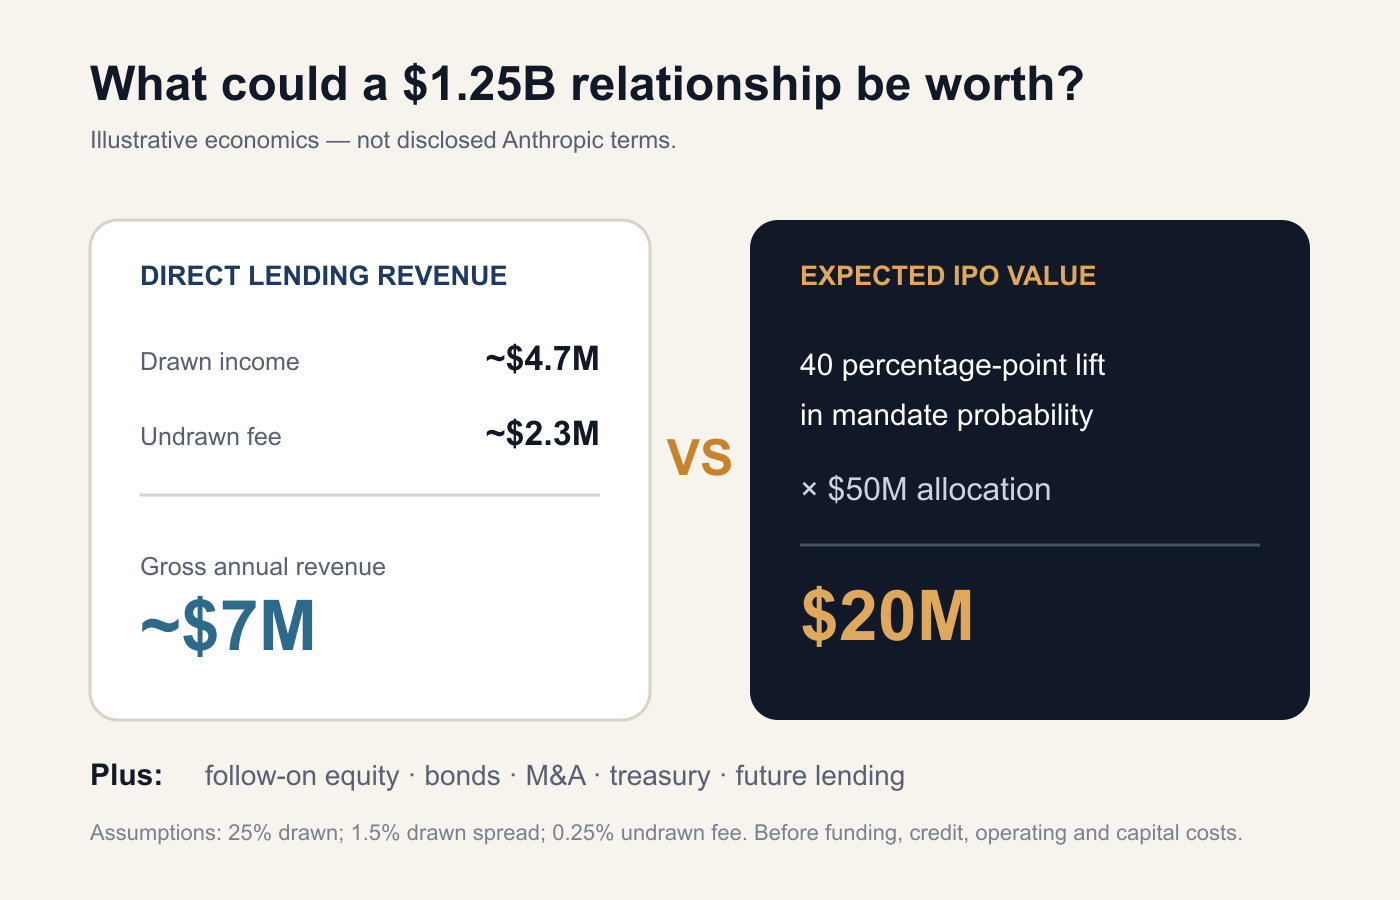
This is a simplified model, not an estimate of Anthropic’s actual facility economics.
But it demonstrates why measuring the transaction purely by the interest earned on the loan misses most of the value. The bank is underwriting a customer-lifetime-value calculation.
Also, as a reference for scale, $1.25B is what Anthropic agreed to spend on compute from SpaceX every month through May 2029. Only one of their compute partners.
There is a legal line Wall Street cannot cross
A bank cannot simply tell Anthropic “Give us the IPO, and we will give you $1.25B”.
US banking law generally prevents banks from conditioning credit on customers purchasing certain other services from the bank or its affiliates. But a bank can still build a relationship with the hope of more work in the future — a necessary part of financial institutions’ mandates internally.
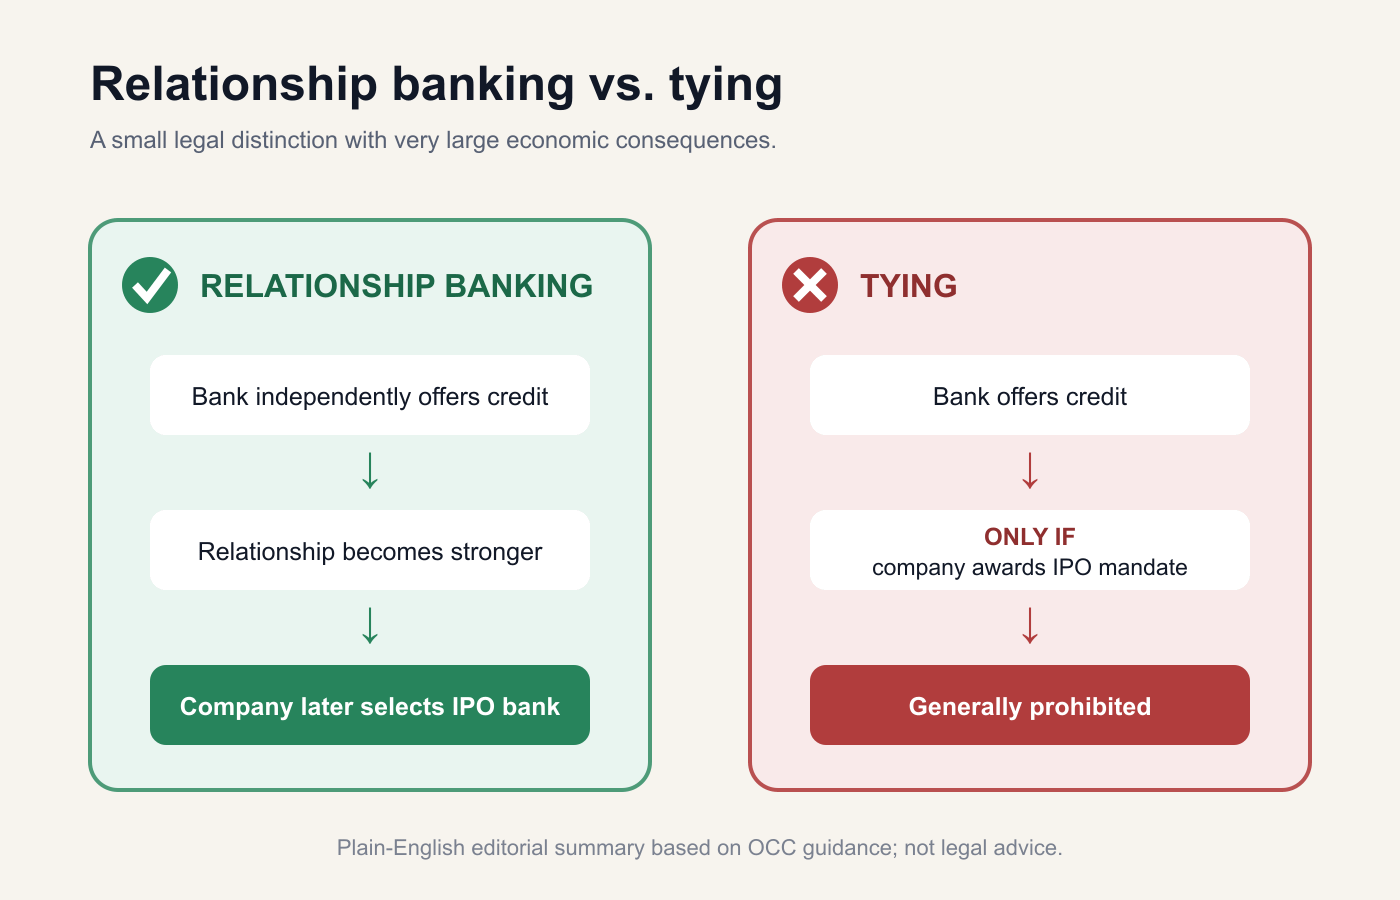
The difference is only a few arrows on a diagram, but economically, they can look remarkably similar.
AI is creating a mega-IPO economy
Anthropic also arrives at a particularly convenient moment for investment banks.
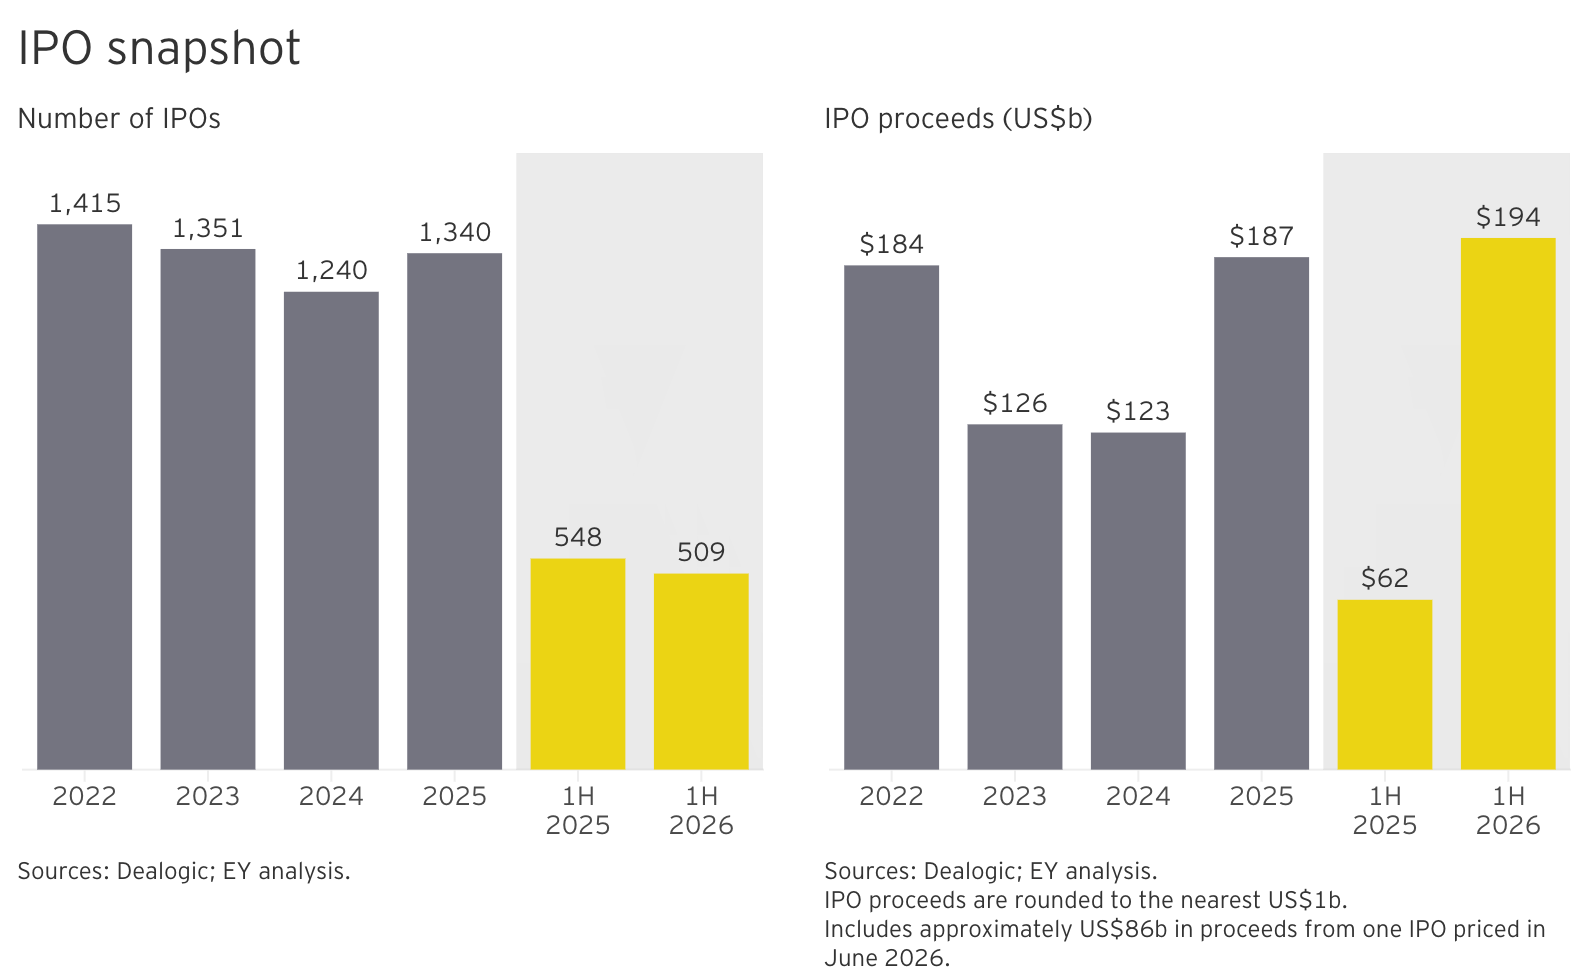
EY’s Global IPO Trends report says the first half of 2026 was shaped by mega-IPOs and AI-related issuance. Its US analysis notes that 12 companies raised more than $1B in the first half, up from only four in the same period of 2025.
If capital formation concentrates into a handful of enormous transactions, league-table position becomes increasingly dependent on winning those few mandates.
Missing Anthropic is not the same as missing a $300MM software IPO.
Balance sheet allocation is part of the investment bank’s customer-acquisition budget.
There is a temptation to conclude that banks are giving away cheap capital to buy Anthropic’s IPO, but this may not be the full picture. Research on relationship banking and pricing found no evidence that universal banks systematically underpriced loans merely to win underwriting work. Banks can also extract value from a combined relationship.
Anthropic in this case, though, has extraordinary negotiating power.
It can make Goldman Sachs, JPMorgan, Morgan Stanley, Citi and every other large bank compete not only on the price of underwriting but on how much balance sheet they are prepared to put behind the relationship before the IPO even begins.
Most discussion around Anthropic’s IPO will focus on its valuation, whether revenue can continue growing, and if Claude can maintain its enterprise position.
But the more profound story is about the speed of innovation and pace of change. A company founded in 2021 has become valuable enough that the world’s largest banks are competing to commit more than $10B of their own balance sheets to deepen their relationship with it.
We are seeing trillion-dollar corporations rising from data center to the cosmos, bringing forth machine intelligence and human transformation. It is a cliché, and it is true.
👑Related Coverage👑


Analysis: The Annotated Stripe Letter (link here)
We examine Stripe’s $7B OpenRouter acquisition as the centerpiece of a roughly $10B push to vertically integrate the infrastructure of the machine economy. We argue that Stripe is using its enormous Web2 distribution to commercialize technologies pioneered across crypto and AI, assembling stablecoins, wallets, usage billing, payments, blockchain settlement, and now inference routing into one stack.
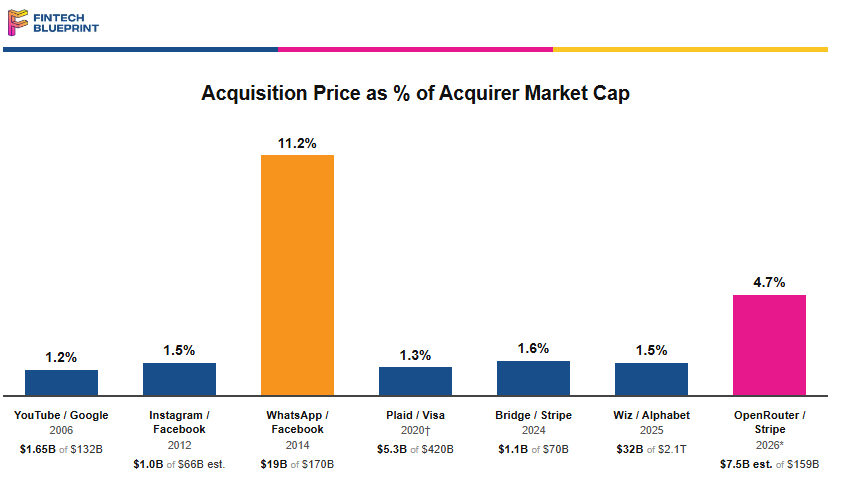
OpenRouter gives Stripe control over a critical commodity layer—AI inference—whose economics increasingly depend on routing workloads across models based on price, performance, compute, and availability. We conclude that Stripe is positioning itself as the economic operating system for AI companies and agents, but its expanding footprint also creates concentration risk and increasingly puts it in direct competition with Ramp.
🎙️ Podcast: AI Distribution for 5000+ Banks, with Fiserv Co-Head of Financial Solutions Srini Krish (link here)
In this episode, Lex chats with Srini Krish — Co-Head of Financial Solutions at Fiserv, one of the original fintechs, in business for nearly five decades and sitting at the intersection of commerce and banking.
Lex and Srini discuss how Fiserv acts as the technology backbone for 5,000+ US banks and credit unions that lack the wherewithal to match JPMorgan or Wells Fargo on their own, and how the firm is packaging AI into that distribution layer through Agent OS and partnerships with OpenAI and Anthropic. Srini lays out his four-bucket framework for enterprise AI - better client service, internal productivity, AI embedded in products, and a platform banks can use to build their own agents - and explains why money demands deterministic outcomes rather than probabilistic guesses, keeping a human in the middle as commercial loan underwriting compresses from weeks to hours.
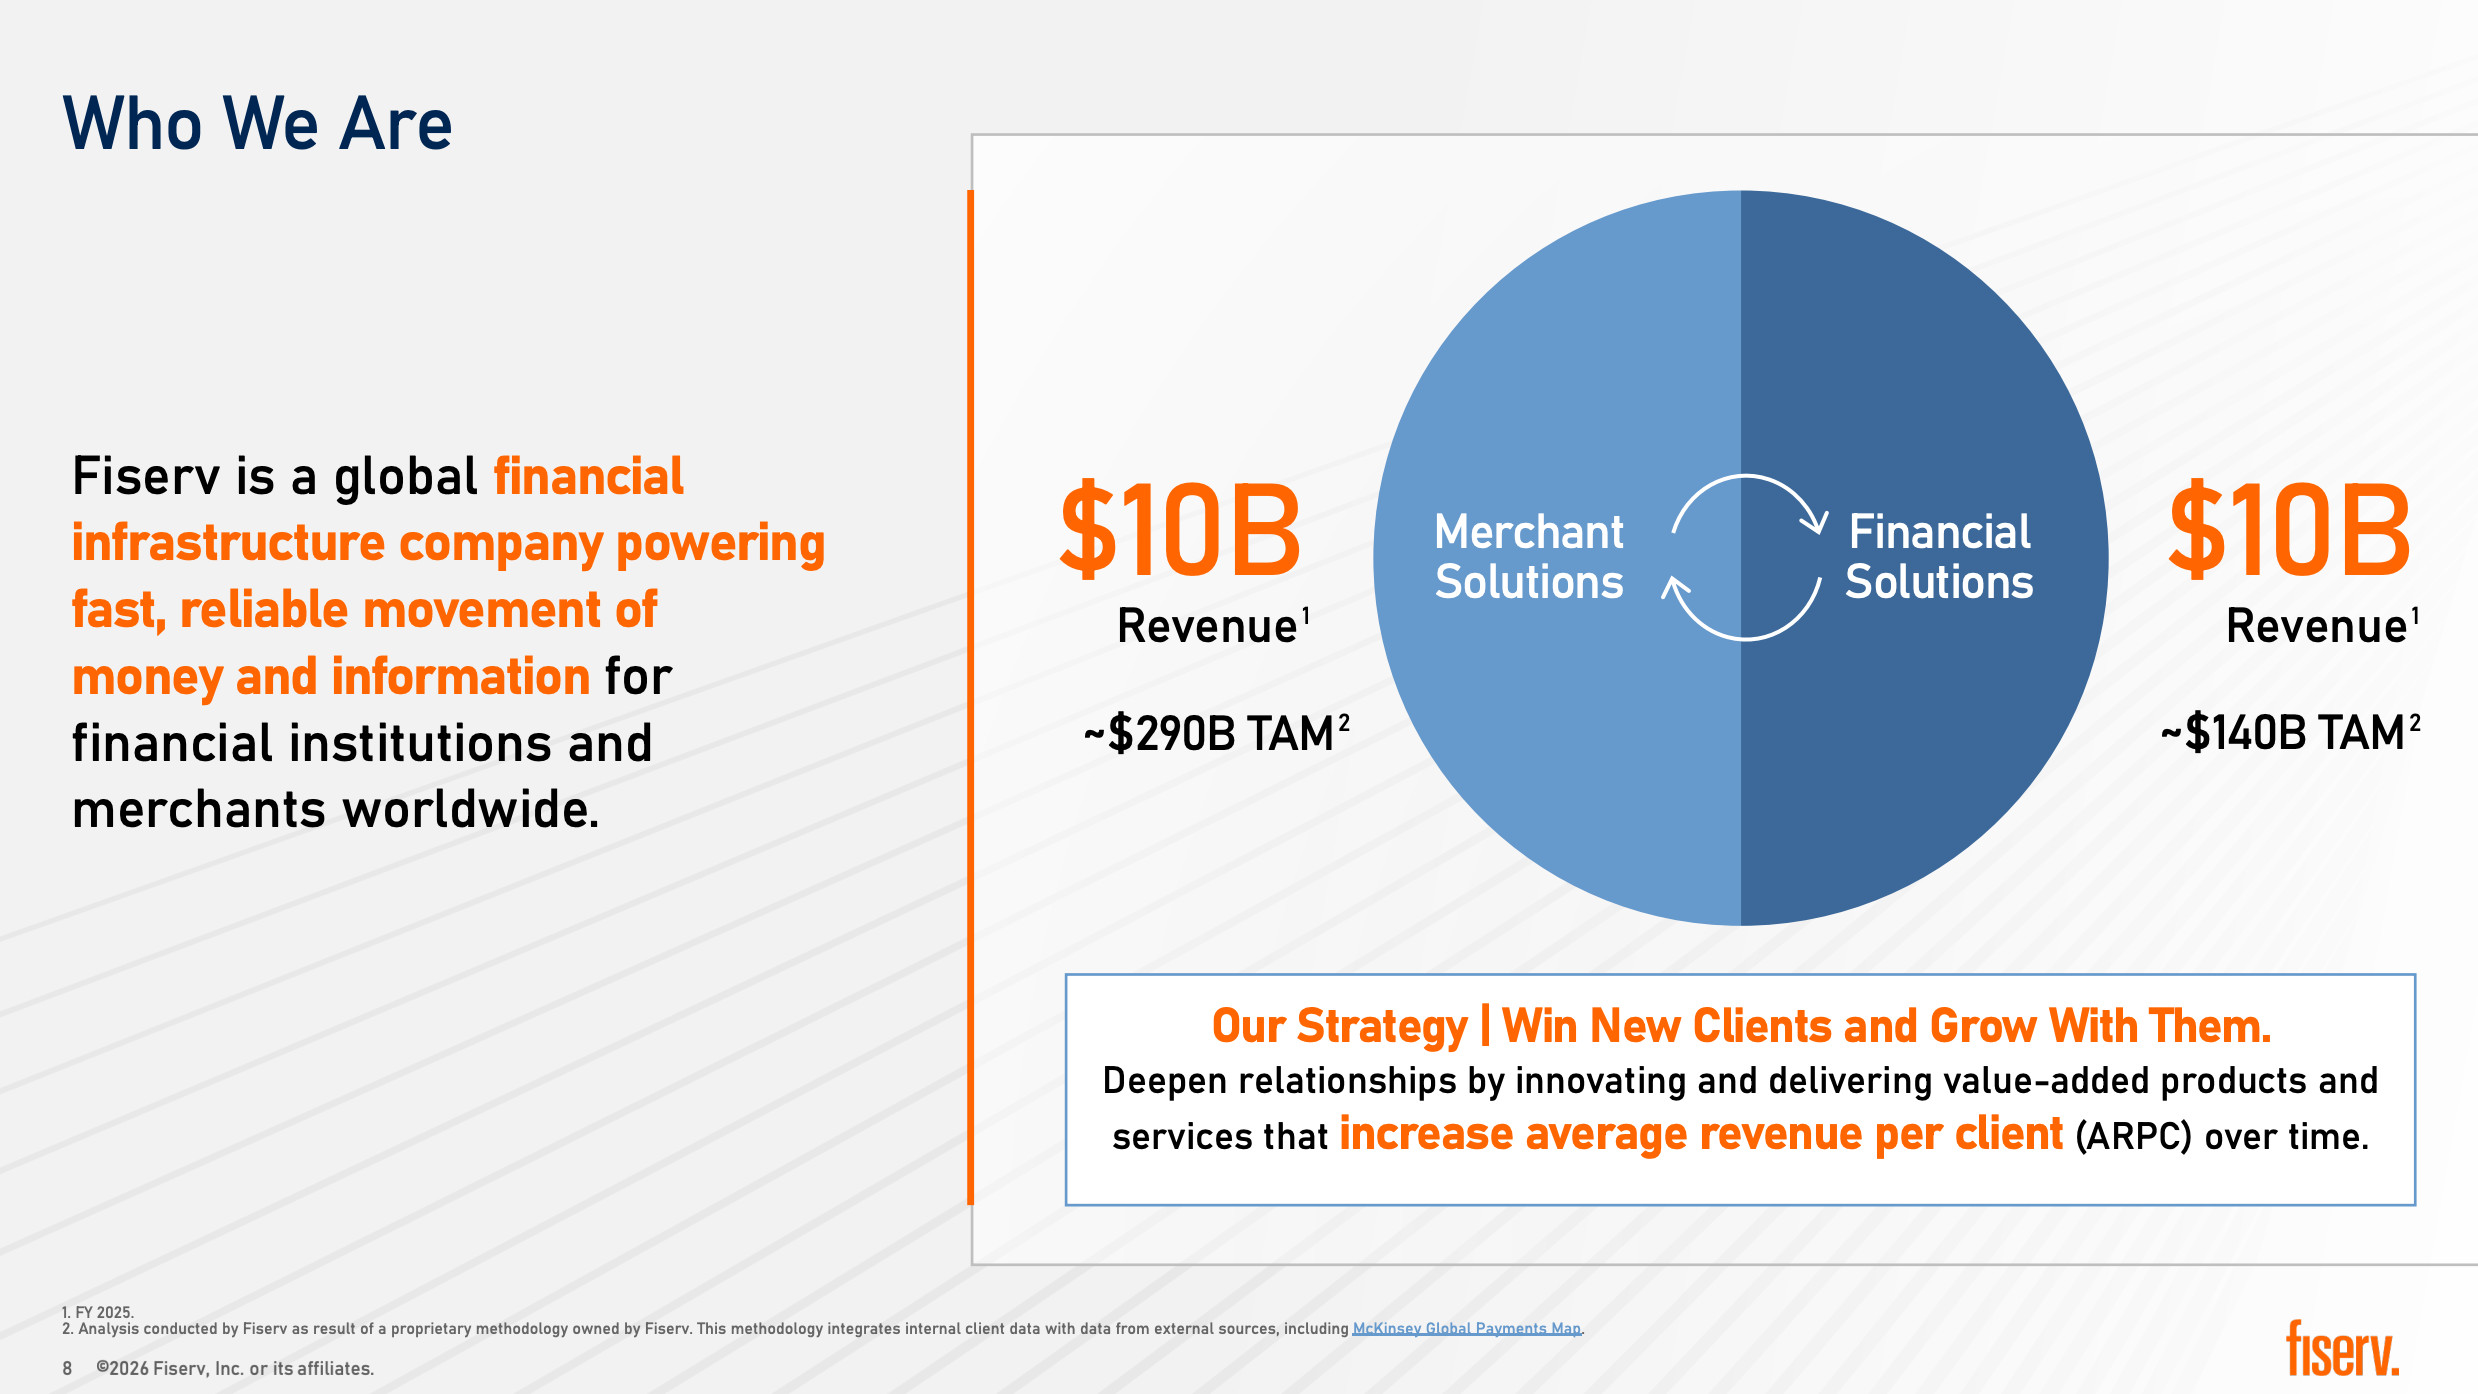
They explore the competitive race against challengers like Mercury and Ramp, the mainframe that has outlived thirty years of obituaries, and where power sits between the AI labs and their distribution channels once inference commoditizes.
Curated Updates
Here are the rest of the updates hitting our radar.
Machine Models
Ethical and Bias Considerations in Artificial Intelligence/Machine Learning - Matthew G. Hanna & Liron Pantanowitz & Brian Jackson & Octavia Palmer & Shyam Visweswaran & Joshua Pantanowitz & Mustafa Deebajah & Hooman H. Rashidi
A Critical Field Guide for Working with Machine Learning Datasets - Sarah Ciston & Mike Ananny & Kate Crawford
AI Applications in Finance
⭐ AI-Driven Payment Systems: From Innovation To Market Success - Merve Ozkurt Bas
The Rise Of Generative Ai Agents In Finance: Operational Disruption And Strategic Evolution - Inesh Hettiarachchi
Financial Modeling in Corporate Strategy: A Review of AI Applications For Investment Optimization - Olufunmilayo Ogunwole & Ekene Cynthia Onukwulu & Micah Oghale Joel & Ejuma Martha Adaga & Augustine Ifeanyi Ibeh
Investment Outlook
⭐ Private Equity Outlook 2025: Is a Recovery Starting to Take Shape? - Bain & Company
⭐ Global Venture Capital Outlook: The Latest Trends - Bain & Company
⭐ Global Private Markets Report 2025: Braced for shifting weather - McKinsey & Company
🚀 Postscript
Sponsor the Fintech Blueprint and reach over 200,000 professionals.
👉 Reach out here.Check out our new AI products newsletter, Future Blueprint. (Don’t tell anyone)
Read our Disclaimer here — this newsletter does not provide investment advice
Contributors: Lex, Laurence, Matt, Farhad, Daniel, Michiel, Luke
For access to all our premium content and archives, consider supporting us with a subscription. In addition to receiving our free newsletters, you will get access to all Long Takes with a deep, comprehensive analysis of Fintech, Web3, and AI topics, and our archive of in-depth write-ups covering the hottest fintech and DeFi companies.