
Gm Fintech Architects —
Busy
Today we are diving into the following topics:
Generative Ventures Update: Market review of (1) Digital Asset Treasuries, (2) Agentic Finance, (3) DeFi Applications, and (4) Robotics and DePIN.
Analysis: We examine the pendulum between centralization and decentralization in financial markets, using Binance’s growing dominance as a case study in the cost of monopoly. Binance’s scale and liquidity have made it the indispensable venue for global crypto trading, yet this concentration of power introduces fragility and systemic risk. The October 2025 flash crash, which wiped out up to $40B in crypto value due to Binance’s oracle and liquidity failures, demonstrates how even high-performing monopolies can destabilize entire markets.
Topics: Binance, CZ (Changpeng Zhao), Tether, Coinbase, JPMorgan, Citi, Ethena, Bybit, Hyperliquid, Trump Administration
To support this writing and access our full archive of newsletters, analyses, and guides to building in the Fintech & DeFi industries, see subscription options below.
Our Ecosystem: AI Venture Fund | AI Research | Lex Linkedin & Twitter | Sponsors
Generative Ventures Update
I recently sent out a market update to the Generative Ventures ecosystem. Below, we share the key takeaways more broadly. I discuss the core drivers of (1) Digital Asset Treasuries, (2) Agentic Finance, (3) DeFi Applications, and (4) Robotics and DePIN below.
Digital Asset Treasuries

Between May and October of 2025, there has been an influx of digital asset treasury companies, primarily into the NASDAQ in the US, but also in other local markets. Most DATs have focused on BTC, following the examples of $90B MicroStrategy and $4B Metaplanet, and thereafter ETH, with $15B Bitmine and $3B Sharplink, followed by Solana, Hyperliquid, ENA, BNB, and other tokens. We are now far on the risk curve for the first wave.
Initially, high mNav multiples of 5-10x sustained ATM equity issuances by DATs, and therefore growing enterprise values and buying pressure on crypto markets. But the current market is pricing most companies in the 0.8-1.3x mNav range, which has created compression in equity values and burned retail investors. There has been no forced selling yet by DATs, because there is no automatic redemption mechanism for investors, and little leverage has been applied. We think contagion risk is small.
There is still capital formation in progress, with motivated token foundations looking for public equity market liquidity in exchange for a discount on their assets. Large holders of ETH, BTC, and other mega-caps are still in the market for potential vehicles. Geographic differentiation is yet to occur.
Models that treat DATs as SPACs are starting to emerge, with the idea of purchasing cash-flow generating businesses in addition to pure token holdings beginning to circulate.
We are engaged on a number of these ideas, exploring second-generation geographic and operating ideas.
⭐ Analyses:
Agentic Finance

One of our main ideas coming into the fund in the last 3 years has been that hardware and software robots will be the core driver of future GDP, and that financial and economic systems will need to be updated in order for this to work. In short, “machine economy” or “robot money”. To that end, we have tracked agentic applications around finance, as well as capital markets activity connected to AI value chains.
Recently, we have seen incumbents move much faster into the space than anticipated. Stripe, through its acquisition of Bridge and Privvy, launch of Tempo, and partnership with OpenAI, and Coinbase, through its work with Anthropic and Google around stablecoin payments integration, have pre-empted the startup ecosystems (e.g., various 402 protocols). AI payment processing, for example, is a competitive field before the consumer has even shown up to the party.
That said, we see Crypto leading agentic finance around implementation of investment and savings strategies, echoing the Roboadvisor sector of 2010 as an Agentic Finance for onchain capital.
We are focusing on “What’s next”. If indeed the fintech incumbents park on this opportunity, will there be value for AI agents outside of the big foundation model companies?
⭐ Analyses:
DeFi Applications

The most commercial outcomes in Web3 over the last 2 years have been Hyperliquid, Polymarket, and Pump.fun. Each of these is a crypto-native capital market. Hyperliquid is worth $40B by replacing FTX in perpetuals trading. Polymarket is worth $9B in equity by using Polygon to host betting / prediction markets. And Pump is trading at $5B as a launchpad, i.e., a crypto-native primary issuer of memecoins.
All are part of the hyperfinancialization and attention economy thesis. Attention is getting shorter. Speculation is the main driver of “value”. Getting rich quickly beats building slowly. We can fight this, or we can accept where human nature is drifting.
Leverage engines like Aave have seen steady success, with TVL as high as $40B, or twice the prior cycle peak. Performance correlates to directional bias in the crypto markets. But we also like that collateralized lending can power use-cases like mortgages or small business loans at the edges.
Payment orchestration with stablecoins is the primary non-speculative example, and Circle’s $30B market cap, Tether’s reported $500B, and Ethena $12B TVL are good evidence. But stablecoins are also the risk-off capital market asset, and only a minority are used for commerce. Real World Assets, or more precisely, the tokenization of fixed income, is another material trend. But again, it largely fits into the risk-off trading use case.
As a result, we are spending more time on DeFi infrastructure that can serve both real-world use cases (e.g., API for DeFi protocols to be integrated into treasuries) as well as plug into the automation of labor. We expect tokenized equities to make their way into neo-brokers and DeFi markets as well.
⭐ Analyses:
Robotics and DePIN

Robotics, and by extension energy and hardware, are ramping up in big tech with high valuations. Companies like Figure, Apptronic, Unitree, and Agility are building out humanoids are constantly in the spotlight. Within crypto, our industry can contribute identity, financial function, and interoperability between these devices. Early approaches focus on crowd-sourcing data to be sold to AI companies for training.
We follow both the DePIN and CryptoAI sectors as they incrementally start to target robotics. However, many companies that have launched these ideas have little traction and product, and their tokenomics have large structural overhangs that result in years of sales pressure without proper demand-side pressure for the token. If the only use of a token is to bootstrap the network as a cost, then it is inevitable that those rewards (farmed by crowds) will be sold, and a negative spiral will result.
Therefore, a number of projects have been caught between a rock and a hard place. Crypto exchange pricing for listings has also negatively impacted this sector, by charging 5-10% of token supply and quickly leading to large sell-offs on launch. Some market participants think they can get around this through market making, but there is little evidence of a successful playbook.
We continue to look for reasonably priced opportunities with entrepreneurs who treat their token and revenue with respect, not as an afterthought.
⭐ Analyses:
How does one succeed in such a dynamic and complex market?
Our approach is to remain disciplined on early-stage valuations and token lock-up terms, target founders who understand the value of distribution and commercial GTM, and tap into larger tech narratives before they hit mainstream consciousness.
We expect another 12 months of a continued risk-on environment, as macro conditions are eased but fiscal conditions worsen. Expect volatility and opportunity.
Analysis
The Cost of Monopoly
There is a pendulum to markets and human nature.
One direction is to organize and centralize through hierarchy, making order from chaos. The other direction is to disperse and break apart, reforming from hyperstructure to new atomic units. Over time, those units compete and centralize again, with the largest becoming the crystal stasis we avoided in the first place. This is the push-pull of the universe.
Economics offers a microcosm of this dynamic. Large banks like JPM and Citi control deposit and money flows. While providing valuable services, they may get opportunistic and charge high unfair fees — minimum account fees to people who can least pay them, high interest on credit cards for people who shouldn’t borrow, interchange on all transactions and so on. And so we have the unbundling brought about by Fintech, and the full decentralization and deregulation that has been the flag of Crypto.
We have shattered the intermediary!
But what happens next? The gap must be filled.
And so it has been. Crypto’s largest winners are enormous — Tether rumored to be raising at $500B for its $300B or so of stablecoin supply. And Binance, the world’s largest crypto-exchange, worth 5-20x more than Coinbase, putting it at somewhere between $400B and $3T in value.
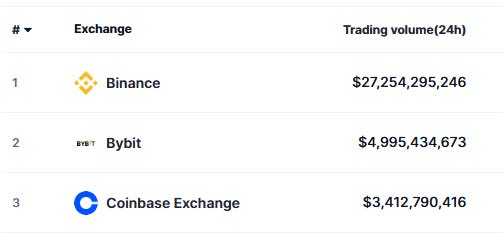
In the beginning, it is convenient to use the largest platform because there are more users, assets, and liquidity than anywhere else. But after a while, you re-discover the cost of centralization, which is the cost of monopoly. A monopoly has control over distribution and enormous returns to scale. The bigger it gets, especially in tech and money, the stronger its network effects become.
The pull of the monopoly is to charge rents, for whatever reason — whether altruistic or not. It also creates centralization risk and fragility of market structure. Whereas a mesh of nodes can resists any particular node being destroyed in a forest fire, a cathedral will not survive if its pillars burn down.
This was the whole point of non-custodial cryptocurrency like Bitcoin, and is at the core of Ethereum’s obsession with decentralization. No node should control the network.
So what are some hidden examples of where things break down?