
Gm Fintech Architects —
Today, we have a guest post from Don Gossen, CEO of Nevermined, an agentic payments company in the Generative Ventures portfolio.

Agentic finance has gotten very hot, so I asked him to dig into what the recent agentic payments launches are missing and where he sees the opportunity still to come.
Summary: AWS, Circle, and Coinbase all shipped agent-payment infrastructure — but all of it is buyer-side, letting agents hold and spend money. Almost nobody is building the merchant side: the acceptance layer that lets a business take payment from an agent across a mess of competing schemes, tokens, stablecoins, chains, and PSPs. Card history says issuance scales fast and acceptance scales slow, so this gap is probably the work of the next decade.
Topics: AWS, Amazon, Circle, Coinbase, Cloudflare, Stripe, PayPal, Braintree, Visa, Mastercard, American Express, Shopify, Spreedly, Primer, BlackRock, a16z, OpenAI, Adyen, Microsoft
To support this writing and access our full archive of newsletters, analyses, and guides to building in the Fintech & DeFi industries, see subscription options below.
🤖🏦🧭 Our Ecosystem:
Generative Ventures | AI Research | Robot Money | Linkedin & Twitter | Sponsors
AI & Robotics Industry Encyclopedia:
In this 100+ page report, we collate all the meaningful companies across public quities, private equity, and digital assets related to the machine economy.
👉Learn more here
The Decade-Long Checkout
The agent economy has built the buyer side. But the merchant side has barely started.
In September 1958, Bank of America mailed 65,000 unsolicited cards to residents of Fresno, California.
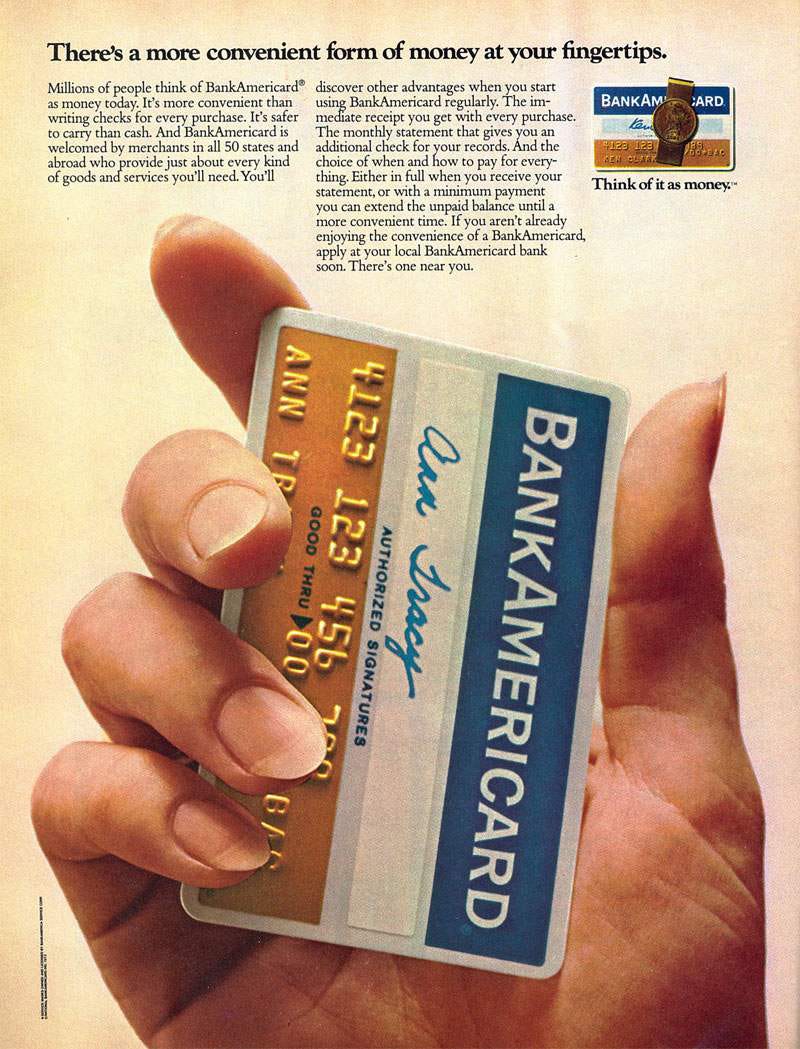
This launched BankAmericard, the first successful all-purpose credit card.
Prior to this, credit cards were merchant-specific, requiring consumers to carry a card for each merchant where they had revolving credit.
The genius of the idea, which ultimately ended up being VISA, was to consolidate those separate cards into one. Two decades later, in 1980, roughly 52% of US households carried a credit card. By 1990 it was 72%. The buyer side of card payments, which includes issuance, wallets, and credit, reached saturation.
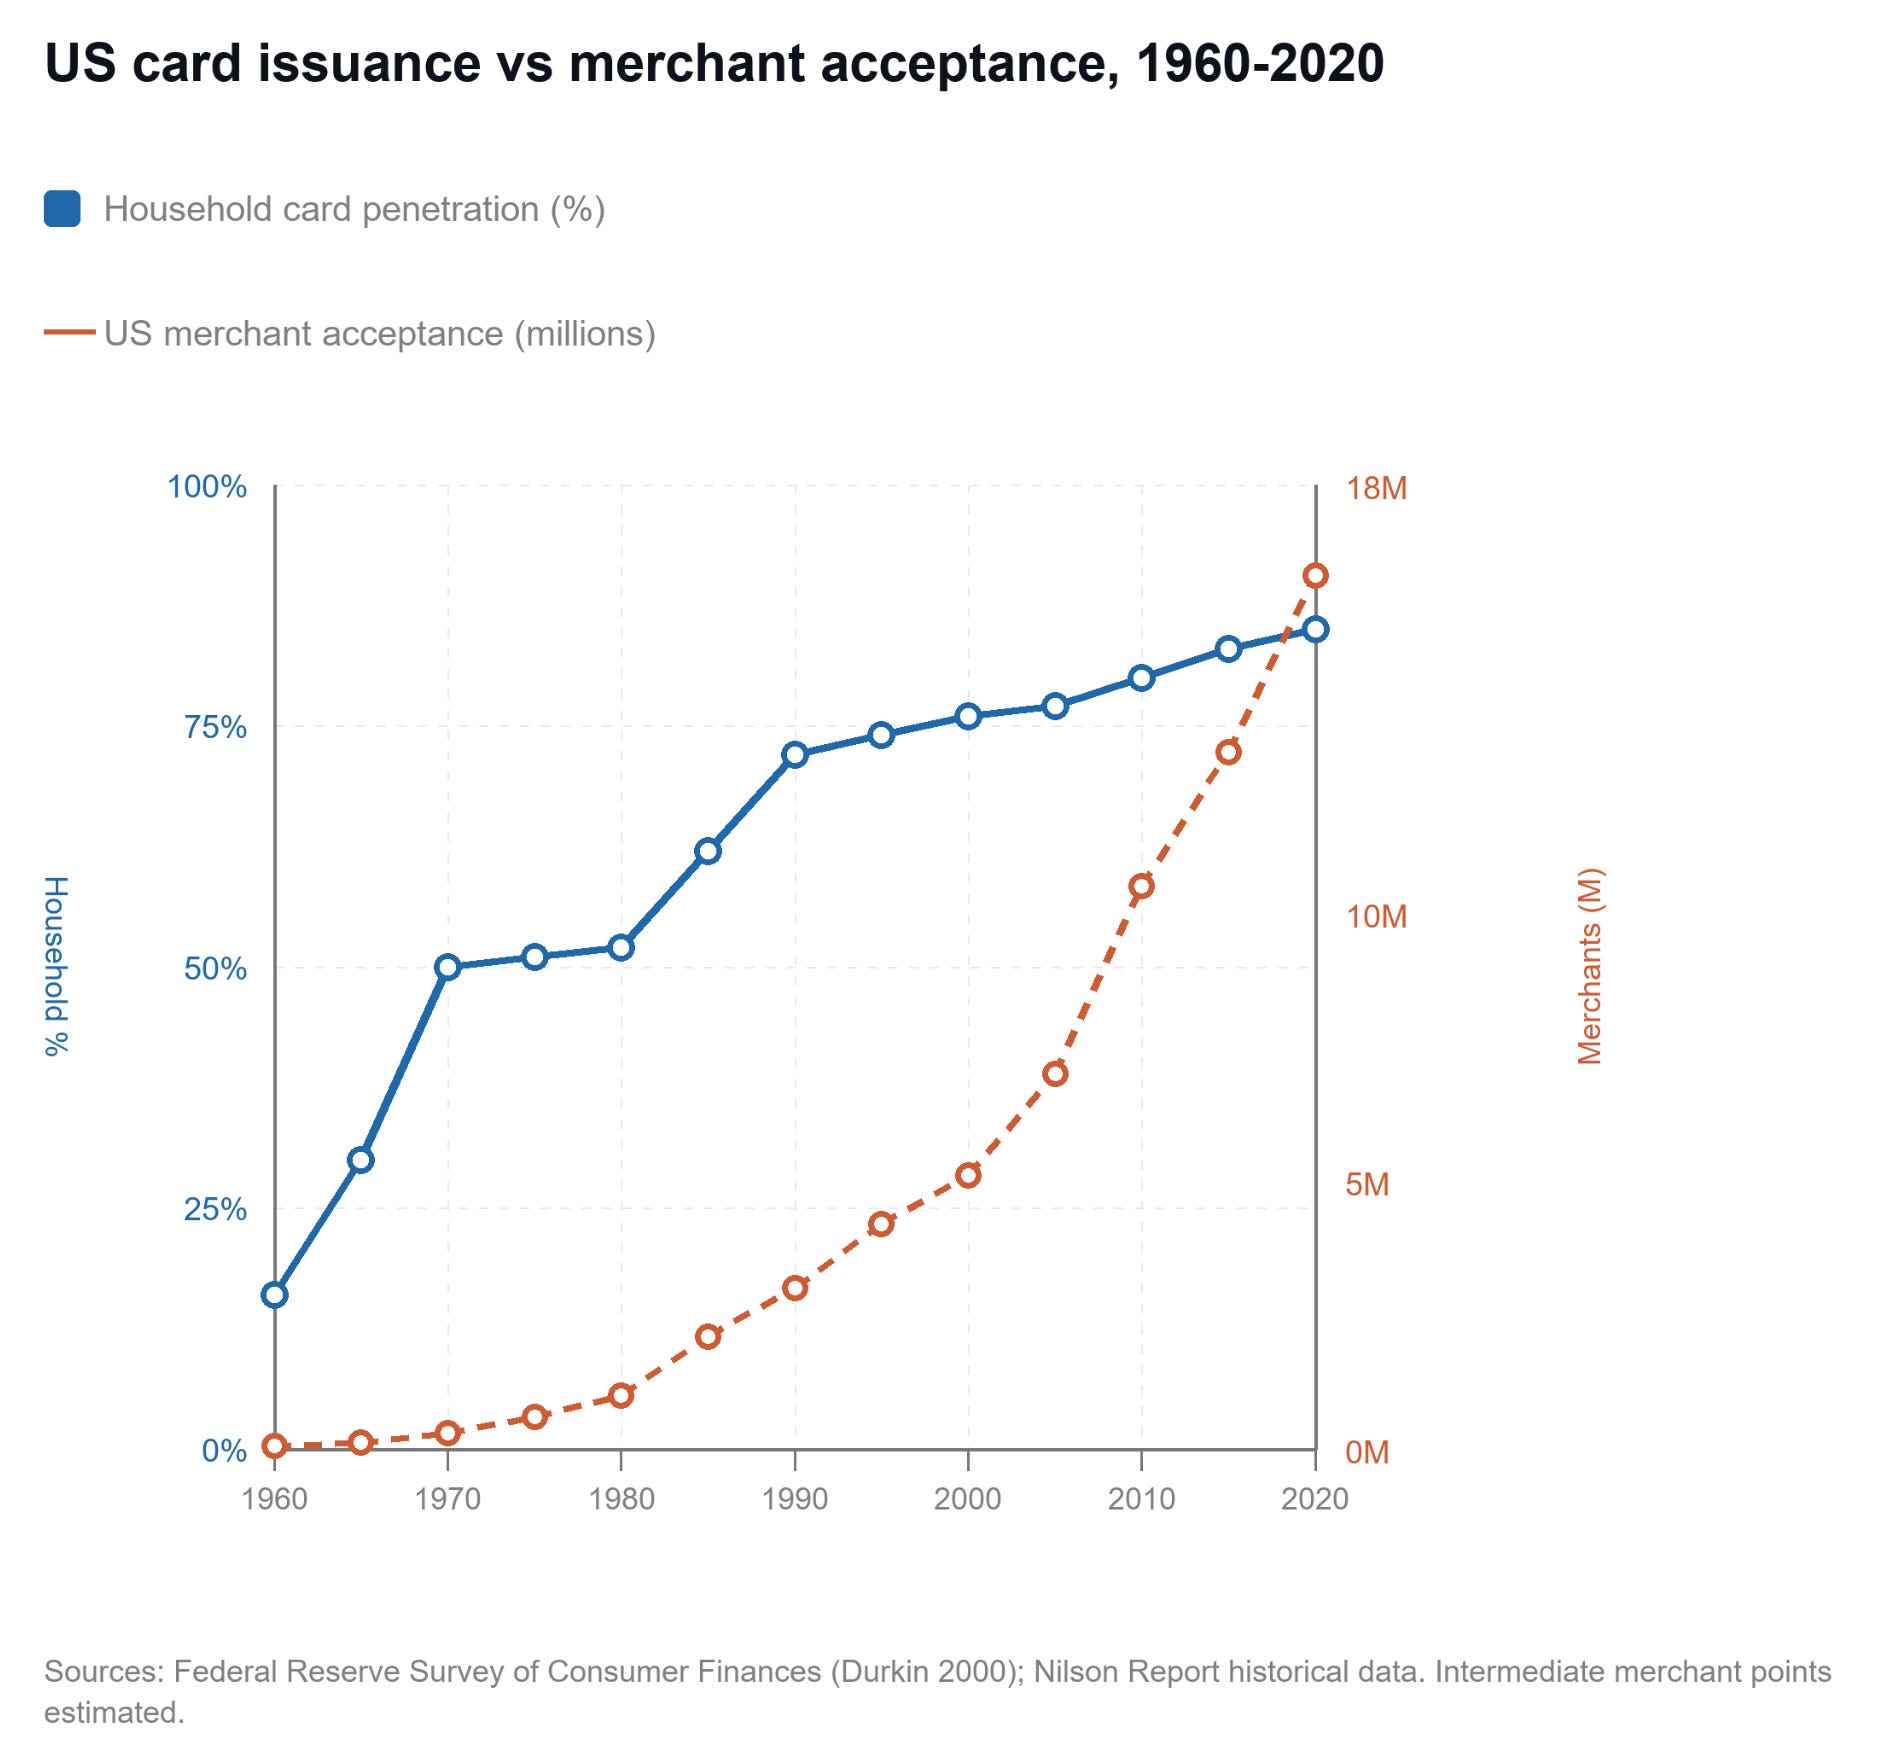
The merchant side, however, definitely had not.
By 1990, the Federal Reserve estimated that only around 2 to 3 million US merchants accepted Visa or Mastercard cards. And even then, merchant acceptance was largely restricted to travel, dining, and department stores. It was not until the late 90s and early 2000s that the ubiquity of credit cards began, largely due to the Internet and the growth of e-commerce.
We are watching the same process repeat with AI agents.
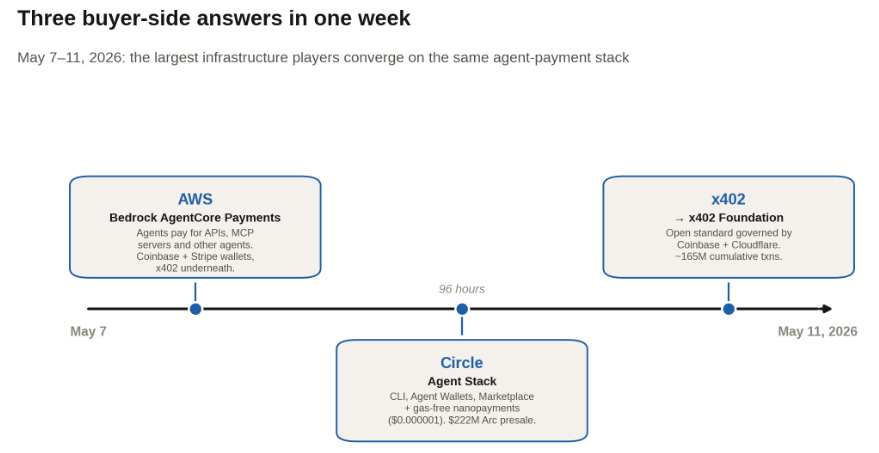
In a 96-hour window, between May 7 and May 11, 2026, AWS, Circle, and Coinbase shipped their answers to the agent-payment question. They distributed the equivalent of BankAmericards to the agentic masses. But the side of the transaction that has to receive money via a new form of payment has largely been ignored.
The buyer side
On May 7, AWS announced Amazon Bedrock AgentCore Payments, built with Coinbase and Stripe. AI agents inside AWS infrastructure can now pay for APIs, MCP servers, web content, and other agents. Developers pick a Coinbase wallet or a Stripe Privy wallet. Users top up funds in stablecoins while settlement takes place on-chain.
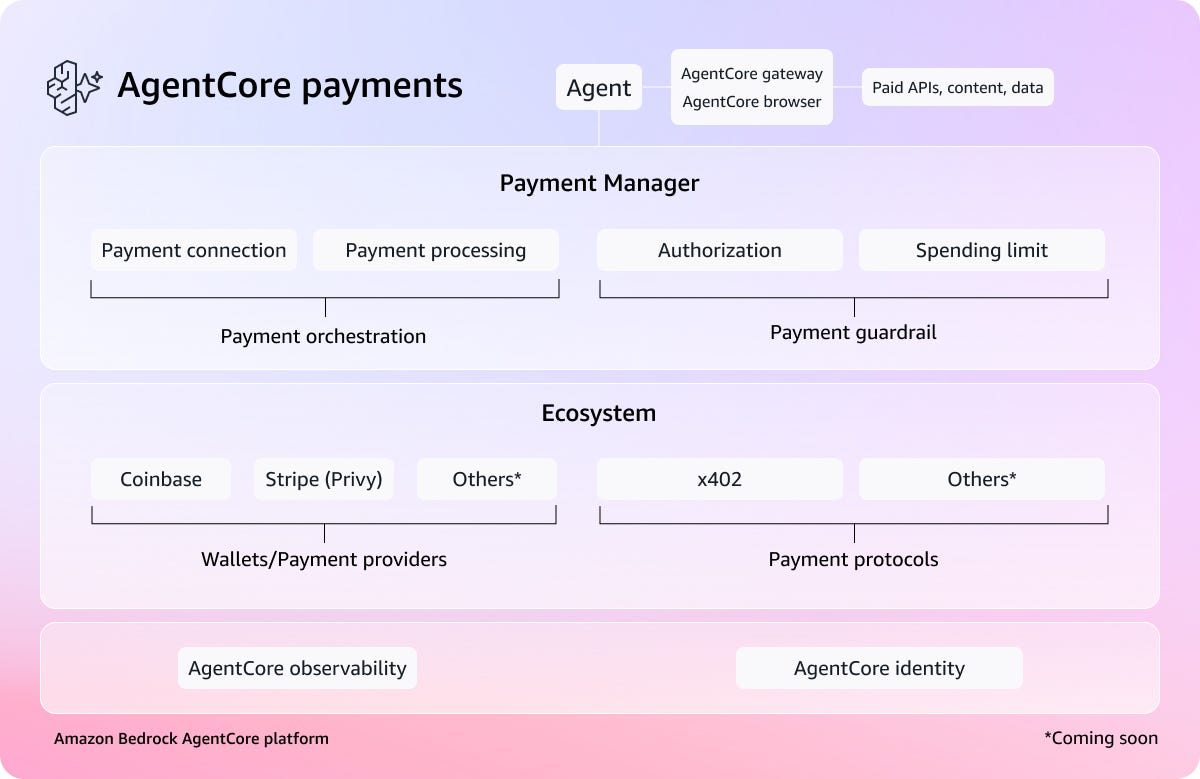
AWS did not build their own rail.
They picked from existing or emerging standards and existing wallet solutions. The largest cloud provider in the world is treating x402, Coinbase, and Stripe as consolidation points for agent payments.
Four days later, Circle shipped Agent Stack, including Circle CLI, Agent Wallets, an Agent Marketplace, and Circle Gateway-powered nanopayments. Nanopayments are USDC transfers as small as $0.000001, gas-free, at machine speed. Circle also raised $222M in an Arc token presale from BlackRock and a16z, which we covered here.

As for Coinbase, x402 had cleared roughly 165 million transactions and about $50 million in cumulative settlement volume by late April 2026, mostly across Base and Solana, with around 69,000 active agents. Governance moved to the x402 Foundation, formed by Coinbase and Cloudflare. A year ago, x402 was a whitepaper.
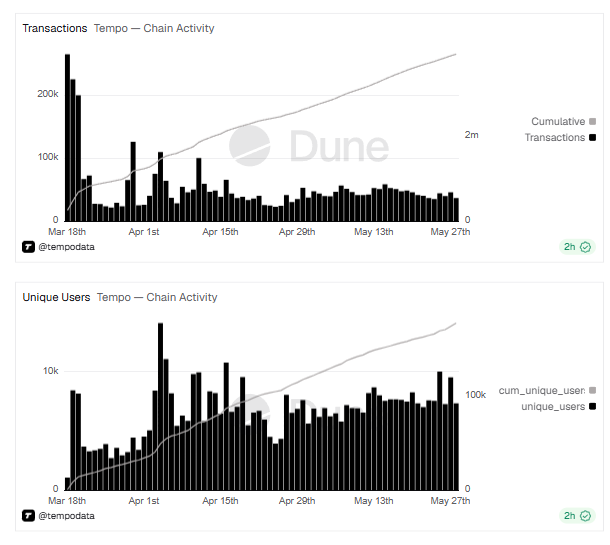
By April, it was clearing nine-figure transaction counts on live rails — though one on-chain analysis shows that daily volume has fallen sharply from a December peak.
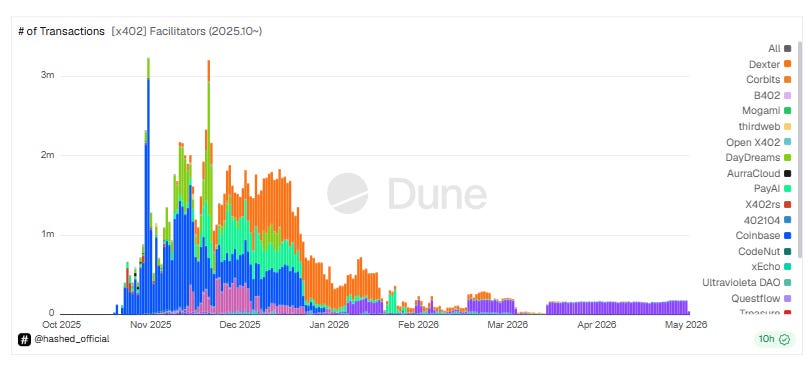
The buy-side primitives include wallets, spending controls, micropayments, protocol standards, programmable mandates and cryptographically signed authorizations. Every major infrastructure player who has shipped agent-payment infrastructure in the past month has converged on the same buyer-side primitives.
The question of whether AI agents can hold and spend money has been answered. The unsolicited cards have now been distributed.
The merchant matrix multiplication
What is not solved well is the part of the network that has to accept the payment.
A merchant who wants to accept agents as consumers today faces a fragmentation matrix the card era never produced. The schemes are splintering:
Visa Intelligent Commerce, Mastercard Agent Pay, American Express Agentic Commerce Experiences, with the other card networks quickly following with their own offerings.
On the PSP side, Stripe leads the agentic charge. Secure Payment Tokens, Link for agents, Stripe Agent Toolkit, Machine Payment Protocol, and more have Stripe taking up positions across the entire agentic payments landscape.
PayPal has leaned into agentic payments through partnerships with the likes of OpenAI.
The solutions are a jumble from a merchant perspective. Each has a different mandate format, a different token issuance flow, different validation rules at authorization time, and a different fee structure depending on the type of agentic transaction.
A merchant who supports Visa agentic tokens but not Mastercard Agent Pay loses the Mastercard agent population. The reverse is also true.
Then there are the token types. Network agentic tokens, like Visa’s VIC tokens carry mandate metadata, are issued by the network, store agent spend policy information, and are designed to route across any PSP that supports the network scheme. They are intended to be portable.
Gateway tokens, on the other hand, like Stripe’s or Braintree’s vaulted tokens, are scoped to a specific gateway, carry less metadata, and lock the merchant into that gateway’s environment. Most agentic merchants will want to accept both. Few are configured to.
The stablecoin side adds another axis. USDC, USDT, PYUSD, Circle Gateway-issued instruments. Each settles on a different chain: Base, Solana, Ethereum, Polygon, Arc, Tempo, with other agent-focused L1s and L2s in flight. Each chain carries different gas costs, finality periods, and acceptance fingerprints.
The issue for merchants is complexity, both in set up and in support. Most merchants, even those built for an AI powered world, don’t know where to start. Lack support for specific agentic tokens or PSPs, and you risk losing agent buyers. Accept too many and the cost of monitoring, risk underwriting, and book reconciliation balloons.
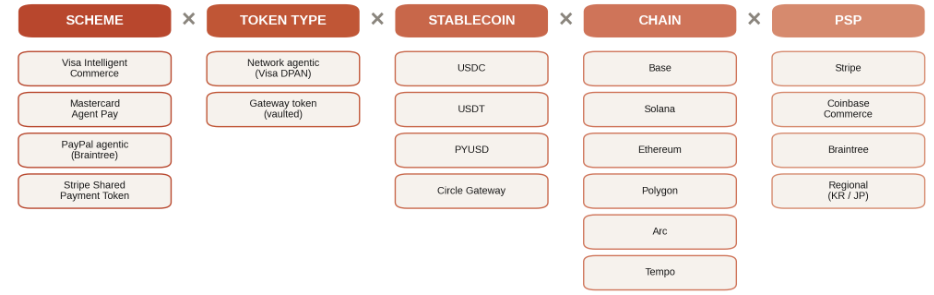
This means four to six new integrations and two or three new vendor contracts. Most merchants will pick one rail, accept a small slice of agent traffic, and wait for someone to solve the consolidation problem, rather than doing it themselves.
Issuance fast, acceptance slow
Buyer-side payment infrastructure has natural distribution. A wallet ships to a user. The user adopts. The product is consumer software with viral coefficients. Issuance scales like a startup.
Merchant acceptance does not. Every new merchant is a bespoke integration, a contract negotiation, a settlement reconciliation, a risk underwriting decision. The economics are different as well. There are merchant acquirers and aggregator platforms, but they are incumbents with existing solutions.
US credit card issuance went from one bank in 1958 to 72% household penetration by 1990, which took about thirty years. Merchant acceptance went from 400,000 US merchants in 1969, to 3 million in 1990, to 10 million-plus today. And online merchant acceptance was not really solved until Stripe and PayPal Braintree consolidated the integration cost and simplified network scheme adoption in the 2010s.
Issuance took three decades. Acceptance has taken more than six and still isn’t done.
The same asymmetry is now visible in agents. AgentCore Payments went from announcement to preview product in a single quarter. Circle Agent Stack shipped four products at once. The buyer side moves fast because the products are simpler to deploy: a wallet, a CLI, a marketplace.
The merchant side does not, because the products are complex infrastructure and harder to sell and integrate. We should expect the agent acceptance buildout to take years, not quarters.
The question is who builds it. So what are the candidates?
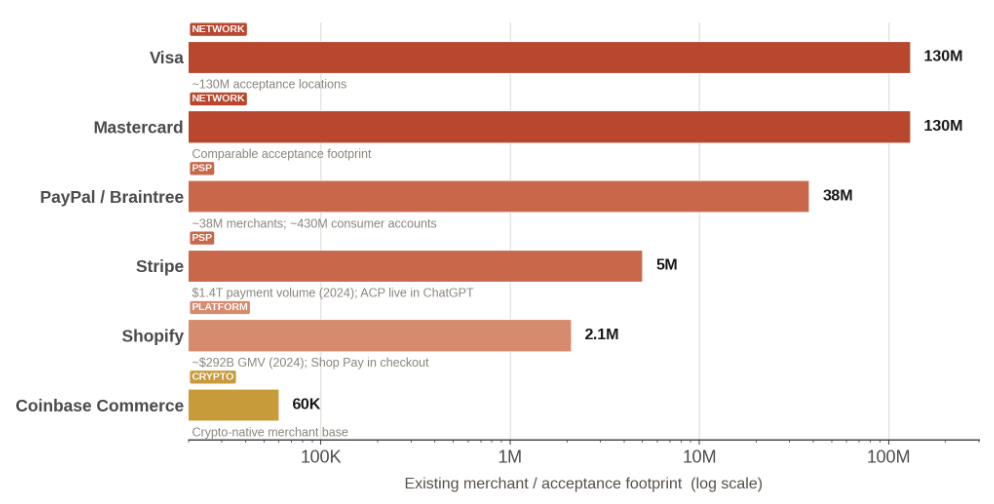
The PSPs. Stripe already sits in the middle of the AgentCore announcement and processed nearly $2 trillion in payment volume in 2025, around 2% of the global total. They have deep merchant relationships. They have Bridge for stablecoin disbursements and Privy for wallet integration. PayPal Braintree is the parallel candidate, with 430 million consumer accounts and several million active merchants, plus an announced agentic checkout and their own stablecoin offering, PYUSD, to lean on.
The commerce platforms. Shopify sits on roughly $300 billion in 2024 gross merchandise volume across 2 million merchants, with Shop Pay built into the checkout. The platform model means Shopify can update the checkout experience across millions of stores in a single product release, the way Apple Pay rolled out across iOS in a quarter. If Shopify ships agent acceptance as a default inside Shop Pay, the merchant side gets several million stores in a quarter.
The card networks. Visa and Mastercard have spent fifty years operating the dual-network model that solved card acceptance. Each has jumped into the agentic payments space with agent-specific token issuance through Visa Intelligent Commerce and Mastercard Agent Pay. Today, Visa reports more than 130 million merchant acceptance locations globally; Mastercard reports comparable scale.
An agentic acceptance product needs to translate between network agentic tokens and gateway tokens, so a merchant contracted with Stripe can accept a buyer whose mandate was issued by Mastercard.
It should route stablecoin payments across chains and issuers based on cost, finality, and the merchant’s policy. It must surface agent identity to the bank’s risk engine at authorization, in a format the underwriter can attach policy to, regardless of whether the credential is a card token or a wallet signature.
Finally, it maintains a single audit trail and a kill-switch that propagates through every downstream wallet, PSP, and network in seconds.
That is the spec. No one has shipped it yet.
Which leads to a fourth possibility:
New horizontal orchestrators sitting above the network schemes and gateways. Agentic payment orchestration is a different business from operating any one rail. In cards, that was Spreedly and Primer, both of which built on top of the schemes without competing with them.
The question for agents is whether the fragmentation is large enough to create a new venture-scale neutral player.
What happens now?
If the card analog holds, building the merchant side is the work of the next decade.
The candidates are already visible. Stripe, Braintree, Shopify, Visa, Mastercard, Coinbase Commerce, and a small set of horizontal orchestrators. Cards showed that issuance and acceptance scale on different curves, with different economics.
The company that solves acceptance is not always the company that solves issuance.
Fifty-two years after Fresno, Stripe was an answer to a problem that still had not been solved. We will see how long it takes this time.
🚀 Postscript
Sponsor the Fintech Blueprint and reach over 200,000 professionals.
👉 Reach out here.Check out our AI newsletter, the Future Blueprint, 👉 here.
Read our Disclaimer here — this newsletter does not provide investment advice
Great analysis. Adyen`s newly launched commerce suite seems to be the first comprehensive approach to adress the merchant side.
Really sharp framing -feels like we’re moving from “building agents” to designing the protocols and markets they operate in.