
GM Fintech Futurists,
Today, we highlight the following:
DIGITAL ASSETS: TradFi Wraps Crypto. DeFi Wraps TradFi.
ANALYSIS: Google, Shopify, and the Infrastructure Layer for AI Shopping
CURATED UPDATES: Financial Institutions and Adoption; DeFi and Digital Assets; Blockchain Protocols; NFTs, DAOs and the Metaverse
To support this writing and access our full archive of newsletters, analyses, and guides to building in Fintech & DeFi, subscribe below (if you haven’t yet).
🤖🏦🧭 Our Ecosystem:
Generative Ventures | AI Research | Robot Money | Linkedin & Twitter | Sponsors
AI & Robotics Industry Encyclopedia:
In this 158 page report, we collate all the meaningful companies across public equities, private equity, and digital assets related to the machine economy.
👉Learn more here
DIGITAL ASSETS: TradFi Wraps Crypto. DeFi Wraps TradFi.
A year ago, Morgan Stanley's 15,000 financial advisors couldn't recommend a single Bitcoin product to clients.
Now the firm has the market's cheapest spot Bitcoin ETF and Goldman is filing for one. Schwab is building a crypto trading desk. Legal & General is bringing $68 billion in money market funds on-chain. And the S&P 500 trades 24/7 on a decentralized exchange.
The question we keep coming back to: who ends up owning this infrastructure — the banks who own the clients, or the chains that can settle anything at 3am on a Sunday?
The TradFi wrapper
Morgan Stanley's spot Bitcoin ETF, MSBT, pulled in more than $100 million in its first week. This has been the firm's most successful ETF launch to date, priced at 0.14% annually, and the first spot Bitcoin ETF issued by a major US bank.
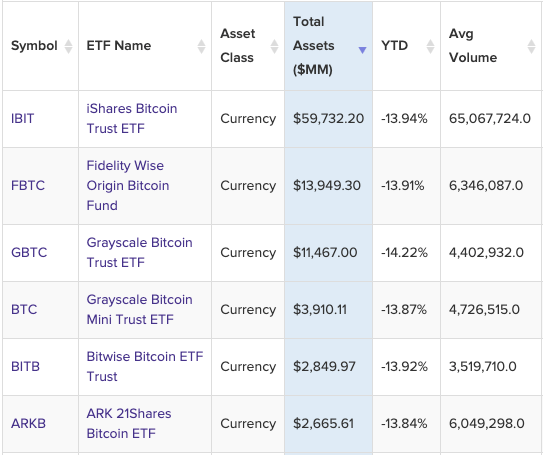
Even so, it is far from the biggest. BlackRock's IBIT crossed $1 billion in inflows within its first week of trading in January 2024 and has since accumulated over $65 billion in total net inflows. MSBT is on track for over $7 billion this year.
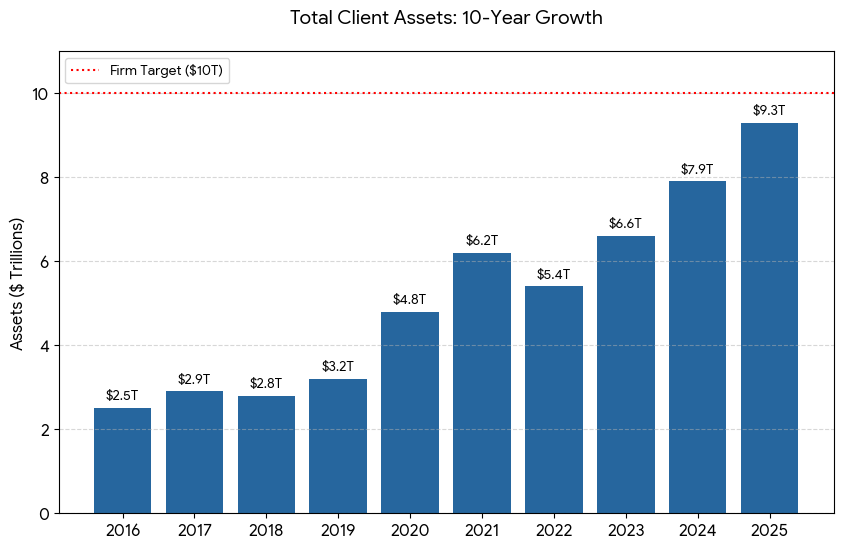
Morgan Stanley’s wealth management network oversees trillions of dollars in client assets. It’s a channel for investors who would never open a Coinbase account, but will buy an ETF through their existing advisor.
Wall Street firms travel in packs, and we saw Goldman Sachs file for its own Bitcoin ETF within days of MSBT’s launch.
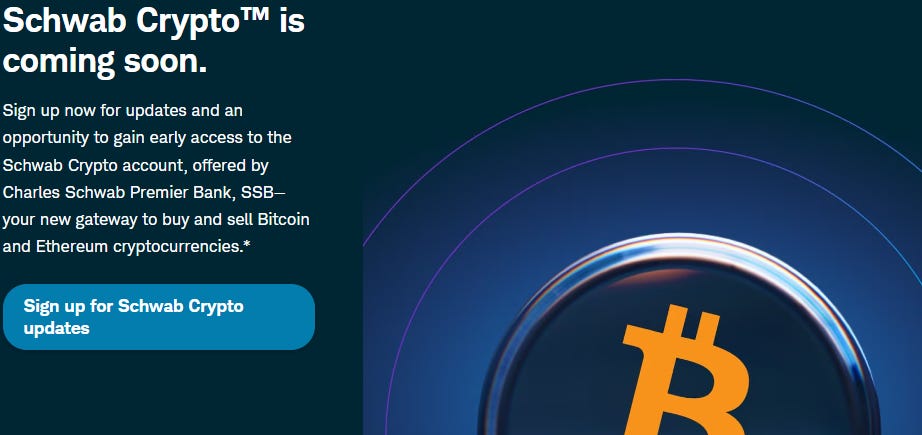
Charles Schwab also confirmed it remains on track to launch spot Bitcoin and Ethereum trading in the first half of 2026, via its Charles Schwab Premier Bank unit. Schwab manages $12 trillion in client assets across 39MM active brokerage accounts.
Importantly, it famously drove stock trading commissions to zero in 2019.
Will it do the same to crypto? This is particularly relevant as the fee gap with native crypto exchanges is significant
Coinbase Advanced charges makers up to 0.40% and takers up to 0.60%
If Schwab applies its equities pricing to crypto, the compression on native exchange margins could be significant, particularly when considering the cost of acquiring these assets directly on-chain.
The ETF, the custody account, the brokerage interface, these are all wrappers that distribute product. They are the store that sell the sandwiches, the sandwiches being financial products. The incumbents are competing to own the client relationship, and the underlying asset is incidental to that contest.
The Perpetual Trade
DeFi is running the same play in reverse, pulling traditional assets onto the chain rather than wrapping crypto into brokerage accounts.
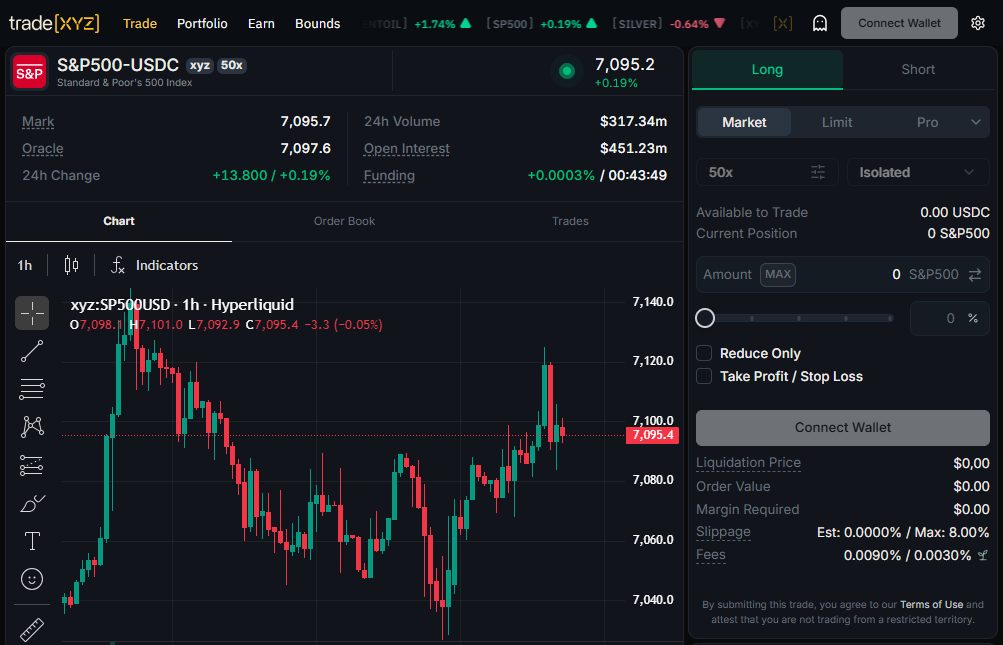
On March 18, S&P Dow Jones Indices licensed the S&P 500 to Trade[XYZ] to launch the first officially licensed perpetual derivative contract based on the index, trading on Hyperliquid. Earlier attempts relied on synthetic pricing. This contract runs on institutional-quality index data from the source, and S&P DJI powers trillions in ETF and index fund assets globally. That data provenance is what institutional confidence follows.
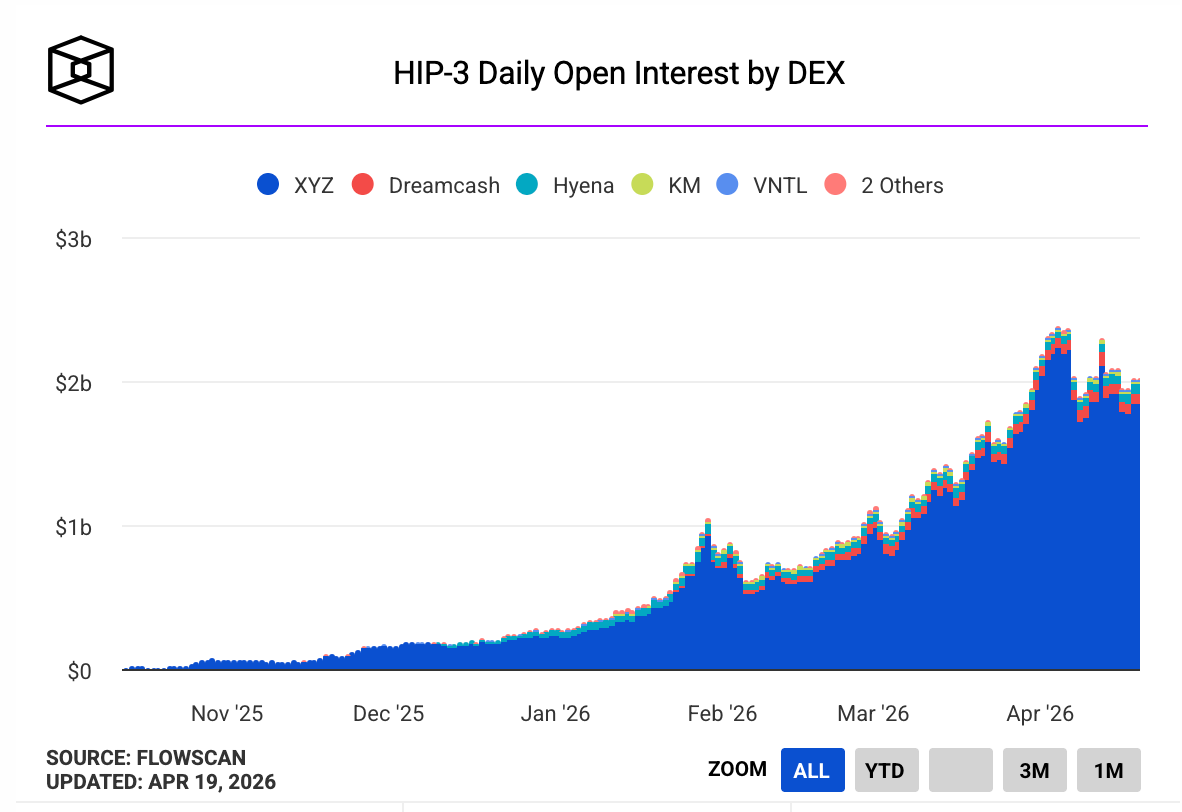
HIP-3 is Hyperliquid’s framework for permissionless perpetual futures on tokenized equities and commodities, where builders spin up new markets by staking HYPE.
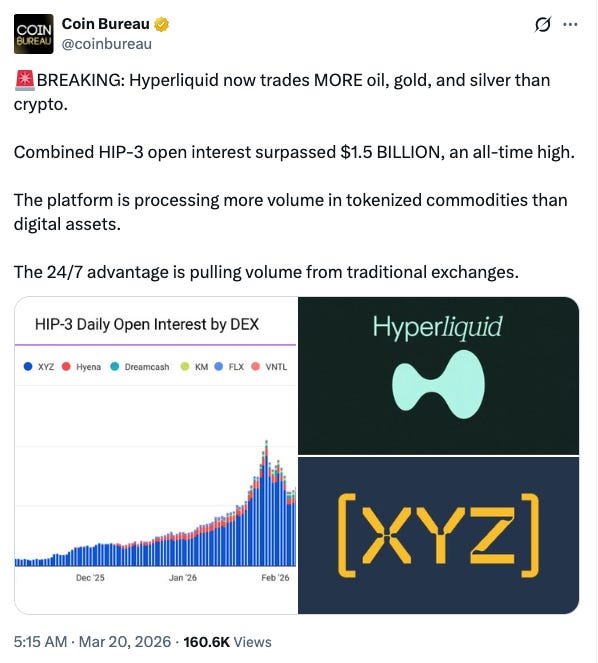
Open interest hit a record $2.38 billion last week, up roughly 580% year-to-date from around $280 million at the start of the year — crossing $1 billion within the first month. TradeXYZ accounts for over 90% of that. We’d watch the $5 billion mark. At that level, HIP-3 starts generating enough volume and liquidity to attract the market makers who currently operate on CME and CBOE.
A note: this product is currently restricted to eligible non-US investors, so it won’t compete with Morgan Stanley or Schwab for the time being.
As of the week of the S&P announcement, only seven of the top 30 markets on Trade[XYZ] by open interest were crypto pairs. The rest were tokenized or synthetic versions of commodities and equity indexes, like oil, gold, silver, and now the S&P 500. The crude oil contract alone saw $1.7 billion in peak daily volume and $300 million in open interest, driven in large part by CME traders who found they could trade oil on weekends during the Iran conflict when conventional markets were closed.
When a major macro event breaks on a Saturday, traditional exchanges are shut. On-chain perpetuals aren’t. All of a sudden, all of our equities and commodities are digitally native and globally available.
Where This Converges
Morgan Stanley, Goldman, and Schwab are wrapping crypto into existing brokerage infrastructure. Hyperliquid is absorbing equities and commodities into on-chain settlement — oil, gold, the S&P 500, all trading 24/7 without intermediaries. Only three of the top ten markets on Hyperliquid by volume are crypto pairs. Traditional finance volumes are arriving on-chain and will increasingly make up the bulk of blockchain activity.
Morgan Stanley still has its clients. S&P DJI still licenses its index. But the S&P 500 now trades on a decentralised blockchain at 3am on a Sunday.
How long before someone asks why the NYSE doesn’t?
👑 Related Coverage 👑


Analysis: From Boom to Bust in the $30B DAT Trade
We look back at the Digital Asset Treasury sector — over 200 publicly listed companies that have adopted the Strategy playbook of holding crypto on their balance sheets.
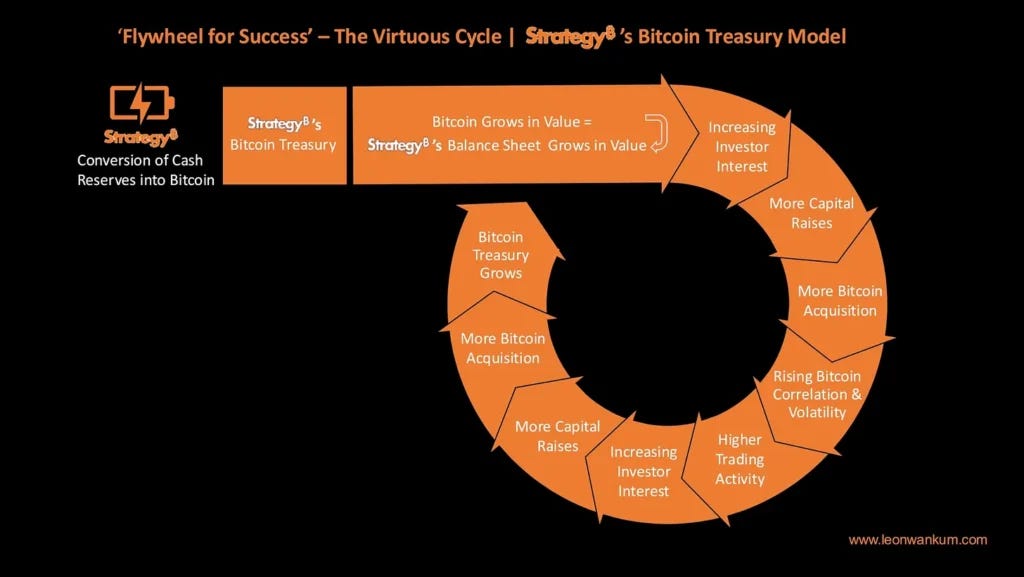
We covered the early DAT wave in detail last year, when the mNAV premium flywheel was still spinning, and every micro-cap healthcare company was pivoting to become a Solana treasury. Now, roughly 40% of BTC treasury companies trade below the value of their holdings. The flywheel that powered $29B in capital raises through 2025 has jammed. We tracked 200+ companies across the DAT strategies. The picture it paints is uncomfortable, but instructive. This is the first real stress test of whether the DAT model works as a financial structure when prices go the wrong way for long enough.
Curated Updates
Here are the rest of the updates hitting our radar.
Financial Institutions and Adoption
American Express Debuts Agentic Commerce Experiences (ACE)™ Developer Kit and Announces Industry-First Protection for Registered Agent Purchases - American Express
Visa Launches Validator Node on Tempo Blockchain - Visa
EToro to acquire crypto wallet Zengo in $70 million deal - CoinDesk
UK asset manager puts $68 billion of funds on-chain via Calastone token network - CoinDesk
Goldman Sachs files for bitcoin income ETF in crypto push - CoinDesk
Payward to acquire Bitnomial, creating a fully CFTC-licensed derivatives platform - Kraken
DeFi and Digital Assets
HIP-3 open interest tops $2 billion as demand for 24/7 tokenized equity exposure surges - The Block
Coinbase adds ‘DeFi mullet’ to UK offering in drive to become an everything exchange - DLNews
Blockchain Protocols
Drift degen sues Circle, alleging stablecoin giant ‘did nothing’ during $295m hack - DLNews
Aave launches v4 on Ethereum as founder eyes ‘opportunities in the real world’ - DLNews
NFTs, DAOs and the Metaverse
Kelp DAO $293 Million Hack Largest DeFi Theft of 2026 - PYMNTS
Polymarket seeks $400 million raise at $15 billion valuation: report - The Block
🚀 Level Up
Join our Premium community and receive all the Fintech and Web3 intelligence you need to level up your career. Get access to Long Takes, archives, and special reports.
Sponsor the Fintech Blueprint and reach over 200,000 professionals.
👉 Reach out here.Check out our AI newsletter, the Future Blueprint, 👉 here.
Read our Disclaimer here — this newsletter does not provide investment advice
Spot on, Lex. It’s the classic 're-intermediation' of a decentralized movement. As a CFA, I see this as the inevitable convergence of technology and capital banks are finally realizing that if they don’t provide the rails for digital assets, they’ll eventually lose the deposits.
The question is: once the banks have the crypto, does it still function like crypto, or just another ledger entry in a shiny new box? Fantastic read as always."