
Hi Fintech Futurists —
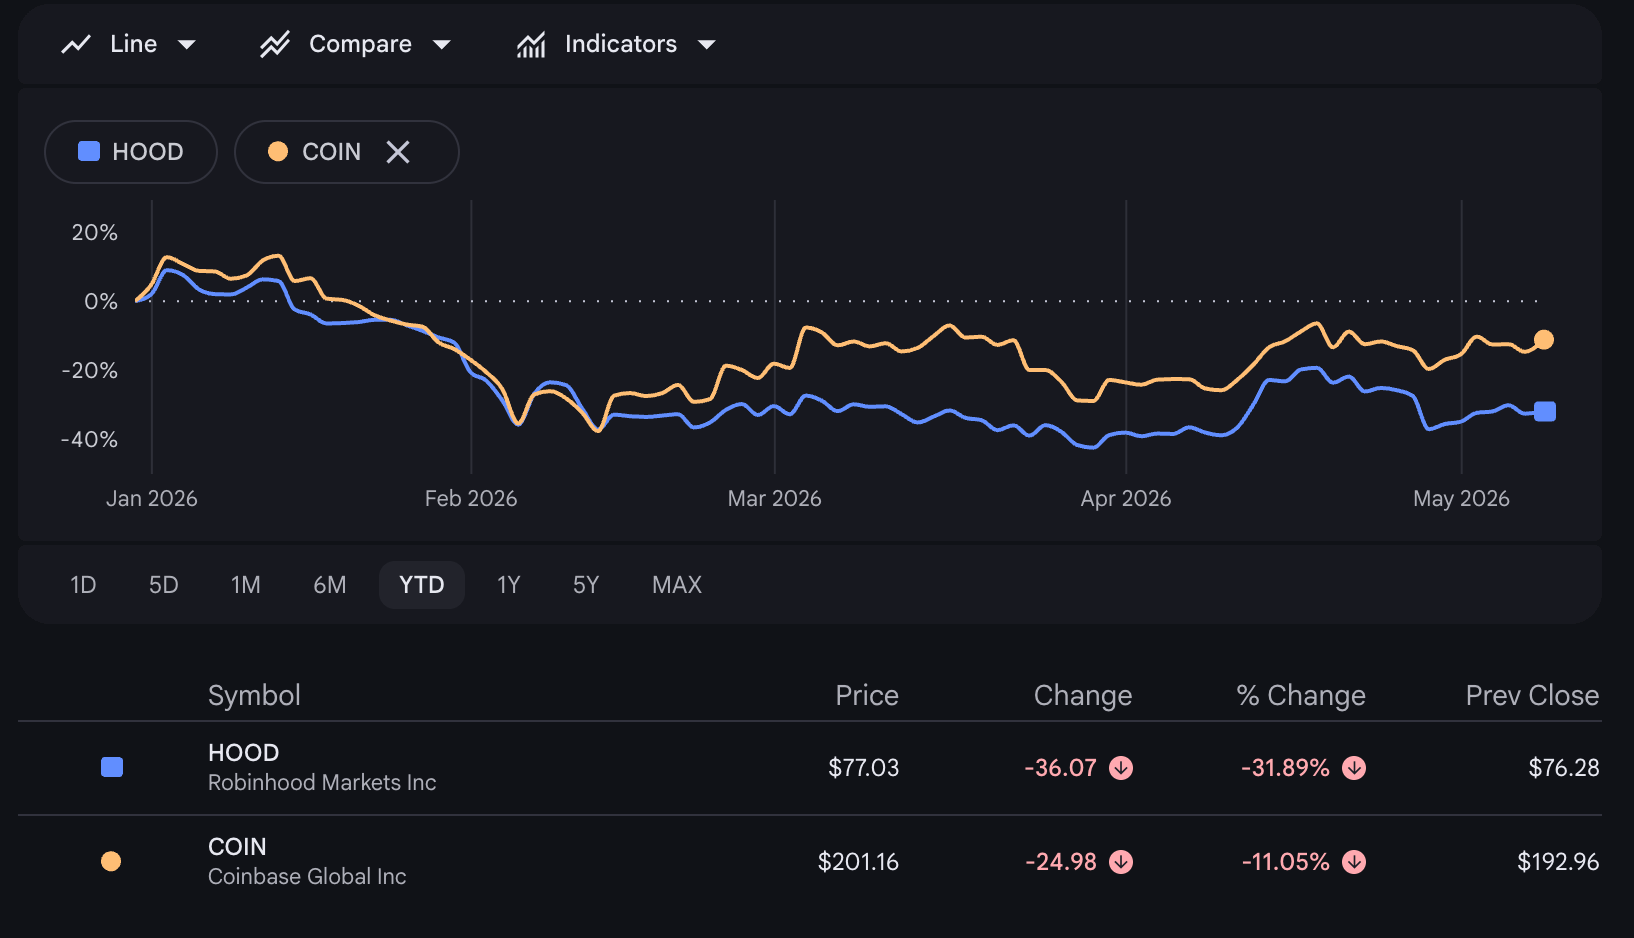
Both Robinhood and Coinbase missed analyst estimates last week as a prolonged crypto downturn dragged on trading activity, sending their shares down -13% and -5% on the news respectively, wiping off $12B of value.
We believe it exposes a deeper challenge for exchanges and neobrokers, who could be at a structural disadvantage as fintechs race to become holistic financial platforms for users. With the majority of revenue tied to volatile transaction fees on retail trading, investing into other financial products becomes much harder. We explore this theme through the lens of Coinbase’s exchange model, the broader consumer trading business of Robinhood, and the payments-first model of Revolut.
Today’s agenda below.
FINTECH: The $12B hole in Coinbase and Robinhood’s 1Q Earnings
ANALYSIS: Coinbase and Ramp restructure as AI-Native Financial Companies (link here)
CURATED UPDATES: Paytech, Neobanks, Lending, Digital Investing
To support this writing and access our full archive of newsletters, analyses, and guides to building in Fintech & DeFi, subscribe below (if you haven’t yet). We are planning a blockbuster set of agentic finance analyses, so grab your seat now.
Our Ecosystem: AI Venture Fund | AI Research | Lex Linkedin & Twitter | Sponsors
Digital Investment & Banking Short Takes
The $12B hole in Coinbase and Robinhood’s 1Q Earnings
Crypto is in the depths of a bear market.
Bitcoin is hovering around $80K, down roughly 36% from its October 2025 peak near $126K. Spot volumes across centralized exchanges have collapsed to their lowest level since September 2019, and are down 44% YoY in Q1, according to Coinbase.
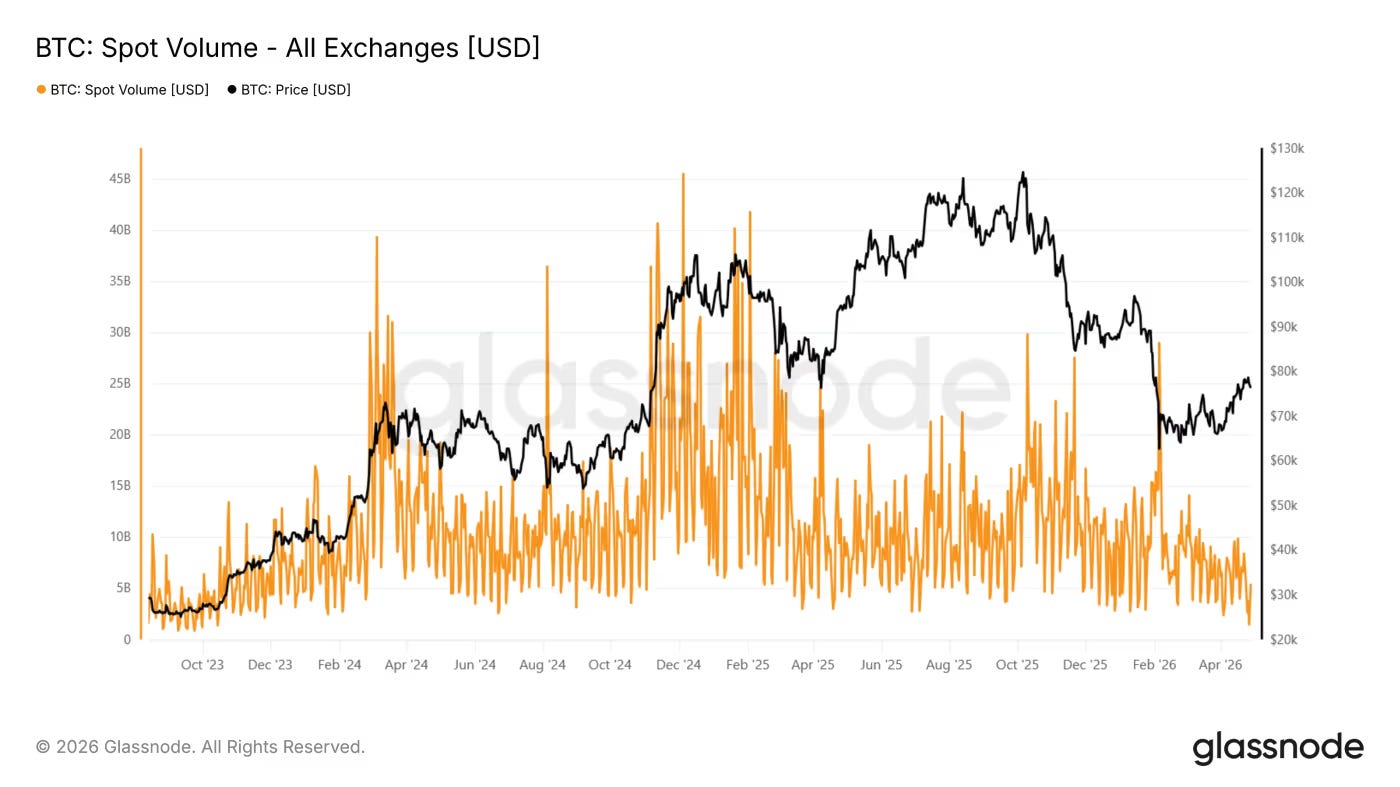
Some on-chain analysts suggest the recent rally off of $60K might not have much steam. It is now the longest bear-market rally of the last two cycles, but it looks more technical than fundamental. A rise in open interest for derivatives (perps) but lower spot activity, indicates that the move higher is being driven by short liquidations and unwinds in speculative positioning rather than durable buying.
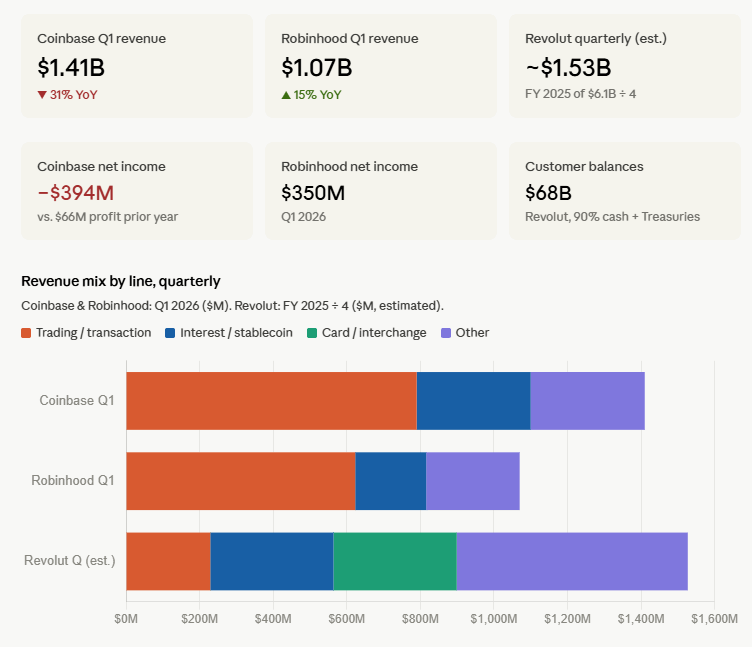
The fall in activity is eating into trading platforms’ revenue. Coinbase saw revenues decline 31% YoY to $1.41B and posted a $394M net loss, compared to a $66M profit a year ago. Management also announced a 700-person layoff (~14% of the workforce) the same week, citing both crypto cyclicality and an “AI-era” cost reset.
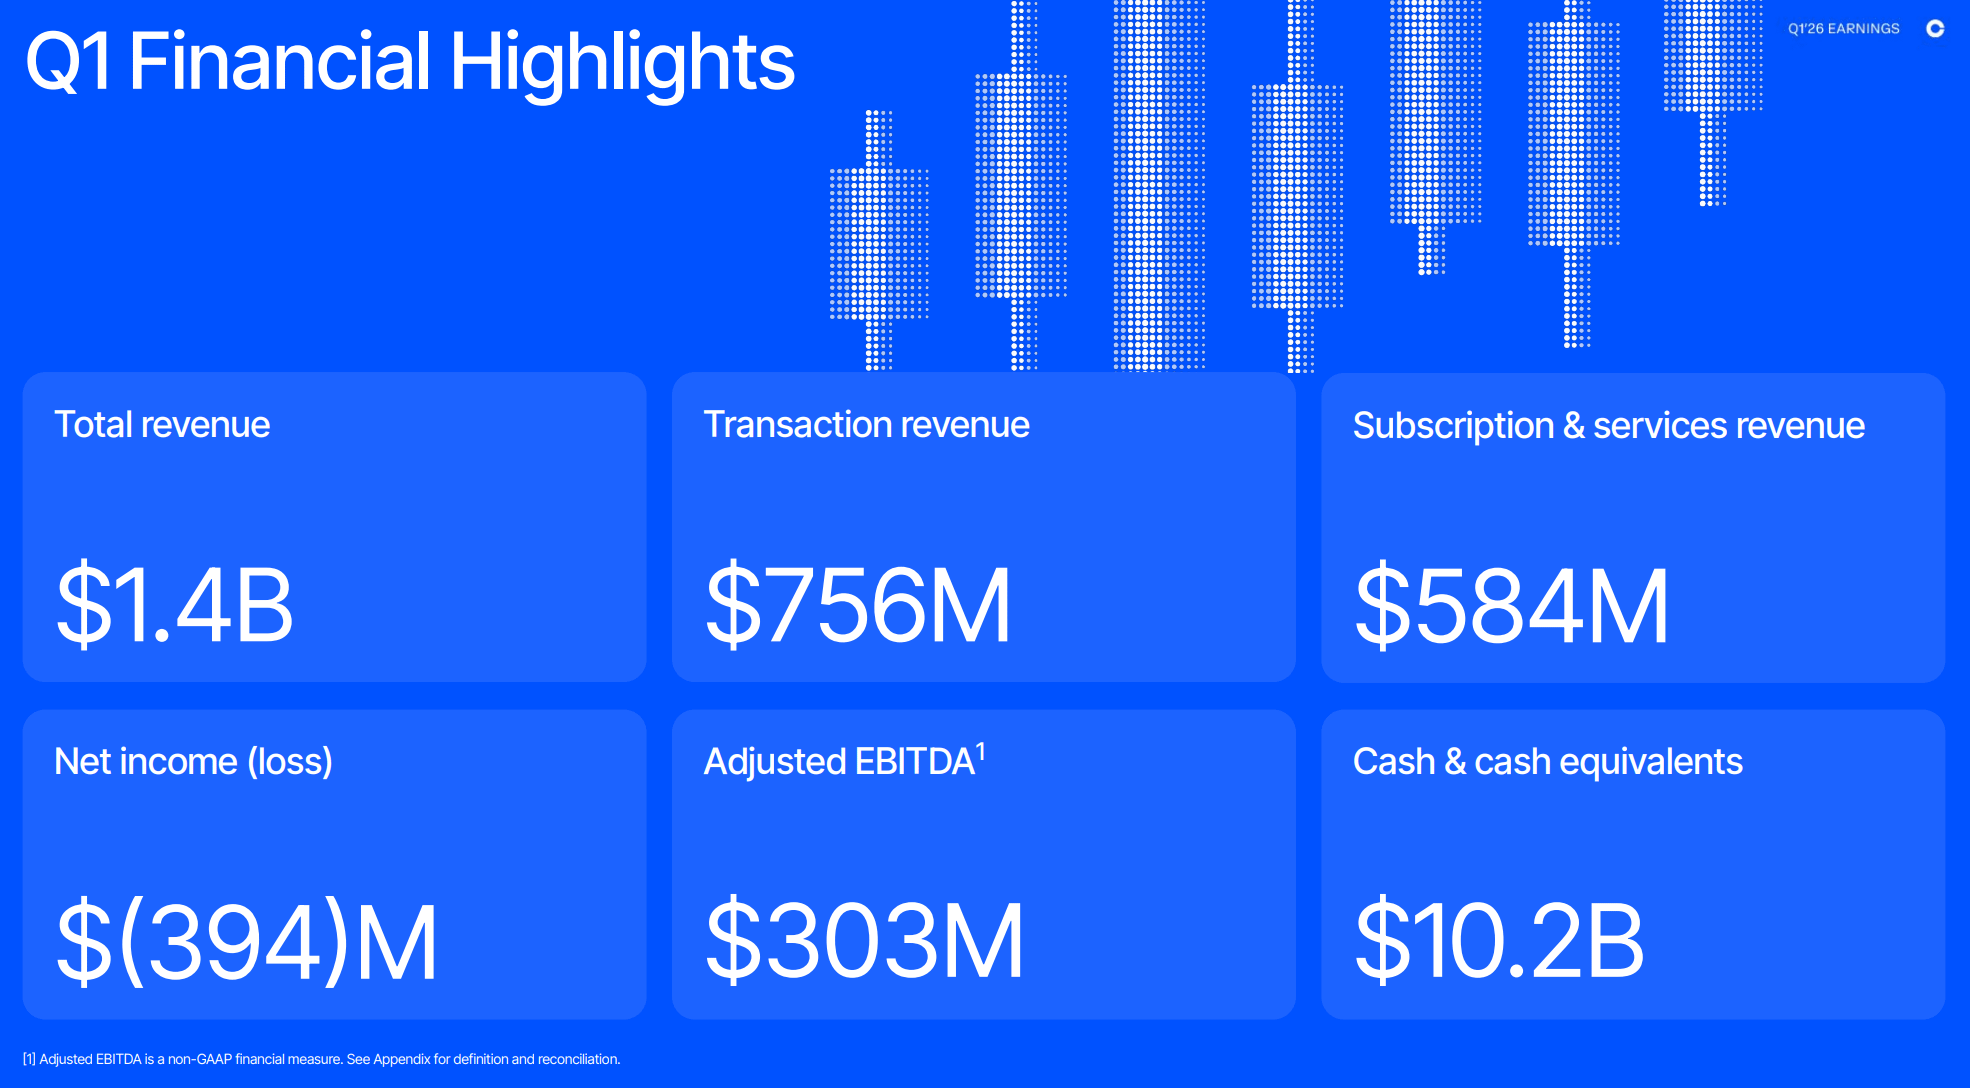
Trading sits at the centre of the decline.
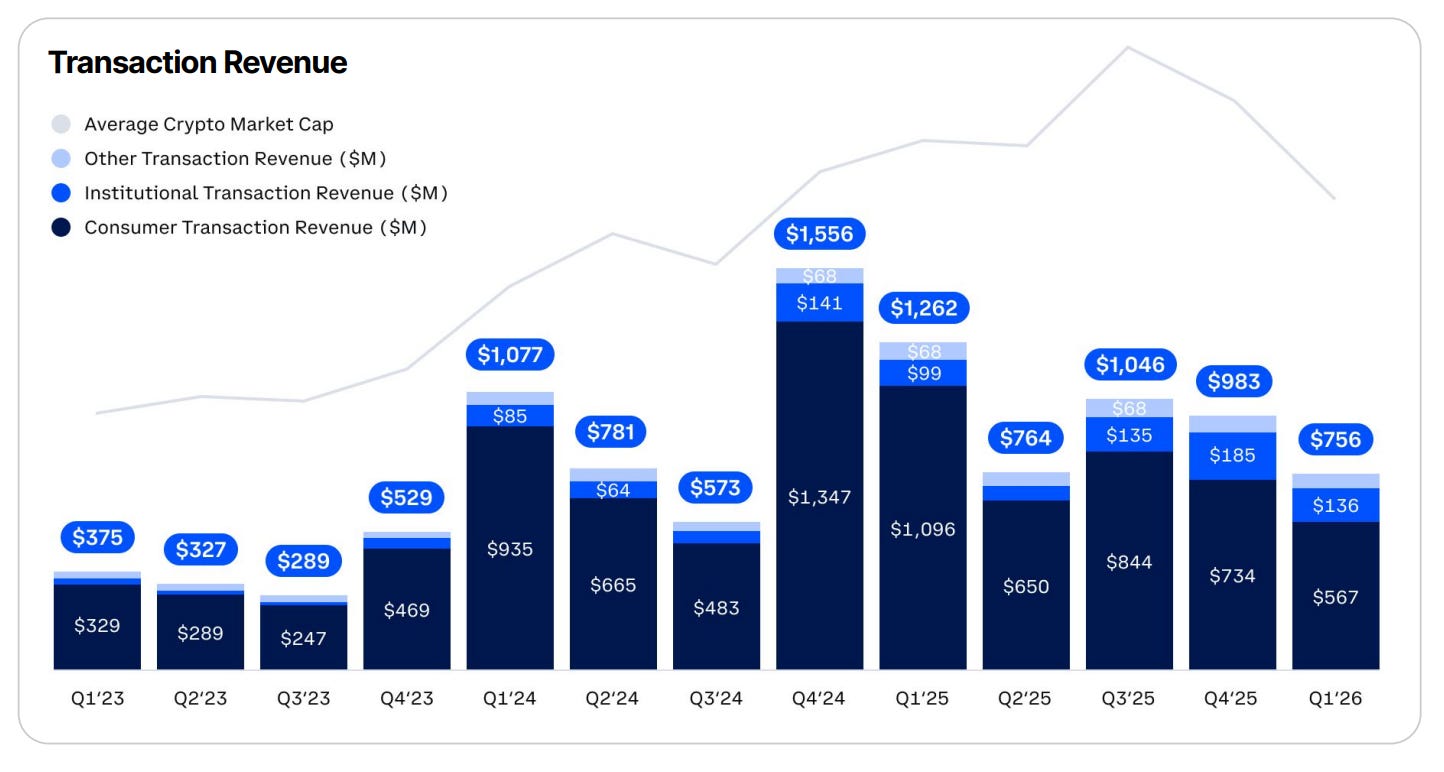
Transaction revenue made up 56% of total revenue in Q1 and fell 40% YoY, with consumer transaction revenue down 48% to $567M. Institutional transaction revenue actually grew in this period, but that increase is almost entirely attributable to the $4.3B Deribit acquisition that closed in August 2025; organic institutional volumes were actually down 48%.
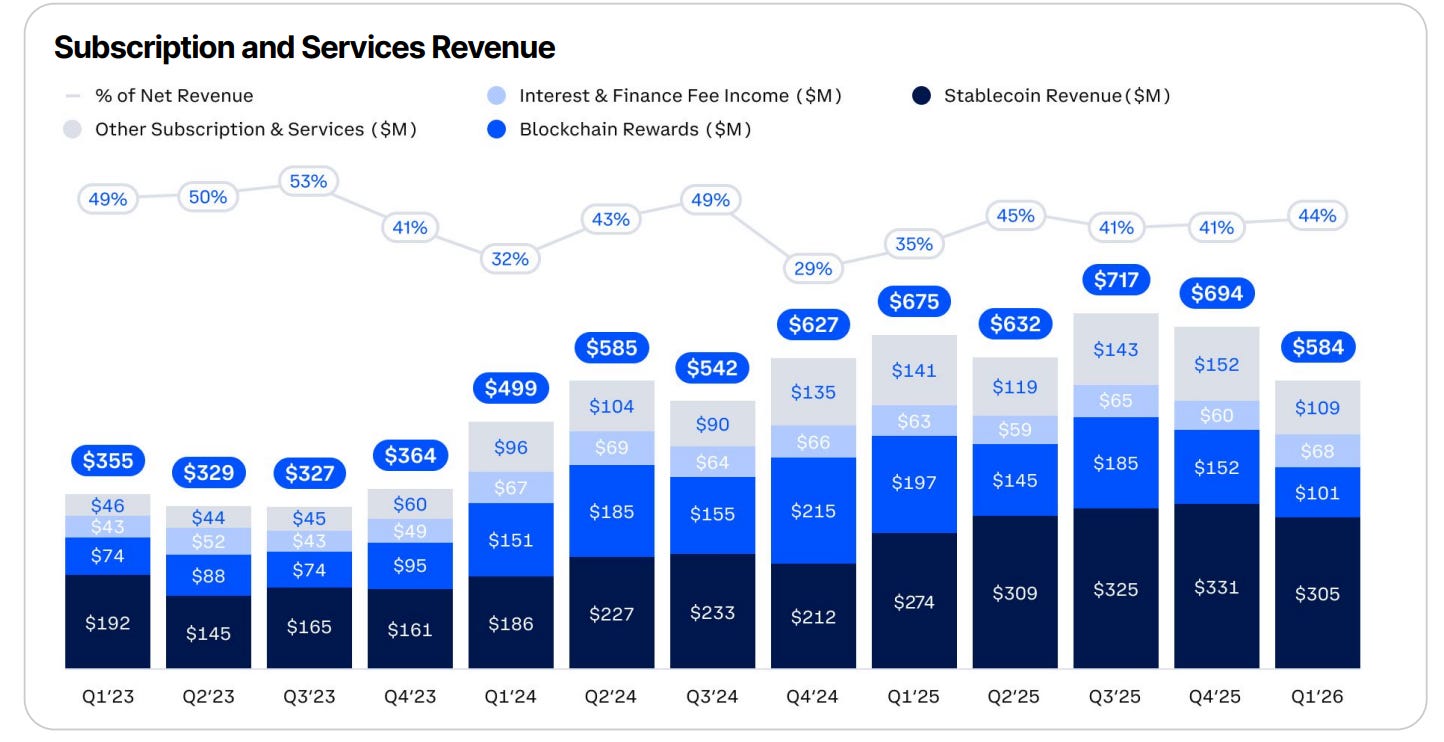
The remainder of revenue comes from subscription and services, which is distributed across stablecoin revenue (interest income earned on customer USDC balances through Coinbase’s partnership with Circle), blockchain rewards, interest and finance fees, and other subscription products like Coinbase One.
This segment now makes up 44% of total revenue, which management frames as a “durable buffer” against trading volatility. But that is slightly misleading. Stablecoin revenue is the single largest line at 22% of net revenue and grew 11% YoY, but it’s also highly correlated to trading volume. Customers move into USDC when they want to sit out volatility or rotate between assets, but will redeploy back into volatile assets as soon as markets turn. This dynamic is partly why subscription and services as a % of total revenue look quite flat over the past 3 years.
Meanwhile, Robinhood posted stronger numbers.
Revenue grew 15% YoY to $1.07B and net income of $350M, but still missed analyst revenue expectations. Like Coinbase, the miss was driven by crypto, where related transaction revenue dropped 47% YoY to $134M. Strikingly, it was the only major income line that fell year-on-year.
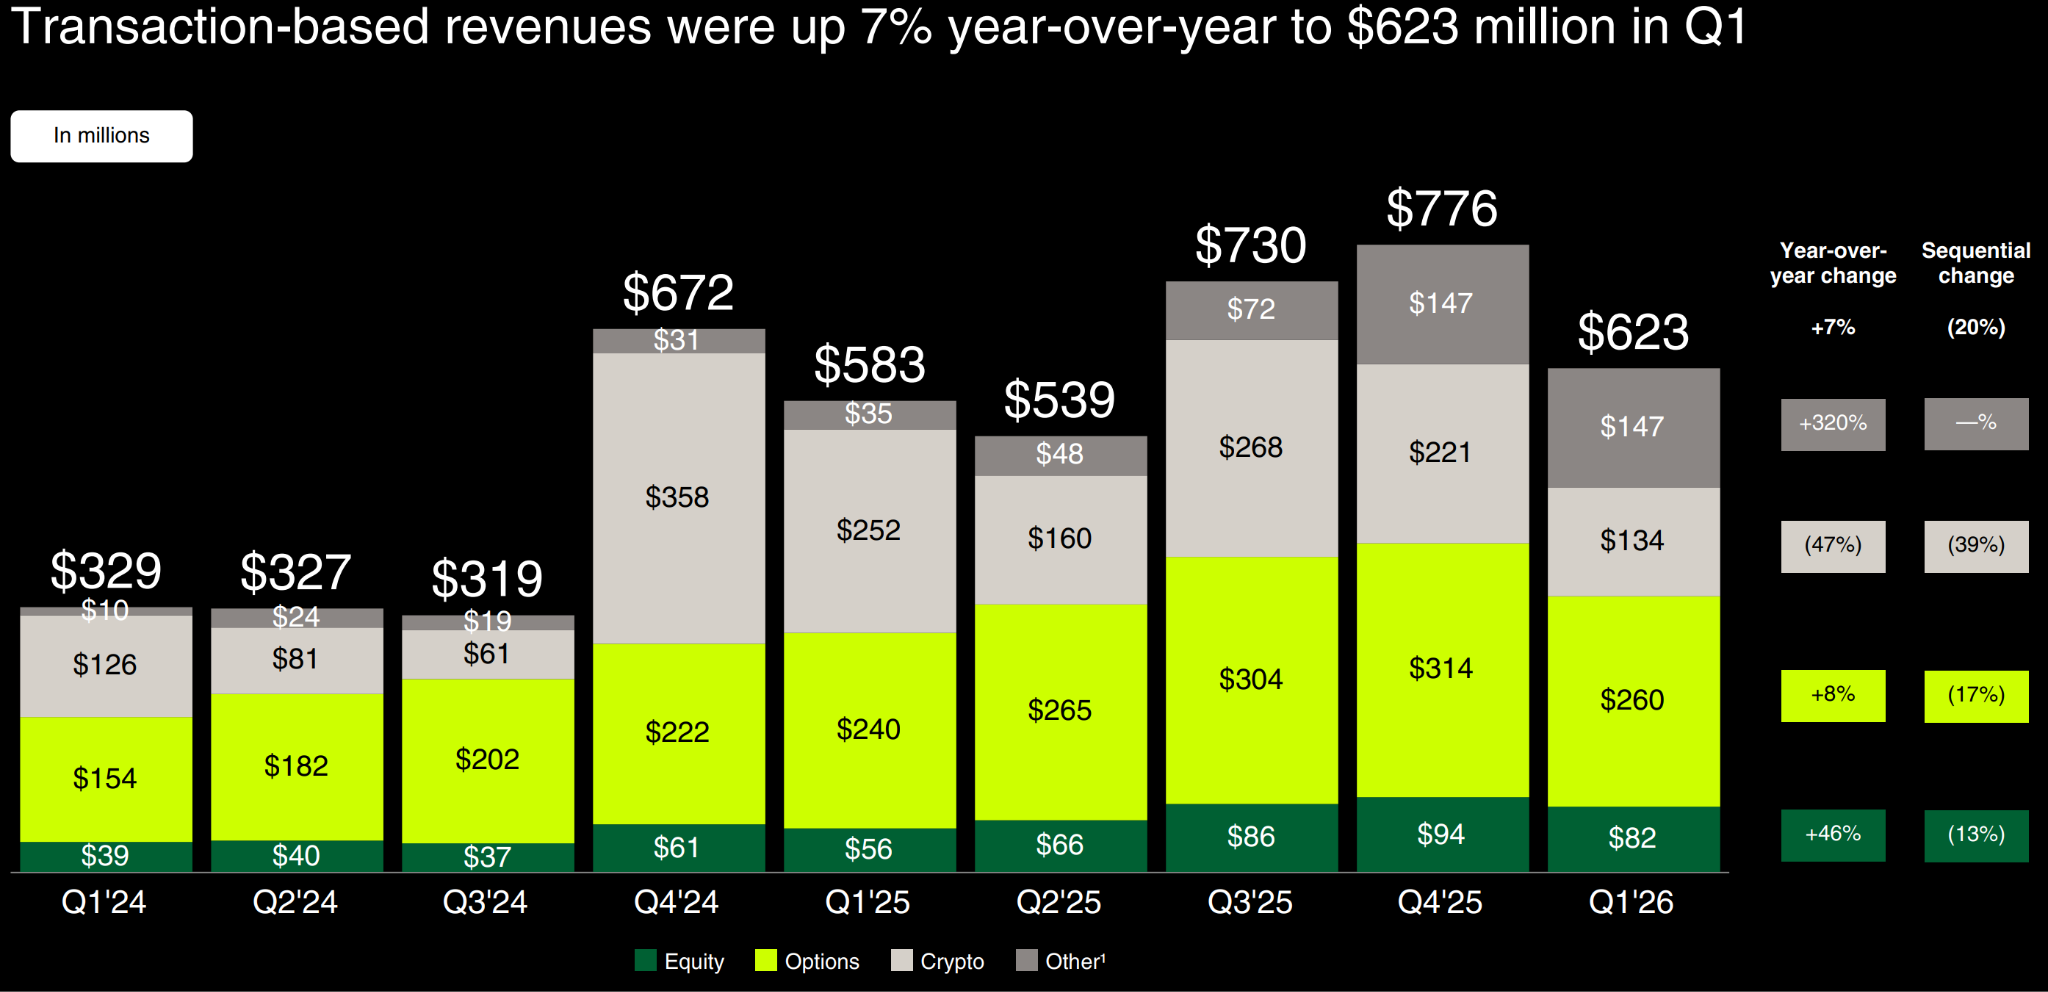
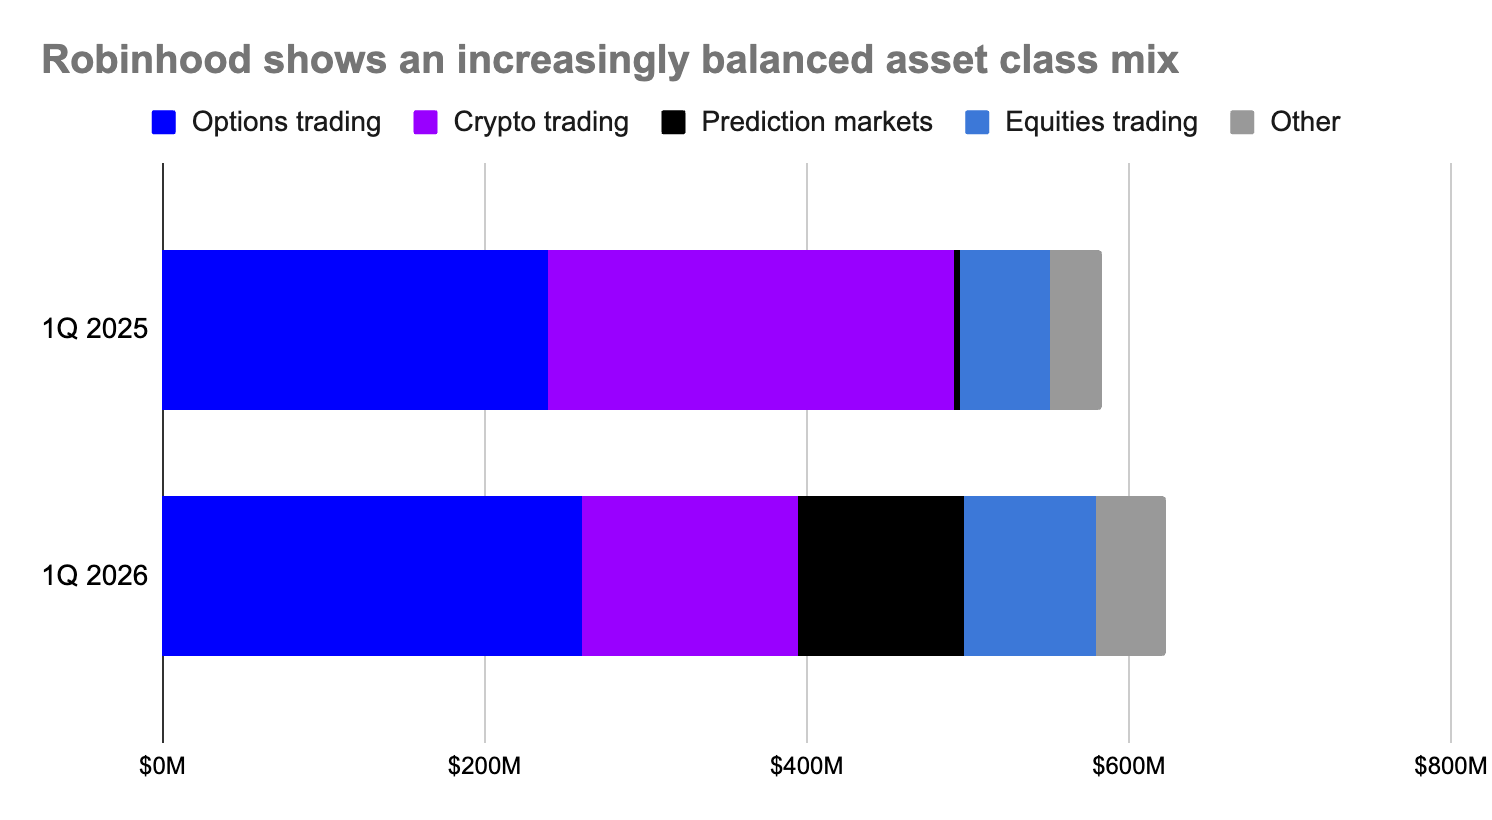
Trading still makes up 58% of Robinhood’s revenue, broadly unchanged from a year ago. But the company has held up better throughout the bear markets due to diversity in the asset classes being traded. Total transaction revenue grew 7% YoY to $623M, driven by a 320% surge in prediction market revenue through Robinhood’s partnership with Kalshi, a 46% jump in equities revenue, and 8% growth in options.
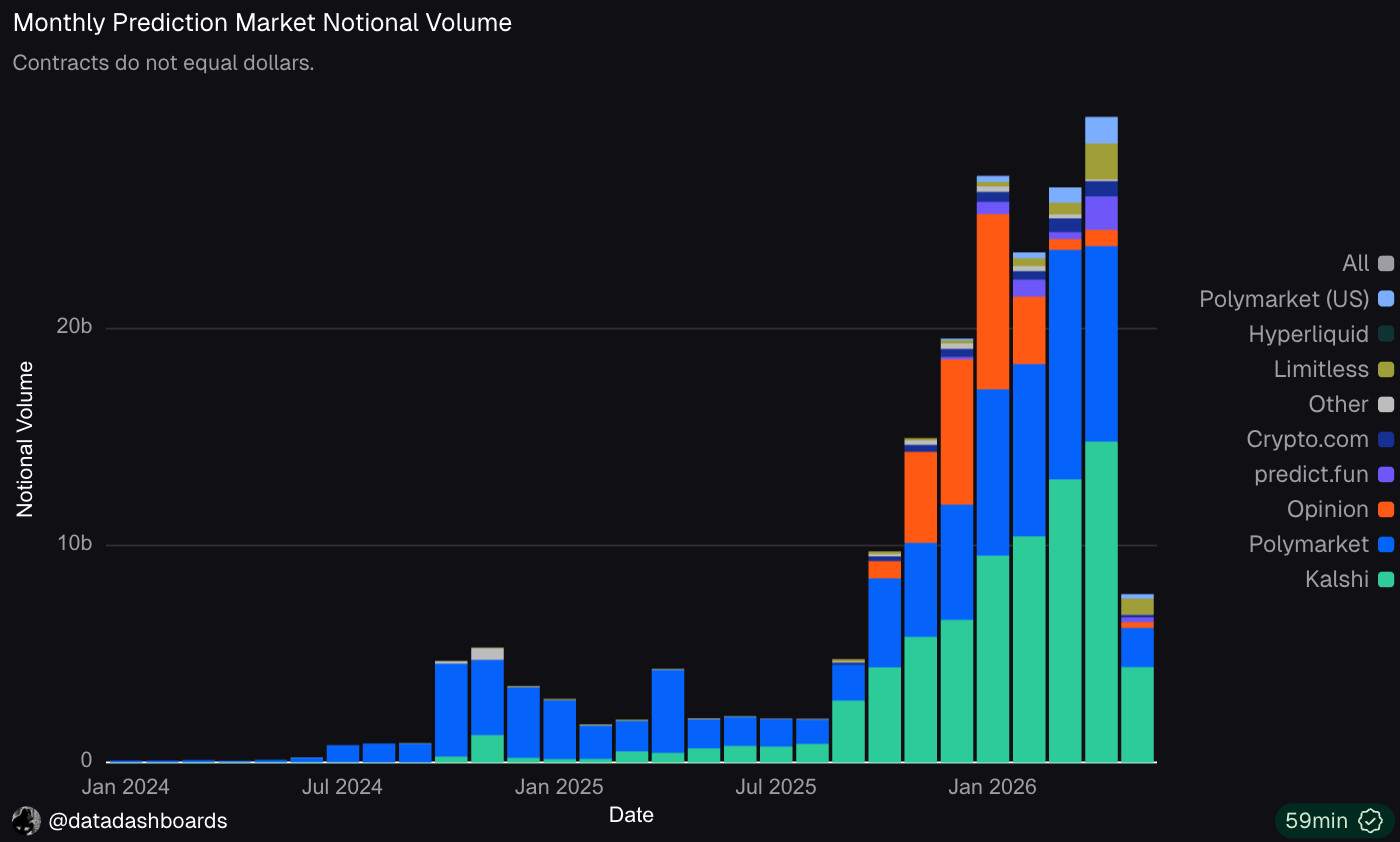
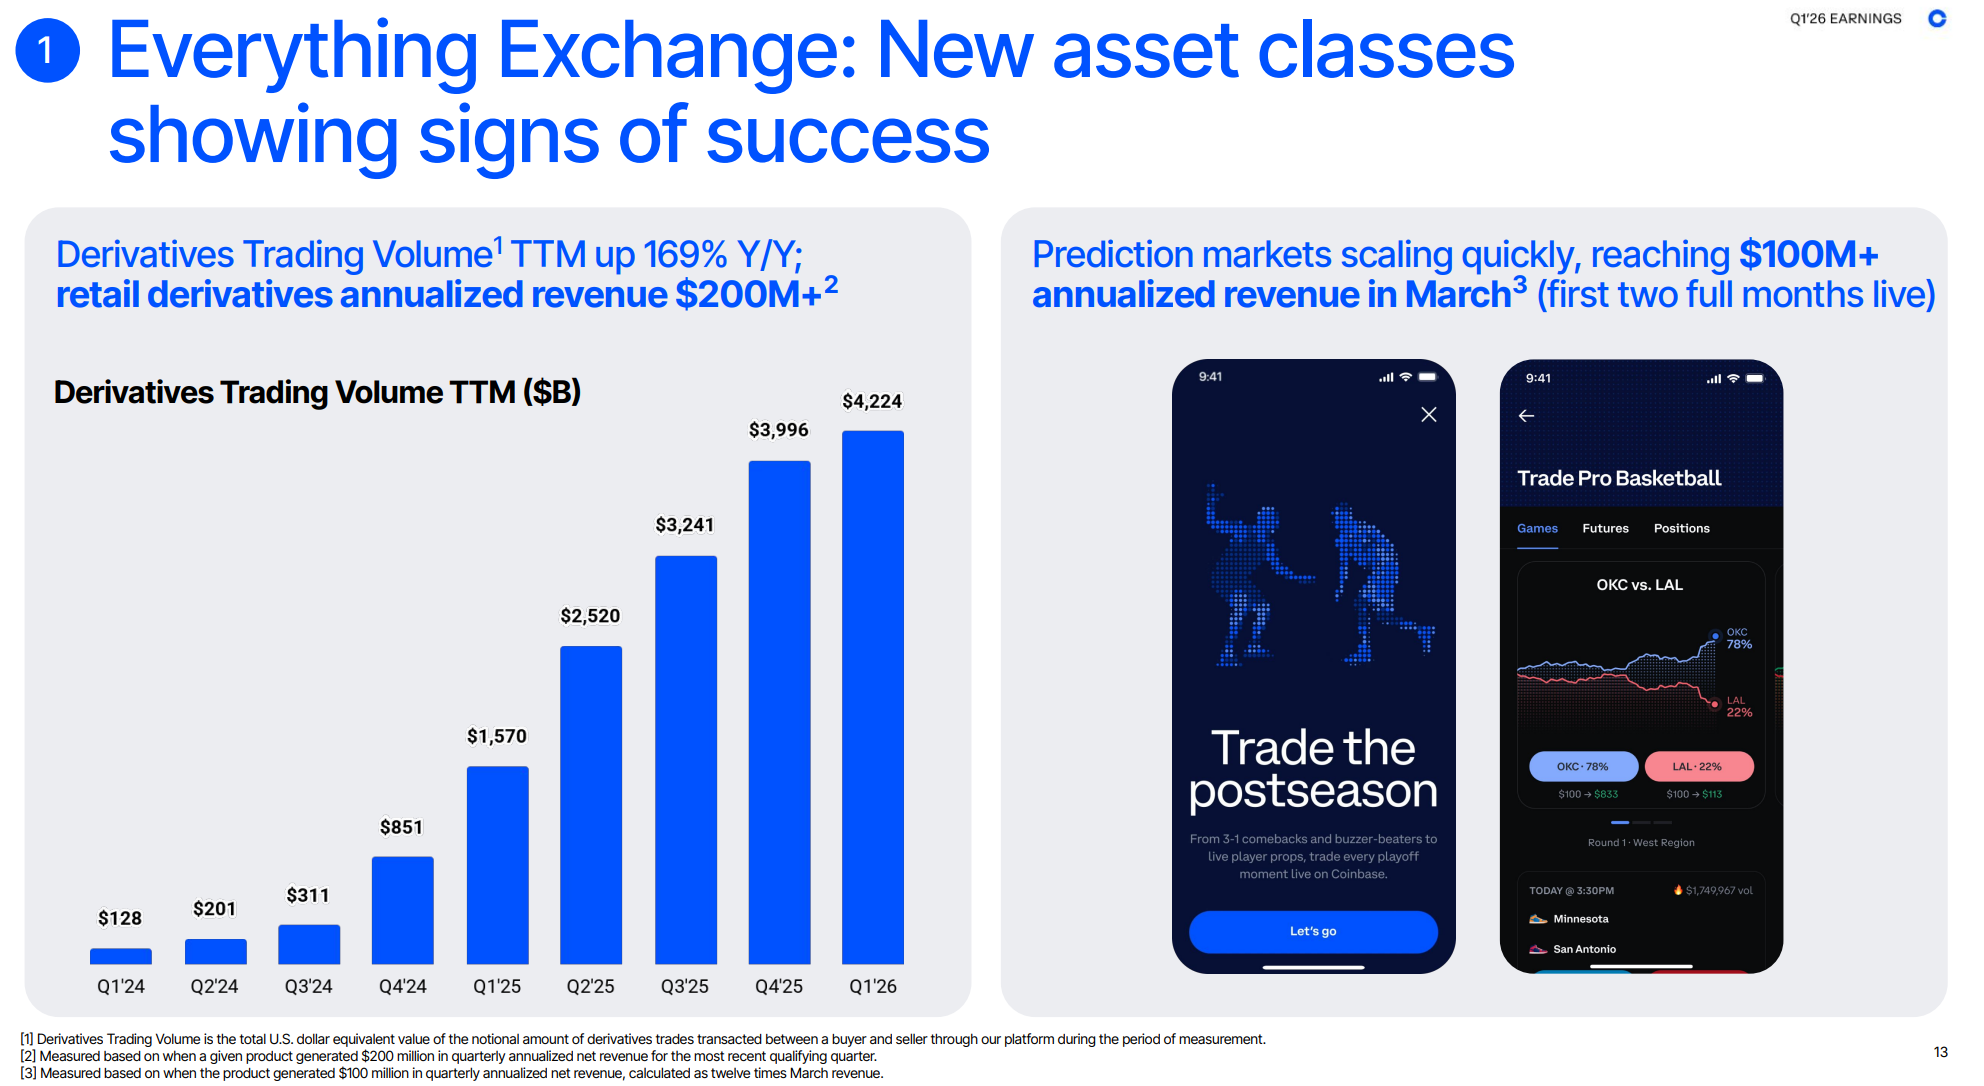
Derivatives like prediction markets and perpetual futures (perps) are proving more resilient in the downturn. Kalshi raised $1B last week at a $22B valuation, doubling its valuation and tripling annualized trading volume to $178B within just 6 months.
Event-driven trading, like predictions are often focused on sports, elections, and economic data, so are less sensitive to broader markets. But growth has also stemmed from institutions beginning to use them as hedging tools when markets get choppy. There is an organic adoption tailwind that is hiding the cyclicality.
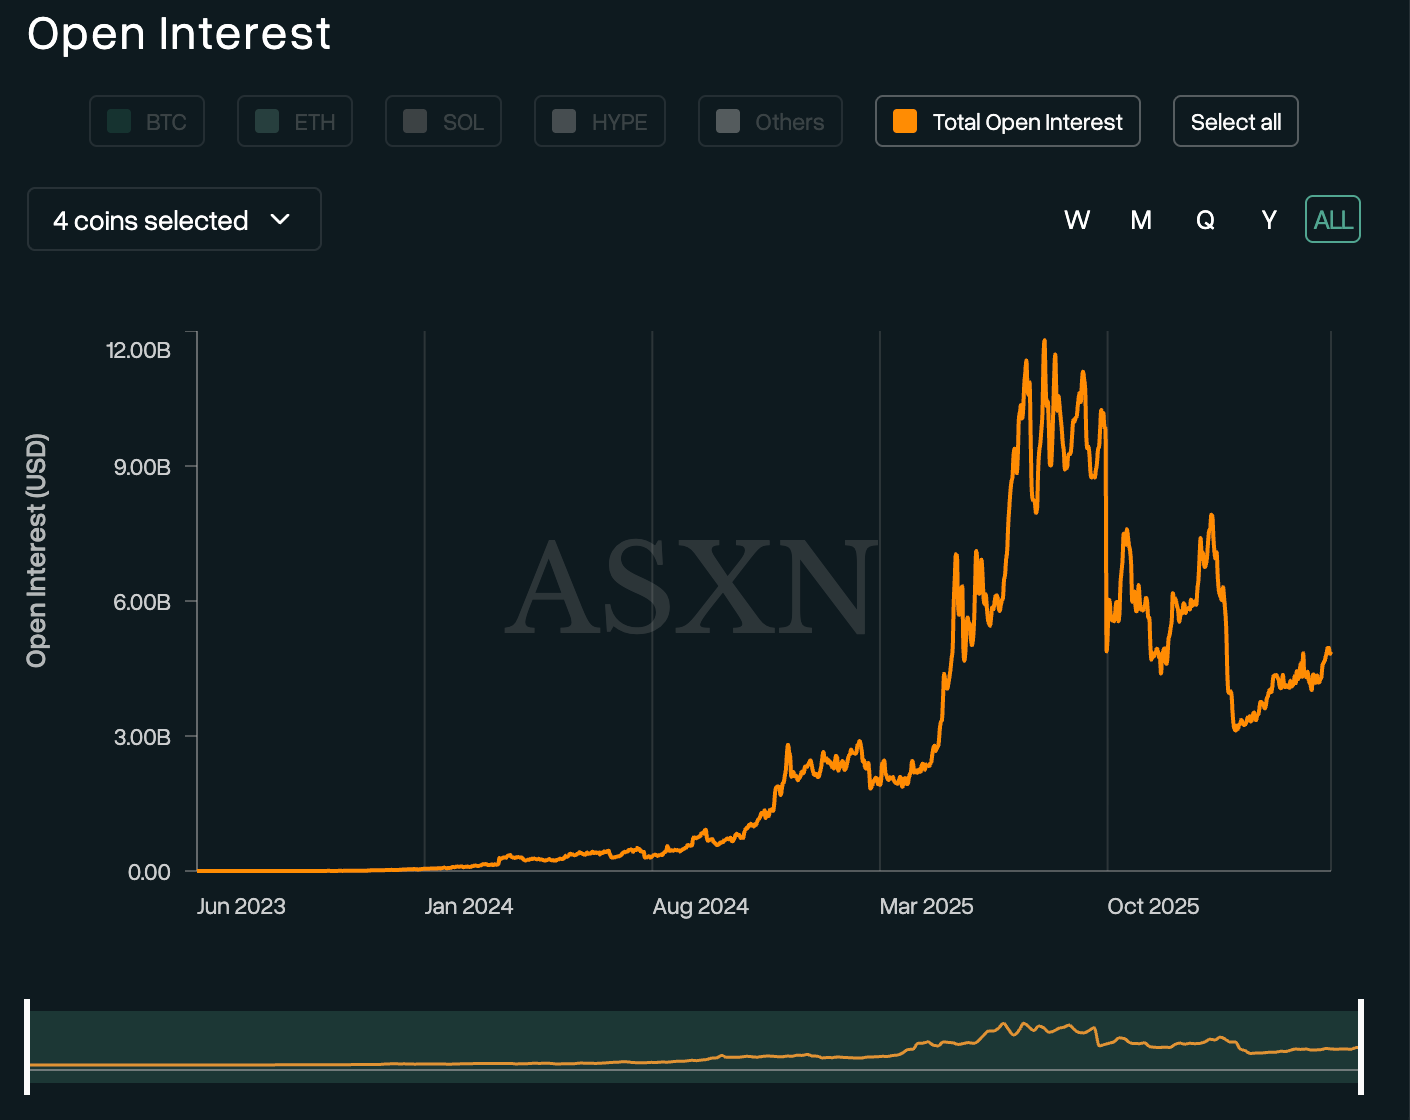
Perps have shown a similar pattern. The total value of open leveraged bets from traders on Hyperliquid, measured as “Open Interest”, was $4.3B by end of April, up +9% in the past two months despite the broader spot market collapse. This metric still dropped from the October peak alongside the rest of crypto, but it’s held up materially better.
This makes a difference for trading platforms that have these features.
Prediction markets now make up 17% of total transaction revenue for Robinhood!
And while it doesn’t offer perps directly, it offers similar margin trading on equities and crypto, on which it earns interest. In Q1 2026, margin interest revenue grew 75% YoY to $193M, making up 18% of total revenue.
Coinbase has been late to this shift. While it launched both prediction markets and perps for retail customers in January 2026, it didn’t materially impact its PnL yet. As a result, the exchange has been left more exposed to spot trading.
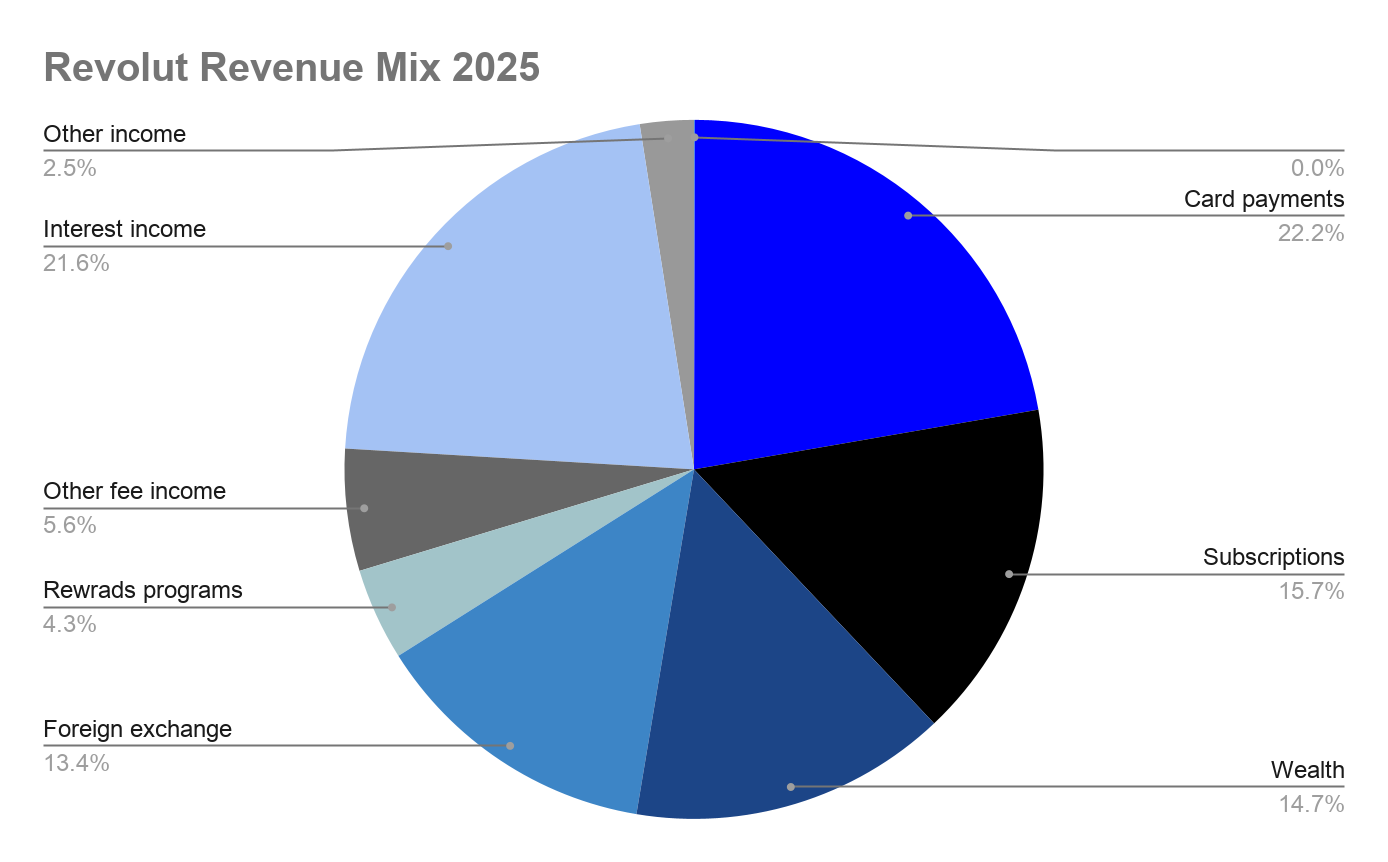
Financial platforms like Revolut, which have major trading activity but center on payments and banking, are much less affected. Revenue grew a whopping +45% in 2025 to $6.1B and is evenly balanced across major revenue streams, each making up between 13-22% of total.
Card interchange fees and interest income are the largest at ~$1.3B each. Crypto trading is wrapped under the Wealth segment together with equities and CFDs, which amounted to 15% of total revenue, a fraction of Robinhood’s exposure and a sliver of Coinbase’s.
It’s also worth noting that Revolut’s interest income is similar to Coinbase’s stablecoin revenue, with both monetizing idle customer balances. Revolut held 90% of its $68B customer balances in cash and Treasury investments at year-end. But the behaviour driving those balances is fundamentally different. Revolut’s deposits grew with growth in primary banking relationships and direct deposits (up 45% YoY) while Coinbase’s USDC balances grew with reduced trading appetite. If crypto markets turn more bullish, Coinbase is more likely to see a fall in balances.
The challenge for trading-first platforms like Coinbase and Robinhood is whether they can meaningfully expand into adjacent financial products while staying tied to market cycles. Robinhood has shown that diversity in tradable asset classes, especially prediction markets and derivatives, can act as a hedge.
Coinbase is moving in a similar direction. The risk is a prolonged bear market hindering their ability to grow while fintech competitors like Revolut, Nubank, and Cash App grow their share of customer deposits.
👑 Related Coverage 👑


Long Take: Coinbase and Ramp restructure as AI-Native Financial Companies
We examine how AI is transforming the org chart itself, shifting companies from Amazon-style two-pizza teams toward “AI-native” pods of 3–5 people with dramatically higher productivity.
We compare Klarna’s failed AI substitution strategy, which cut headcount from 5,500 to 3,400 before quality issues forced rehiring, with Coinbase and Ramp, which are reorganizing around AI augmentation and orchestration instead. Coinbase cut 700 employees while moving toward one-person product teams and AI-generated code, while Ramp built an internal AI harness used daily by 99.5% of employees across 350+ workflow skills.
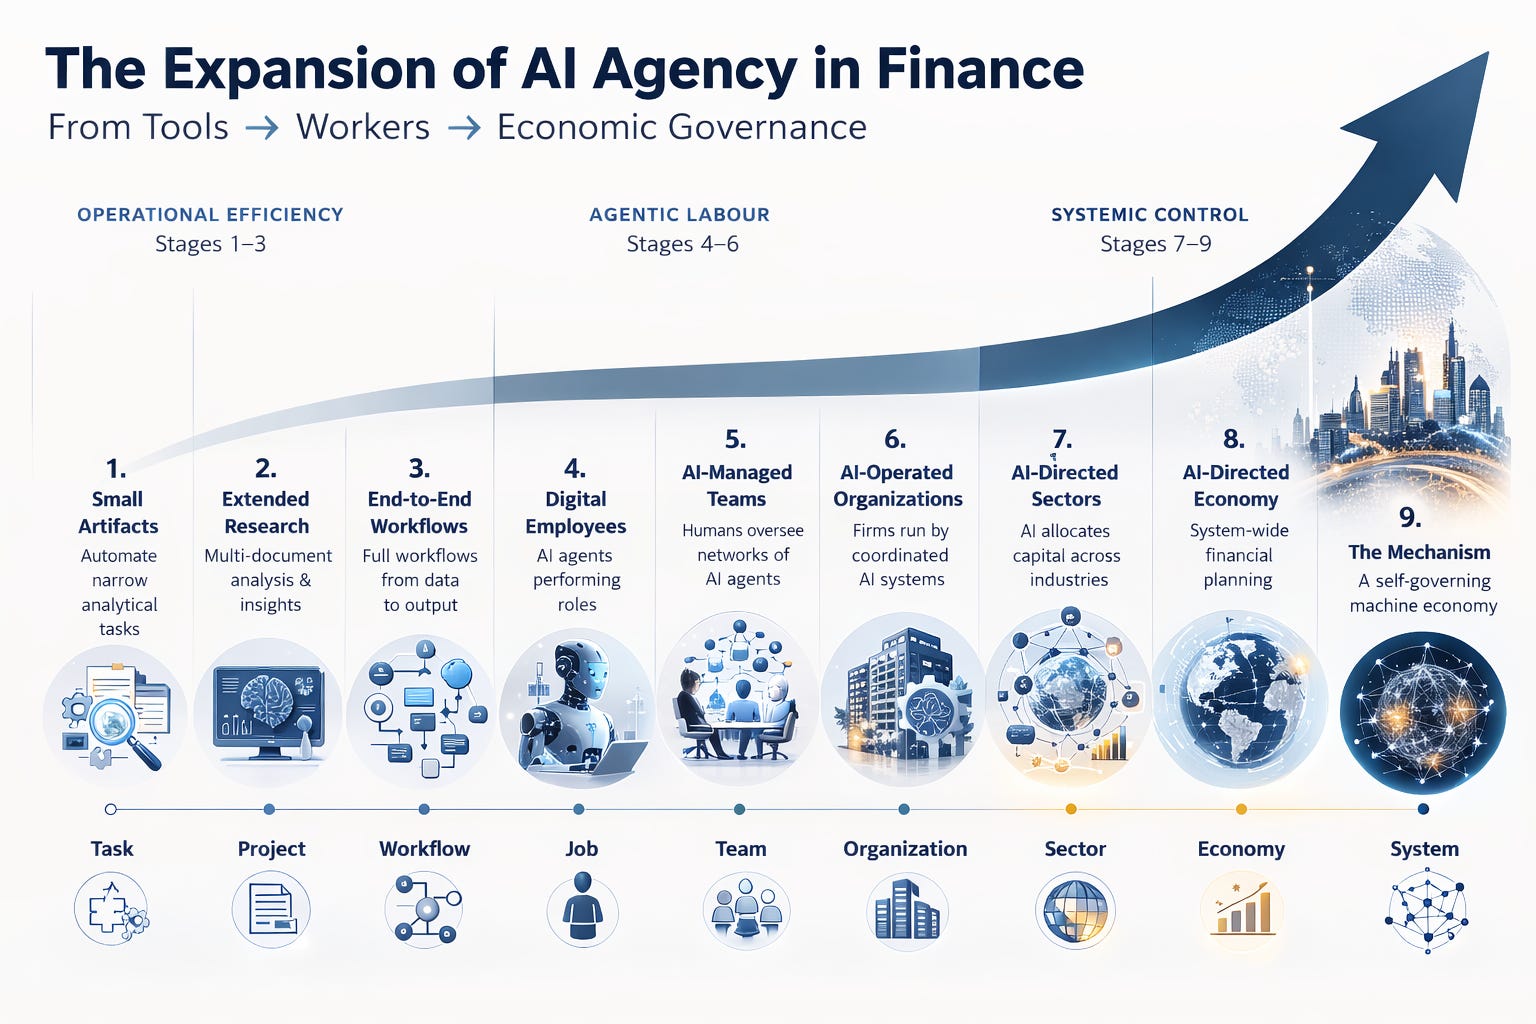
We also explore how firms like Box and Plaid are being repriced as AI infrastructure companies because they control permissioned enterprise data that agents need to operate.
Curated Updates
Here are the rest of the updates hitting our radar.
Paytech
Ramp acquires Swedish payments platform Billhop - FinTech Futures
Neobanks
Mercury Wins Conditional OCC Approval For Banking License - Fintech Futures
Chime moves further up market with prime offering - American Banker
Lending
SoFi Reports Record Net Revenue of $1.1 Billion - BusinessWire
Revolut’s AI Credit model PRAGMA - Finextra
Commerzbank to axe 3000 jobs as it fends off UniCredit takeover - Finextra
Digital Investing
⭐ US sues Wisconsin in legal battle over prediction markets - Reuters
Kalshi to offer perpetual futures trading - Coindesk
KelpDAO/LayerZero Exploit Drains $290m, Freezes DeFi Markets - Galaxy
🚀 Level Up
Join our Premium community and receive all the Fintech and Web3 intelligence you need to level up your career. Get access to Long Takes, archives, and special reports.
Sponsor the Fintech Blueprint and reach over 200,000 professionals.
👉 Reach out here.Check out our AI newsletter, the Future Blueprint, 👉 here.
Read our Disclaimer here — this newsletter does not provide investment advice