
Hi Fintech Architects,
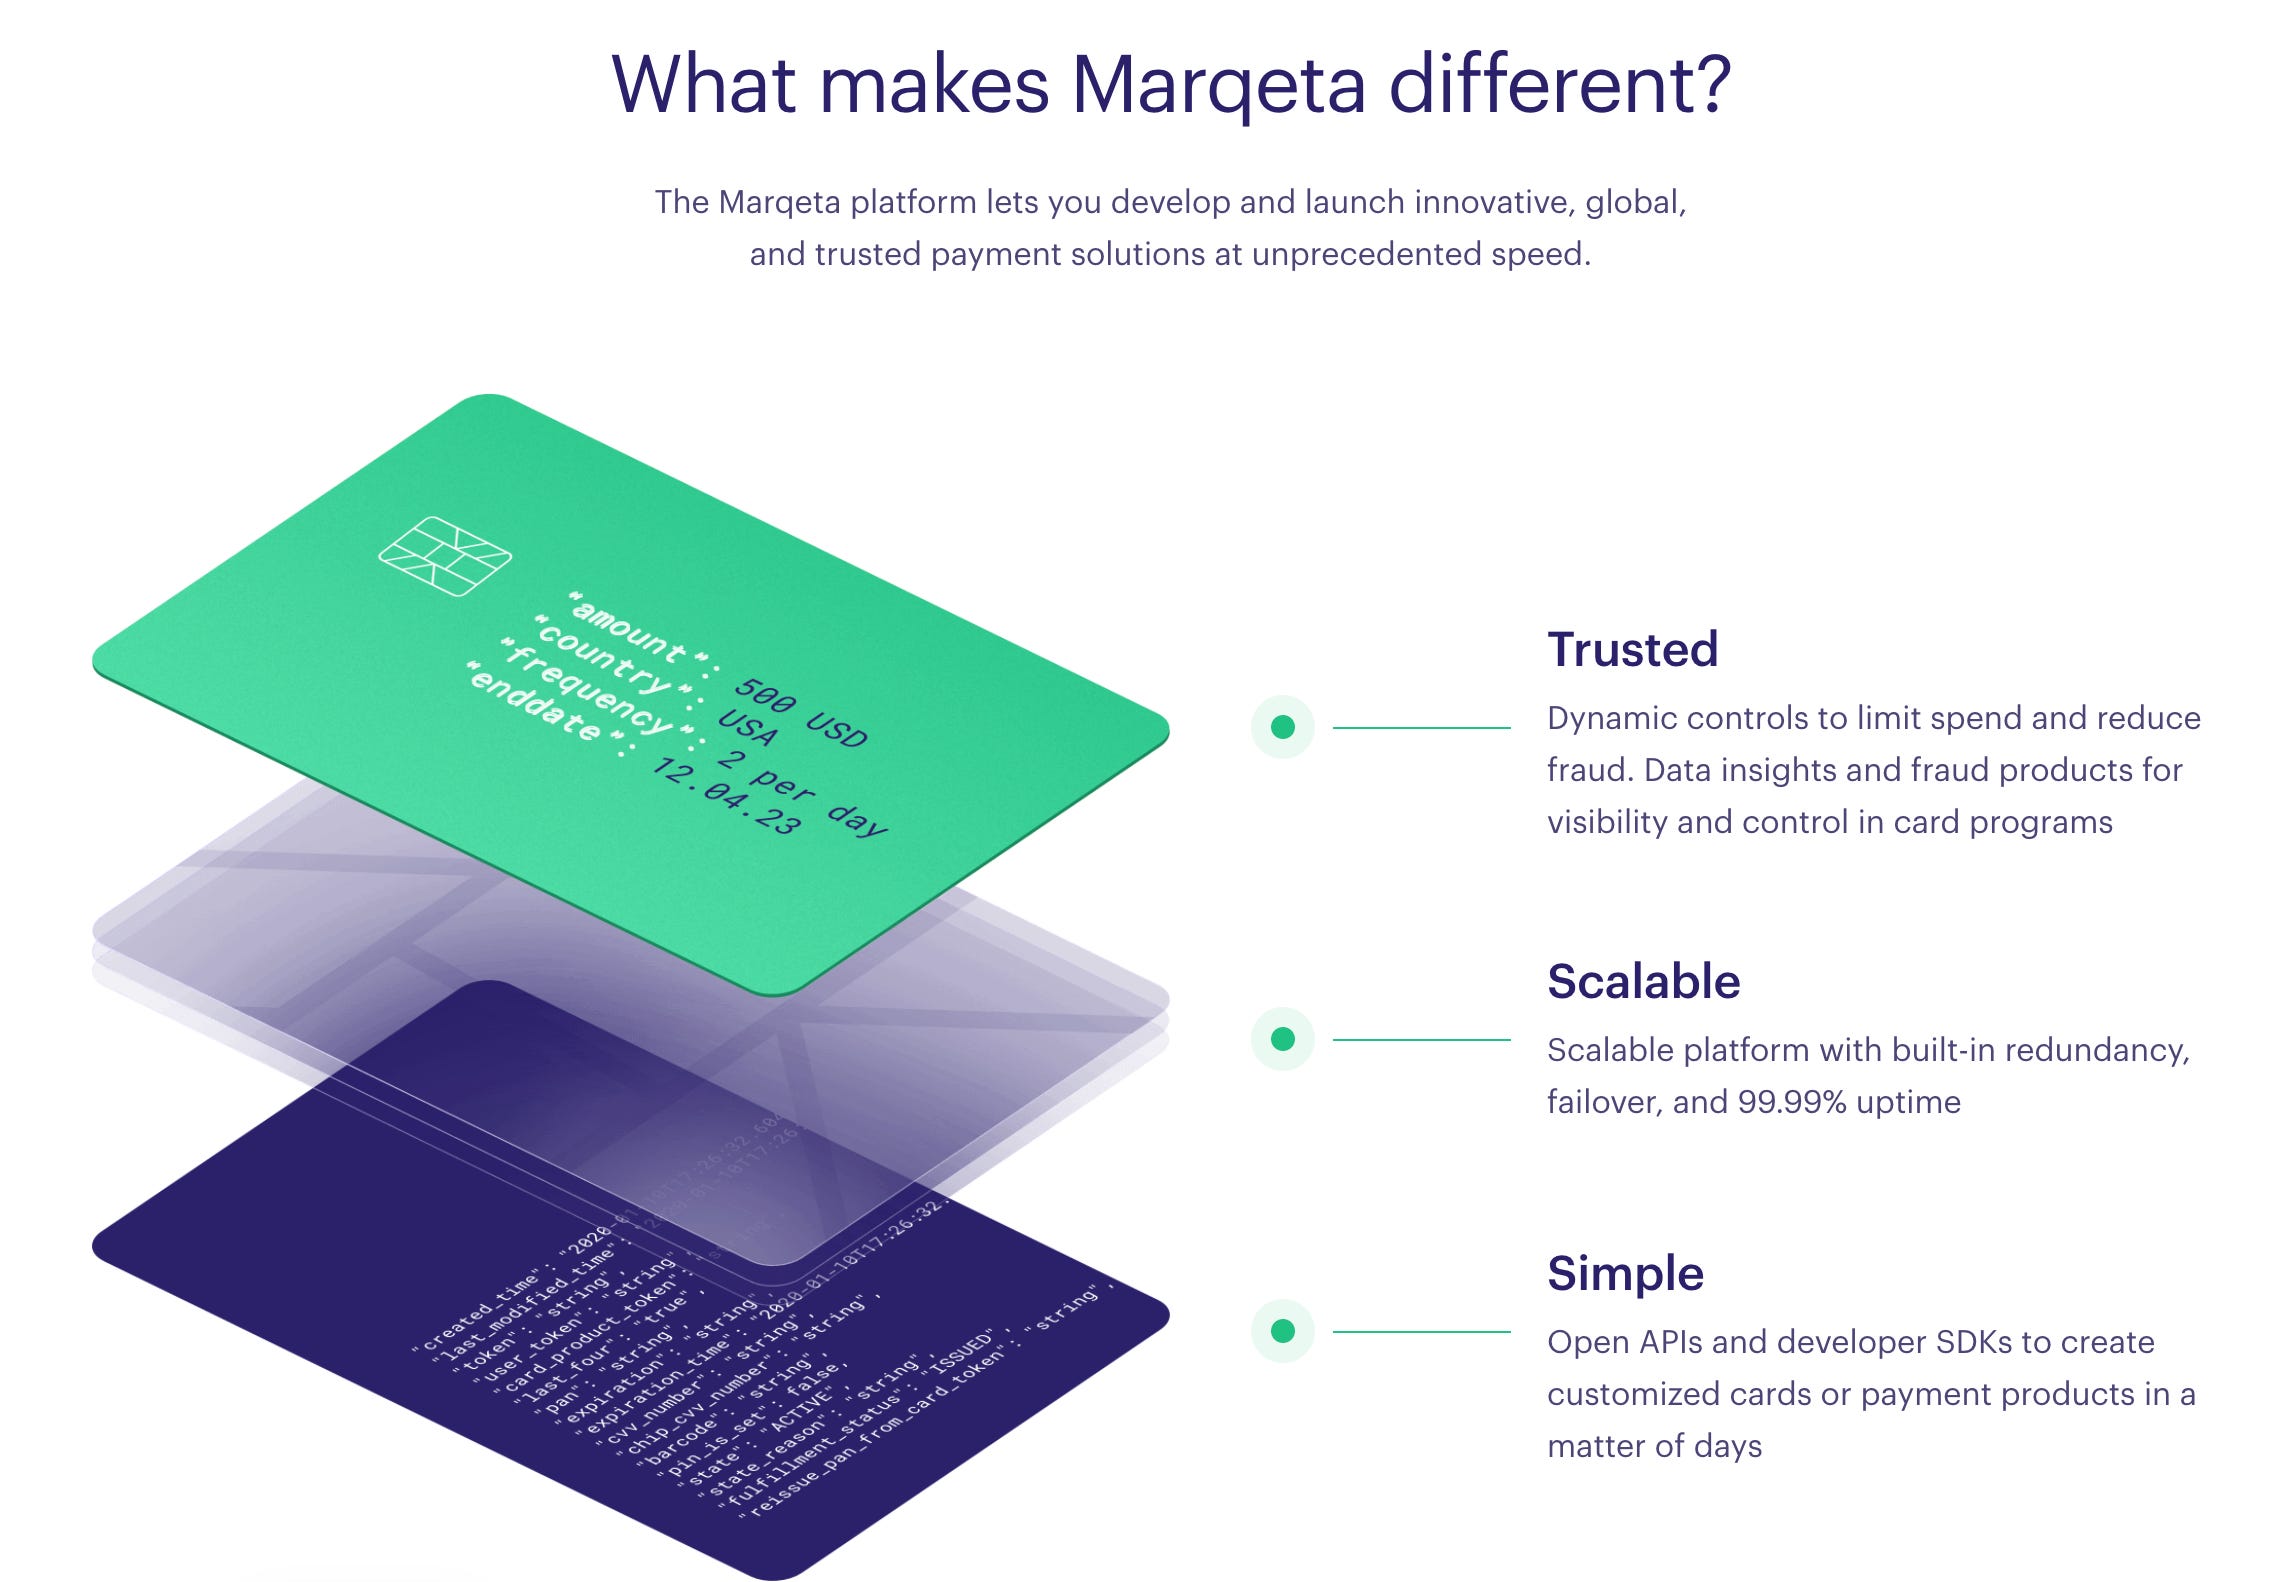
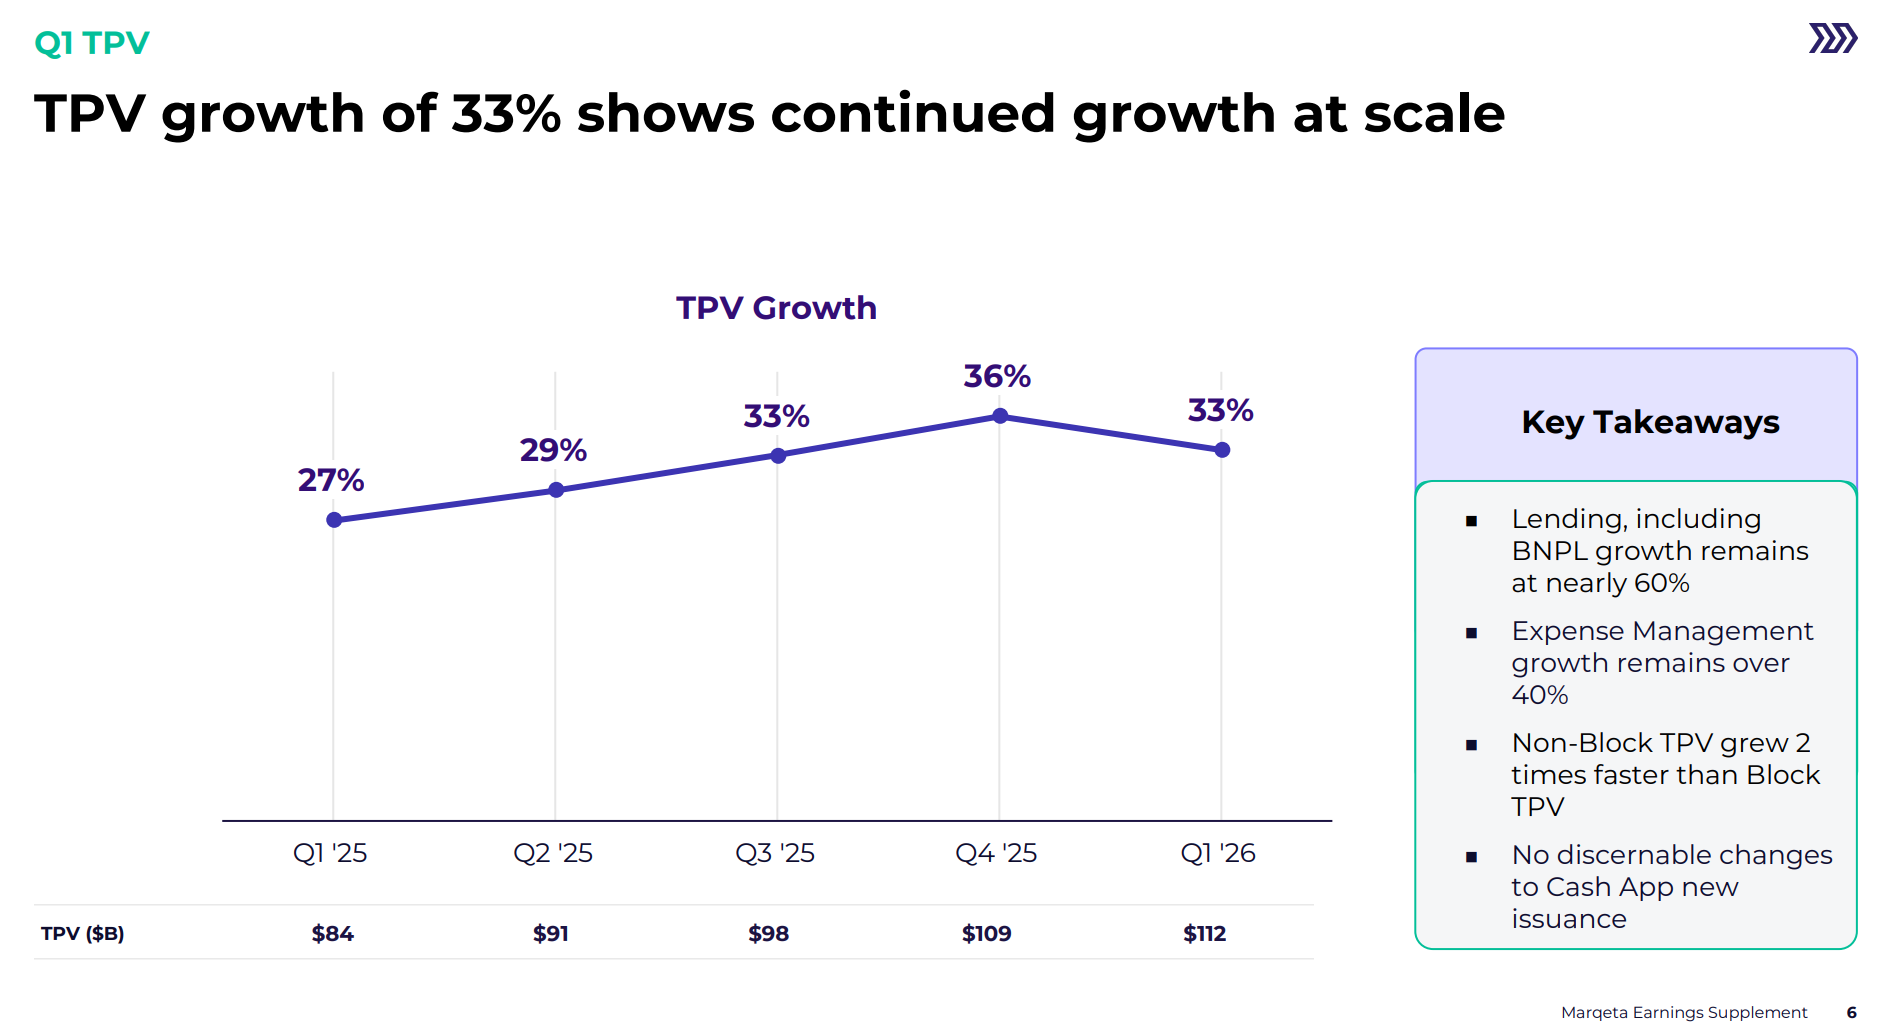
In this episode, Lex chats with Mike Milotich — Chief Executive Officer of Marqeta, the modern card issuing platform that processed nearly $400 billion in payments volume in 2025, and is certified to operate in 40+ countries, growing over 30% for the third straight year. They discuss how Marqeta's separation of bank, processor, and brand armed fintech's largest winners across buy now pay later, on-demand delivery, neo-banking, and expense management with the Lego blocks to build their own card programs. Mike explains how the company's growth is shifting from enabling new use cases to displacing volume on legacy bank platforms, and they explore why card issuing is going multinational, what the agentic commerce wave actually requires to clear security and behavioural hurdles, and how Marqeta's continued growth runs through embedded finance, real-time personalisation, and the forced modernisation of the banks themselves.

For those that want to subscribe to the podcast in your app of choice, you can now find us at Apple, Spotify, or on RSS. Or to support this writing and access our full archive of IPO primers, financial analyses, and guides to building in the Fintech & DeFi industries, see subscription options here. Our current price point is only $2/week.
Thanks for your time and attention,
Matt & Lex 🙌
Key notable takeaways:
The BNPL business model is flipping from merchant rails to consumer cards. Marqeta originally solved the merchant scale problem for buy now pay later via virtual cards, removing the need for tens of millions of merchants to integrate a new button at checkout. The current shift is more important: BNPL players are now issuing consumers their own physical and virtual cards usable anywhere cards are accepted, turning BNPL from a merchant-acceptance game into a direct consumer value proposition. BNPL volume has grown over 50% year-on-year for Marqeta in recent quarters.
Card issuing is going multinational, and that breaks the legacy bank model. Banks have always been local on the consumer side, with only a handful multinational on the commercial treasury side. The next generation of card issuers, neo-banks like Revolut and Nubank, plus large global platforms embedding financial products into existing user bases, are global by default. A single platform that issues cards, and is certified to operate across 40+ countries, becomes the strategic moat, and legacy processors built to serve domestic bank programs aren’t structured to compete.
The growth story is moving from expanding the pie to displacing the incumbents. To date, Marqeta has mostly powered new card use cases that didn’t exist before — on-demand delivery, BNPL, neo-banking, expense management. Mike’s forward thesis is a phase change: pressure from fintech winners is forcing banks to modernise, and the next leg of growth comes from displacing volume sitting on legacy bank-controlled platforms. Real-time personalised rewards, where the same card delivers different offers to different cardholders based on live data, is the wedge that legacy infrastructure can’t deliver.
Background
Mike Milotich is a payments veteran with more than two decades of experience in financial services, drawn to the industry by its quantitative, data-driven core. He began in business analysis roles at American Express and PayPal, supporting new product launches, portfolio strategy, partner pricing, and cost optimisation. In 2011 he joined Visa just as the company was standing up its mobile payments division at the dawn of the smartphone era, and spent a decade there across multiple finance leadership roles, ultimately serving as Senior Vice President of Corporate Finance and Investor Relations, where he managed the corporate outlook, evaluated M&A opportunities, and led engagement with the global investor community. Mike holds a bachelor's degree from UC Santa Barbara and an MBA from New York University. He joined Marqeta as CFO in February 2022, stepped into the interim CEO seat in February 2025, and was appointed permanent CEO in September 2025.
👑Related coverage👑


Topics:
Marqeta, Visa, Mastercard, American Express, PayPal, Payments, card issuing, embedded finance, fintech, BNPL, neobank, agentic commerce, e-commerce, crypto, stablecoins, programmable money, machine economy, agentic AI
Timestamps
1’04: From Math Brain to Payments Career : Finding the Nuance in How Money Actually Moves
7’05: The Narrative Gets Ahead of Reality : Why Agentic Commerce Will Move Slower Than the Technologists Think
10’08: Global But Local : The Balancing Act That Kept Visa on Top of the Payments Network for Decades
12’58: Carve It Out or Watch It Get Trampled : How Visa Incubates Mobile, Crypto and Agentic Without Killing Them
15’03: $400 Billion in Volume, 30% Growth, Three Years Running : The Numbers Behind Marqeta's Compounding Scale
17’05: The Pandemic Poured Gasoline on Everything : Why DoorDash, BNPL, Expense and Neo-Banking All Exploded at Once
24’24: The Lego Blocks for Payments : How Marqeta Armed the Innovators Who Couldn't Build Through Banks
29’19: Visibility as a Weapon : Why Being Public Helps Marqeta Win Customers Against Private and Embedded Competitors
33’15: Fewer Bets, Higher Probability : How Public Market Discipline Reshaped Marqeta's Risk and Profitability Model
36’35: The Legacy Platforms Were Built for Banks : Why Embedded Finance, Multinational Card Issuing and Personalisation Reshape the Pie
41’50: Prompted, Not Replaced : The Ten-Year View on Whether Volume Comes From People or Robots
43’56: The channels used to connect with Mike & learn more about Marqeta
Illustrated Transcript
Lex Sokolin:
Hi, everybody, and welcome to today’s conversation. We are very lucky to have with us today, Mike Milotich, who is the Chief Executive Officer at Marqeta. Marqeta is one of the original payment infrastructure companies and has been a fantastic success. So, I’m really excited to dig into its story as well as learn more from Mike about his own career. With that, welcome to the conversation.
Mike Milotich:
Thanks so much for having me. Good morning.
Lex Sokolin:
I want to start a little bit back in time focused on you. And I’ve noticed in your career that we have a little bit of overlap, that you were at Barclays Global Investors in the early part of your finance career? When I was at Lehman Brothers and we had been bought by Barclays, I remember that Barclays had sold BGI in order to buy Lehman Brothers, which I think is probably one of the historically worst corporate transactions you could do.
But it’s a fantastic business and now it is, you know, a huge ETF business and iShares, I believe. How do you remember your early career? What brought you to finance? What got you interested in finance? And maybe just pull on some of those early threads?
Mike Milotich:
I got started in finance mostly because I was quantitative in my orientation. So, I’m more of a math brain, if you will. And, you know, always was, you know, going through my school years. And I’ve always been inherently curious and analytical. So, I’ve always just noticed things and thought like, how does that work? Or, you know, wanting to explore more. And I feel like a lot of components of finance are more analytical. A lot of it is like peeling an onion and problem solving. And that’s just always something that I was interested in. And so, you can combine that with my sort of more data orientation.
Lex Sokolin:
What is inside the onion, and where do you use the onion? What do you season with it?
Mike Milotich:
Apply that, in particularly in the payments business, as an example, there are a lot of subtleties and nuances that matter. And so, the more you understand, the more you can connect the dots to add value. So, by peeling the onion and really getting down to really understanding how certain things work or interactions happen, the more you can apply that knowledge in ways that are advantageous, both from a career perspective, but of course always about adding value for the company and helping the company be more successful. That’s what helps your career. And so that’s how it’s really served me well, is that ability to connect the dots and then apply that to add value.
Lex Sokolin:
You did finance inside of financial services companies, right?
Mike Milotich:
Correct. So, I worked, I would say the better part of my career, American Express, PayPal, and Visa before I came to Marqeta. So, I’ve also been in payments a long time. But yes, all are financial services related.
Lex Sokolin:
What kind of things did you get exposed to, and did you see from that period — like the 2007 through that decade, starting with a great financial crisis — is really fascinating in terms of shaping, you know, the business models of whether it’s asset managers or whether it is payments companies. From the seat that you had early on, like with that fresh view, what did you notice? What did you see?
Mike Milotich:
I wish I could tell you that then I could really see how this whole financial services space was going to really modernize and get very innovative. I did not have that foresight. I targeted American Express as a place to work, as I had understood from many people that it was just a great company. And I was fortunate in that sense, that I sort of fell into it and then really embraced it, really liked it. I think what has served financial services very well is that it has always been very data driven. So inherently there’s more data in that business. And so, data-driven decision making and data-driven risk management, for example, has been around for decades, long before you had the kind of technology tools and capabilities that you have today. So, I would say the raw ingredients were always there.
And I think as you started to see technology come about — like, for example, my first job at Visa in 2011, when I joined, they had just created a mobile payments division. And, you know, at that time the smartphone was only a couple of years old, right? And so, Visa recognized that mobile is going to be very impactful in payments, but what exactly that’s going to look like is unknown, right? How it’s going to evolve is unknown. And what’s going to happen in the US is going to be different than what happens in Asia, which is also going to be different than what happens in Africa.
And so, you know, understanding that influence of how technology is going to impact the business, but having all this data and understanding about how to make better decisions and be smarter about some of the bets you’re making as a business, I think, is what makes financial services maybe more unique or ahead of its time right now. Everything in digital advertising and marketplaces is also all about data and data mining. But I think financial services was probably, you know, ahead in that regard, just because of the nature of how those business models work.
Lex Sokolin:
You brought up a really interesting example. So let me meditate on it for a moment. You know, the sort of moment when proximity payments and mobile phones became a real way that commerce could happen. Visa played an enormous role in that, but within some of the developments from Apple Pay and Google Pay. And it reminds me a little bit of where we are, and I know this is sort of a sidetrack, but where we are with agentic commerce, where you have, you know, everybody’s sort of like pregnant with the feeling that it’s coming. But it probably felt a little bit like that mobile moment. Were there parallels? How would you compare the two?
Mike Milotich:
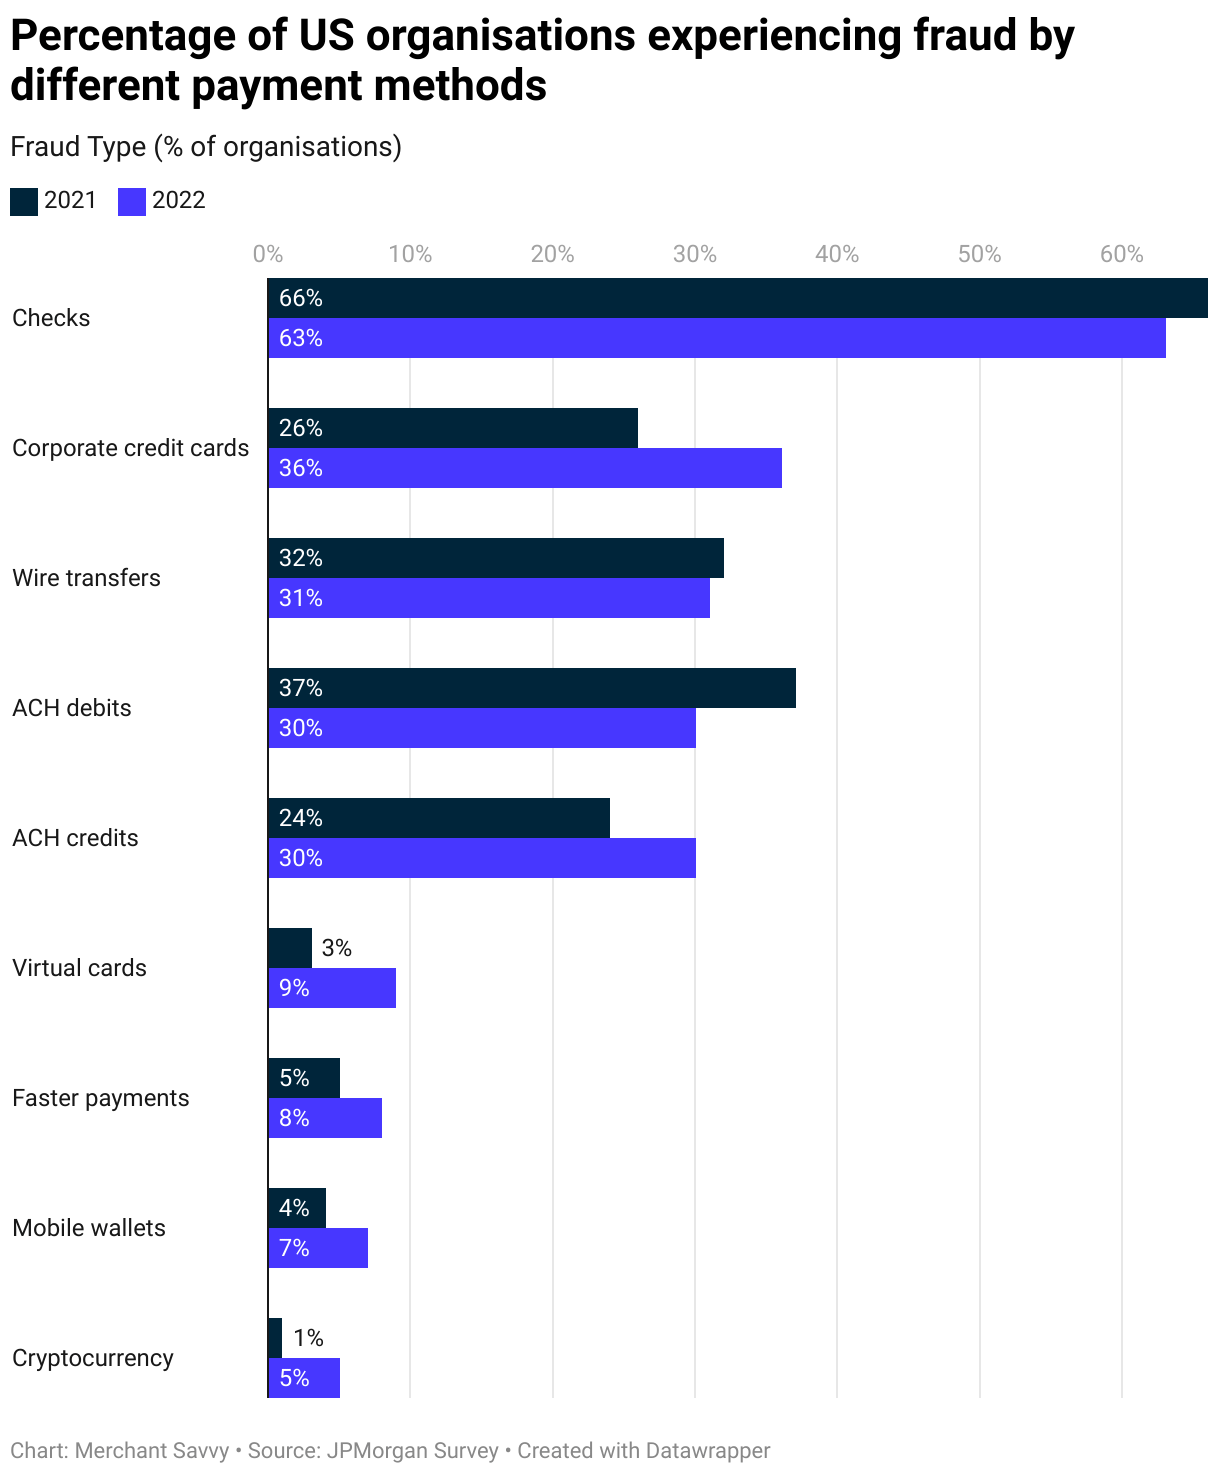
Yeah, I think what’s similar is that when the technologists drive the conversation, they tend to get a little bit ahead — the narrative gets ahead of the reality, right? Because what’s possible with the technology is always very exciting. And I would say those two things are very similar in terms of the early days of mobile and the early days of agentic. So, what’s possible is very exciting, and the people who are driving the technology, I think, get ahead of the — again, some of the challenges and nuances of payments in terms of security, first and foremost. Like, how do you — you know, fraud is a huge issue and factor in everything related to payments. And it affects both the people who are trying to provide those payment options, who take the liability, but also in terms of consumer behavior. Consumers tend to be slower to change their behavior than I think a lot of technology enthusiasts think, because it’s money. People inherently are quite conservative. And so changing behavior takes a long time.
So, I would say security is something that has to be solved. And then there are other things that are just, again, practical things that nonpayment people don’t tend to think about. So, as an example, I often use, like between e-commerce and what’s happening with agentic, in the early days of e-commerce, a lot of retailers would talk about that they were sort of — they had to evolve to deal with the number of returns, right? When you were buying everything in the store, you tried it on, you saw it, you put it on, you looked in the mirror.
And so, the returns were relatively low. But in the early days of e-commerce, when you’re buying everything online and you’ve never put it on, you’ve never seen what it looks like, there was an increase in the returns rate. And that was like an operational challenge — then the impact of what was happening in payments became an operational challenge in retail. And so there are just things like that that have to be worked out. And that’s why things don’t happen with the snap of your fingers. It takes some time for not only people to work out the user experience and making it secure, but also some of the operational differences that have to be worked through. Investments have to be made; problems have to be solved.
Lex Sokolin:
I think it’s a blind spot for sure, in the people who invest in categories and tell stories, versus folks who actually have to make it happen. If we spend just a bit more time on your rise at Visa and the different parts of the business that you saw, I mean, Visa is a company that has stayed on top as a network of networks really successfully. And, you know, that’s a really difficult thing to do. What do you think allowed it to, you know, persist in this way? And as you kind of got more and more visibility into the company’s machinery, like, what are some of the things you admire about it?
Mike Milotich:
Two things in particular. So one is, there are very few businesses that are as global as Visa, in terms of — I think they operate in every country that isn’t sanctioned by the US government. So, they truly are, you know, everywhere, I guess, as the tagline says. But yet payments inherently — and you know this, you’re a student of the business — is local, right? So how things work on a local level is quite different as you move from country to country.
And so being able to do both is really a unique skill set: be global, but yet local at the same time. So, what things have to be done consistently for the good of having a global platform, but what things need to be local to cater to the local habits, tastes, laws, regulations, etc.? That’s a challenging balancing act, and I think Visa and Mastercard both have perfected that — you know, or honed that. Maybe not perfected it, but honed it over decades, right, of learning how to operate that way. And I think that was something that I took away and was very impressed with: the ability to balance both those things.
The second one that I would point to is a really healthy paranoia, right? You know, when you’re the leader in the space, you have a great position, competitive position. You have a great business model. There are many, many examples in history of businesses that get complacent, right, and sort of rest on their laurels. And I would say one of the things I’ve always admired about Visa when I was there is that there’s a very healthy dose of paranoia and a pride in kind of continuing that legacy, carrying that torch and not being the one who drops it, right? So every day, that sort of willingness to grind and say, I’m going to keep working to stay on top — you know, I think is something that I took away, that makes the, you know, the business one of the more special businesses out there.
Lex Sokolin:
Were there any organizational principles that you think allowed it to be global but local, or sort of traditional but nimble? People try matrix organizations; they try the pizza-size team. I think right now the idea is, let’s have everything inside of an AI giga-brain, and people are just nodes in the machine. Like, what was the organizing structure of the company that you think worked?
Mike Milotich:
The leadership, inherently the way the company is organized, is regional. So that’s what keeps them local. But all the functional expertise is global. So, they’ve struck the right balance of people on the ground to understand the local nuances, but then there are certain functions like the people running the network, or, you know, finance, risk, some of these other functions that are global in nature. So, you can’t go too local. I think they do that well.

I think what I saw as successful is they’re good at incubating new ideas. So even when, as I’d referenced, when I first joined in mobile, they recognized that — at that time they separated what they called an emerging products function away from the core product, away from the big machine of, you know, credit, debit, and prepaid. We need to kind of carve this out so that it doesn’t get kind of trampled or become an afterthought in comparison to the big business that’s being run.
And so I think that’s what they do very well. And whether it was some of those early emerging products or now with, you know, crypto and stablecoin and agentic — all these things, when you look at how they organize in those areas, they try to create separate teams that can really focus, and give them, you know, visibility at the most senior levels, right? It really is carved out with a lot of visibility, because otherwise it’ll get trampled by the big machine that’s being run of the day-to-day business.
Lex Sokolin:
Yeah, that makes perfect sense. Let’s transition to Marqeta, which is sort of the spotlight of the conversation. Can you give us a high level — what are the latest figures of the company? What’s the scale of the company? And maybe just what are the chunky leverage points?
Mike Milotich:
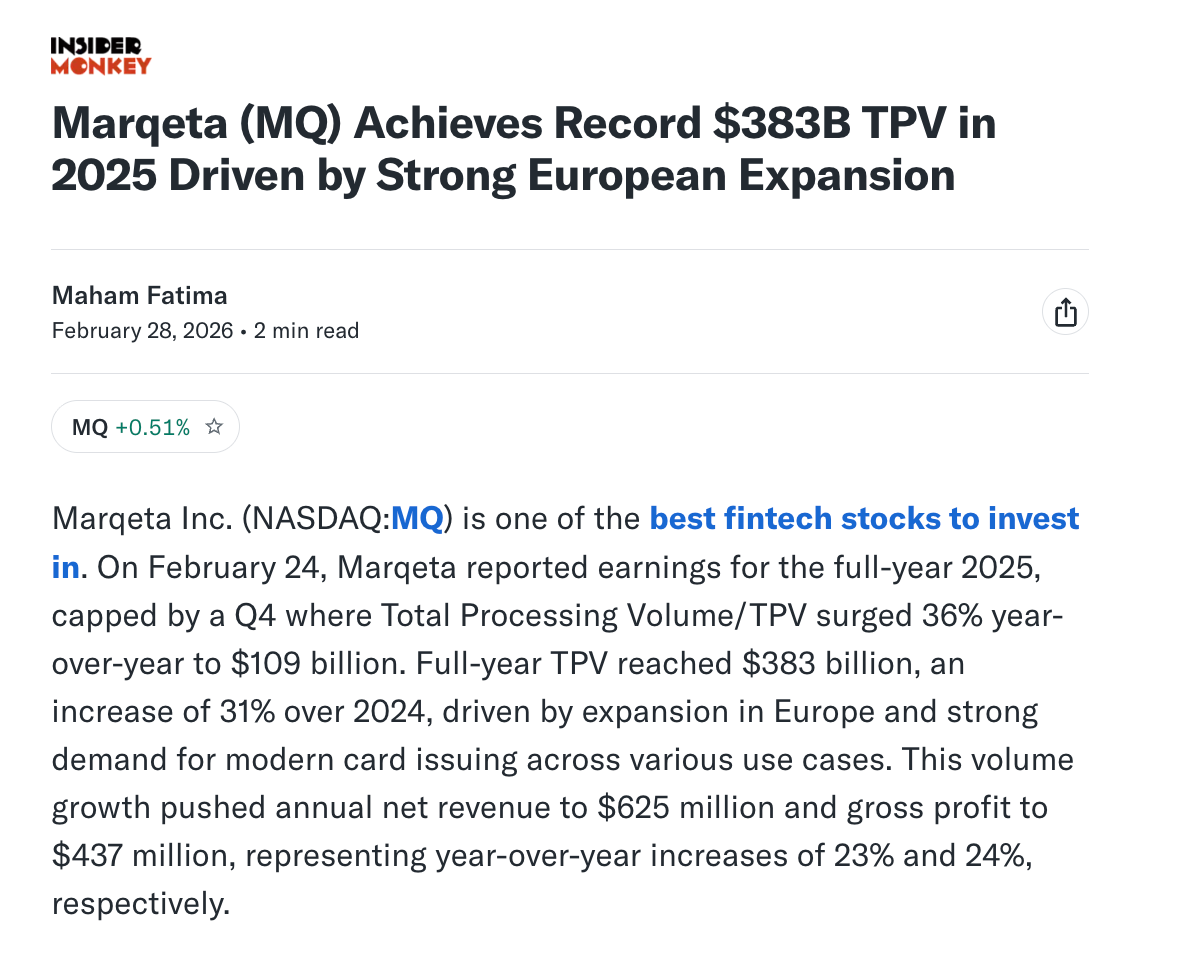
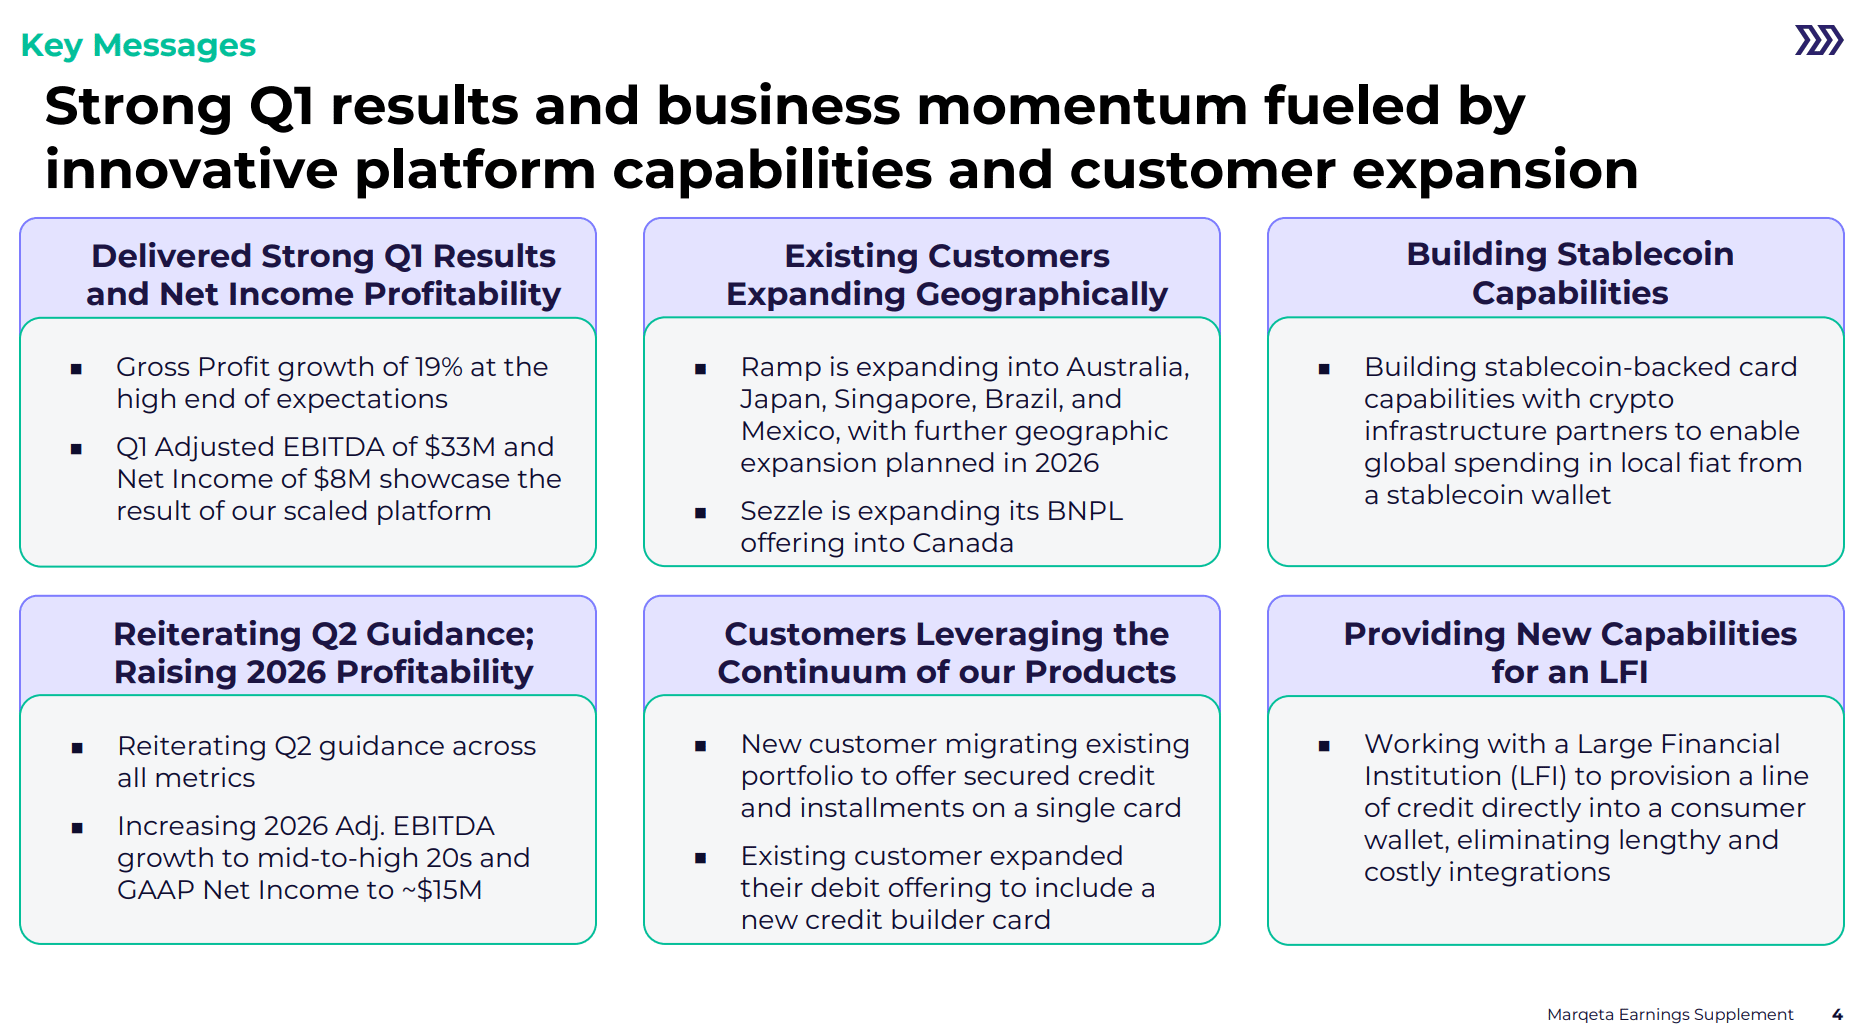
So, in 2025, we processed just shy of $400 billion in payments volume. And so, we’re getting to be, you know, pretty good size now. And that grew over 30% for the third straight year. And, you know, as you get bigger, right, it’s hard to compound at that kind of rate as the base, or the denominator, keeps getting bigger. So that’s something we’re quite proud of, is that ability to scale and get to that level.
And what makes us unique is that we service a lot of different use cases. So, a lot of the, you know, more modern players like ourselves tend to be more narrow in their focus. So, they only tend to do like one type of use case, for example. And what makes Marqeta unique and has allowed us to grow at that rate is that we support many use cases, whether it’s, you know, neo-banking, buy now pay later, expense management, on-demand delivery. But we do credit and debit, we do consumer and commercial, and we do it in over 40 countries.
And I’m sure one of the trends we’re going to talk about at some point is how more and more people are going multinational, where, you know, card issuing tends to be very local and individualized in the past. I think that’s changing with some of the developments in the market and some of the types of innovators and disruptors that we power. But that’s what kind of gives you a sense of the unique scale of the business and the way it’s growing.
Lex Sokolin:
When was the company founded? And if you think about its history, you know, were there a couple of turning points that really got you here? And I know you kind of stepped into the leadership role recently, but I’m sure there’s a sort of a myth of things that turned on, whether it’s, you know, the Square relationship or Klarna. How does that internal myth come together?
Mike Milotich:
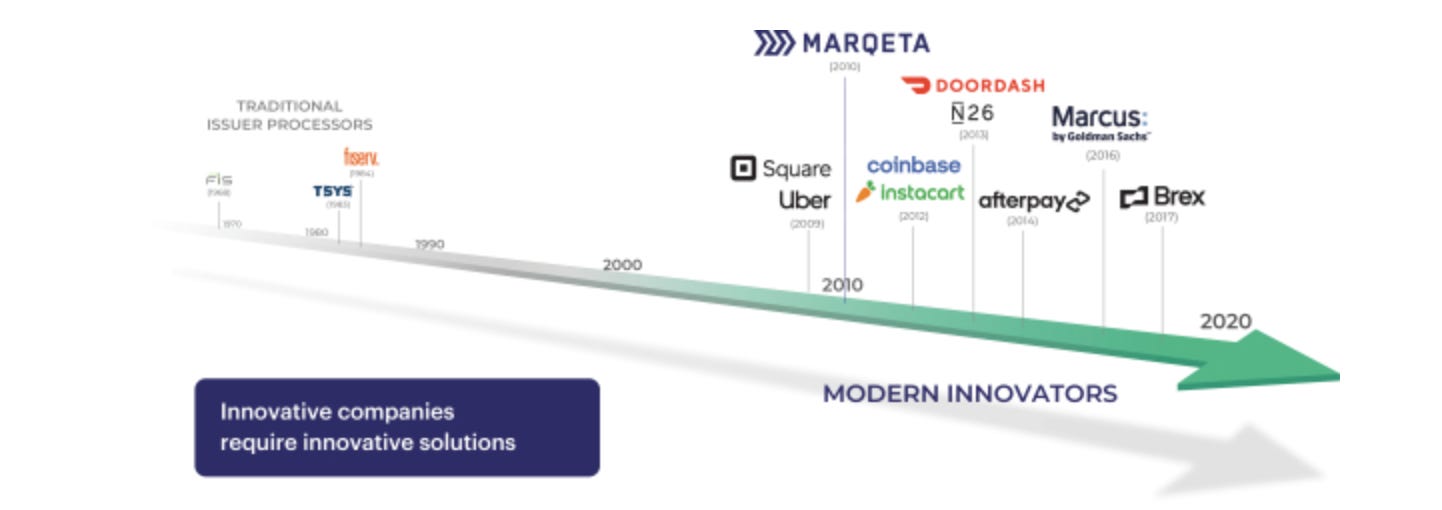
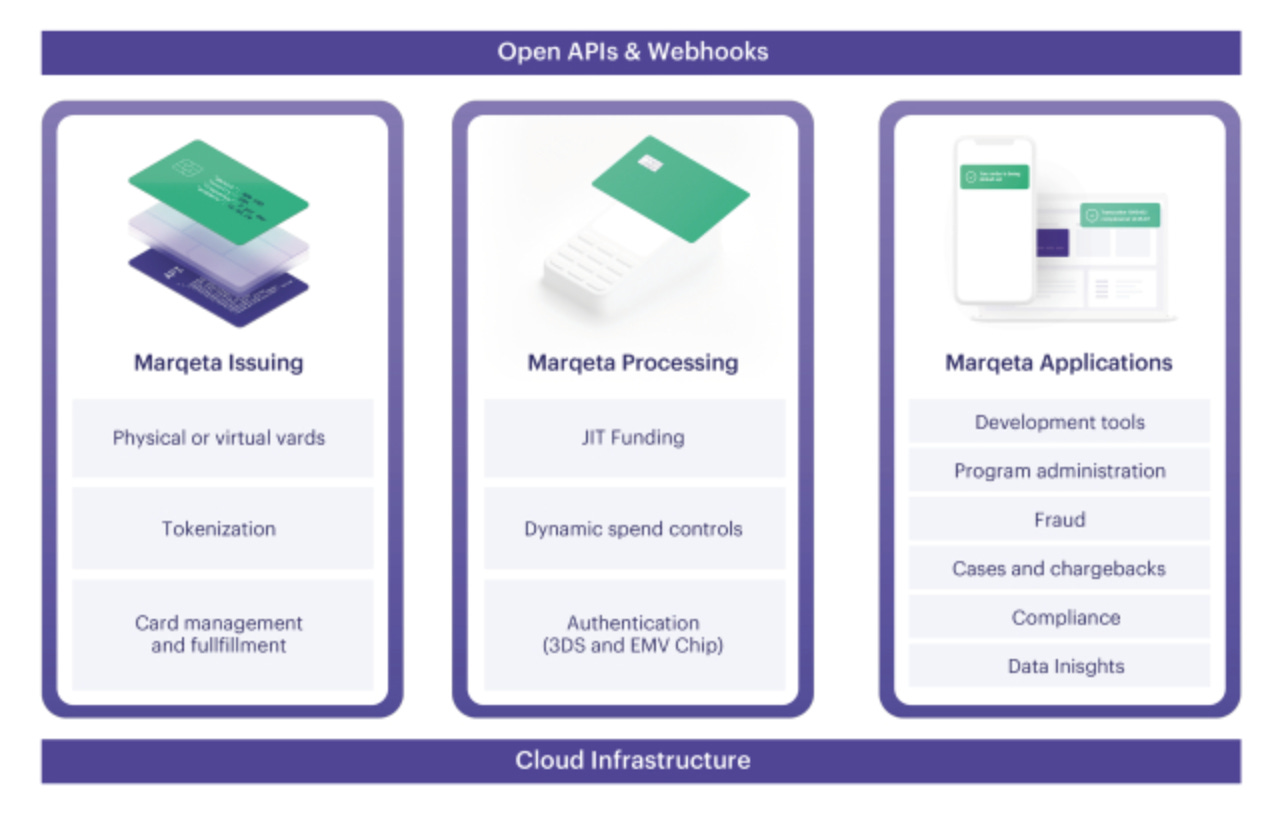
So technically the company was founded about 15 years ago, but I would say it was more like ten years ago — the 2015, 2016 time — when it started to become a real business. And the real innovation that I feel that Marqeta brought is — in the past, like before Marqeta, if you wanted to do something in card issuing, the bank controlled every aspect of that card program.
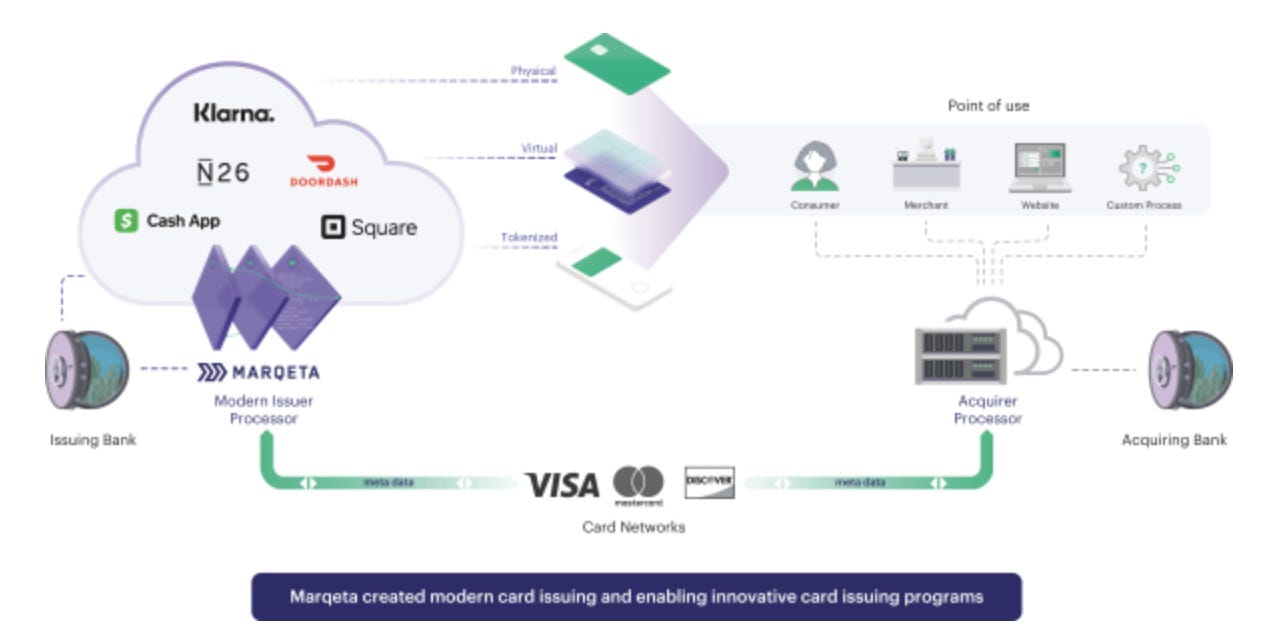
You know, if you think about some of the largest co-branded cards that you use today, probably that are, you know, affiliated with premier technology companies or major airlines or hotels, but, you know, you still manage those cards through the bank’s app, as an example. Like, that to me shows you — gives you a little insight into the history of what was possible. It had to be done that way in the past.
And what Marqeta came along and said is, you know, there should really be a better division of labor here. Because, you know, let’s just be honest, banks, because of the regulatory nature and the safeguarding priority that they have, they tend to not be super innovative. You know, they tend to not be very focused on user experience and product. Like, those are not their strengths. And so why are we having them control those things?
And so, what Marqeta did was really say, let’s have the bank focus on what they’re good at, which is the safeguarding of funds, making sure you’re compliant with, you know, laws and regulations. And let’s leave the user experience and the value proposition up to the brand, the company that really is going to touch the user and allow them to embed it in their experience, and have the bank be a little bit more in the background, playing a very important role but a little less visible to the end user.
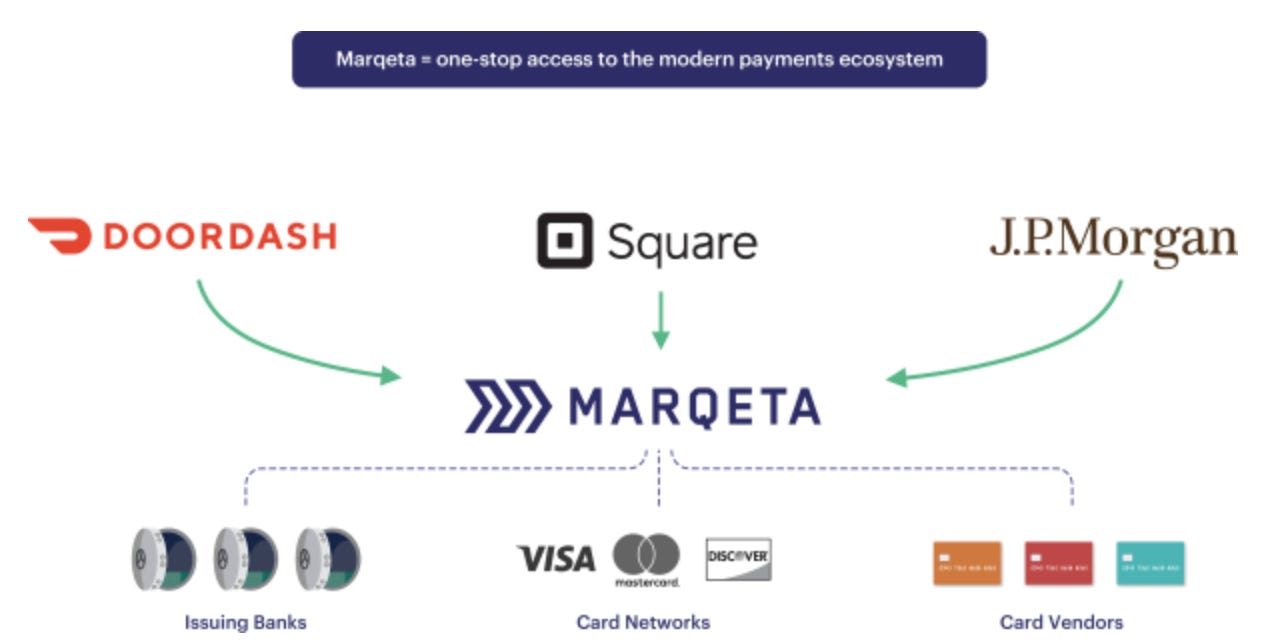
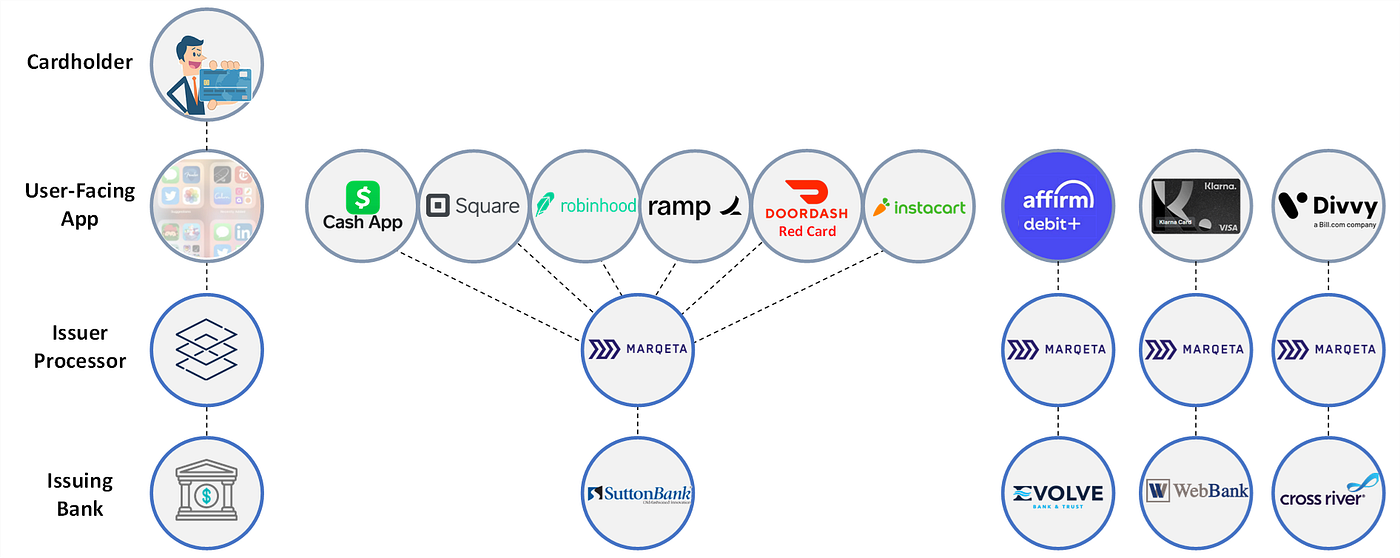
And then in the middle, what we can do as Marqeta is provide the technology and the expertise and the scale to help our customers. So, by us providing the processor and program management role, we can allow our customers, for example, to use different banks for different products, because each bank might only be comfortable with certain types of businesses. So, we can help our customers roll out multiple product types across different banks. But we can obscure a lot of that complexity, because they’re only dealing with the Marqeta platform, and they don’t see sort of what we’re doing behind the scenes to provide all that variety to them. And so, I think that’s what really separated Marqeta.
And so it was in that, you know, 2016, 2017, 2018, that’s when, you know, fintech really started getting momentum. And some of these companies that are now household names were really starting to, you know, figure out and hone their value propositions and start to get traction. And then it was, of course, the pandemic that I would say really, you know, poured gasoline on everything. In terms of — if you look at the major use cases we support, you know, on-demand delivery — I mean, Instacart, DoorDash, Uber Eats, all those businesses exploded with the boom of e-commerce during the pandemic. You know, buy now pay later went mainstream. You know, in expense management, everyone has been talking about for a long time about how to take cash and check, how to — B2B payments. It became more of a priority, in just a matter of survival in the pandemic, and that really provided a catalyst in that space.
And then finally, neo-banking, right — really having an embedded banking experience, either in a platform that you use for other reasons or just a very unique way of engaging you. You know, that became much more valuable once everybody was, you know, at home and on computers and devices more frequently. And so that was really the catalyst that really changed the trajectory of the company and our partners.
And then what’s happened in the last couple of years is, as the, you know, the fintech boom has, you know, sort of calmed — you know, the winners have been crowned, as I always say it. You know, there used to be 10 or 15 companies chasing the same thing. Now there’s been a little bit of a shakeout and it’s clear who the winners are in this space, and they’re becoming big businesses. And as they become big businesses and there aren’t 15 people chasing the same thing, they are spreading their wings, moving into new products, new geographies. And the Marqeta platform really makes that fairly seamless for them. And so that’s really what has, the last couple of years, fueled our growth — that expansion of what used to be, you know, kind of fintech disruptors into, you know, very big companies.
Lex Sokolin:
I think there is a through-line to something we talked about before, which is your experience seeing mobile become a new channel and kind of Visa positioning ahead of it. And then the agentic commerce wave where, like, the demand is not there, but, you know, it’s time to plant a flag in the ground and position ahead of it. To me, it seems Marqeta did a really similar thing, because it was an embedded finance company before there was embedded finance as, as like this category, right, where instead of selling financial products to consumers or to like a partnership manager that would sign a legal contract with you, you’re effectively selling to developers and people who are focused on building software.
You know, obviously Stripe’s been a huge success in that on a very particular use case. But then there are companies in different verticals, whether it’s, you know, renting a bank or card issuance or capital markets and so on and so forth, where selling and embedding your fintech services or your financial services with a sort of like regulated chassis is the whole game. And, you know, to me, there’s a big symmetry to Marqeta’s experience. I looked at it in detail quite a few years ago, and the thing that really struck me about the company is, as you said, it was founded pretty early on, and the product had been live for three years until Cash App and DoorDash launched. You know, like, CashApp and DoorDash launched in 2013. And these are huge drivers of the business. You know, I imagine just like the stress of sitting there for three years, having this feeling of like, we have it totally right, like the wave is coming, there’s no demand of any kind. You know, and doing that for three years and having the conviction to get to the other side of that, and then your clients just like materialize, right? To me, that’s such a powerful entrepreneurial story.
Mike Milotich:
That’s right. I mean, we really armed, it’s a little bit of a cliché analogy in business, but I really think the way our business works is we’ve really provided the Lego blocks for, you know, innovative companies in payments to build their own service and their own offering. And that just wasn’t possible before. Again, the bank kind of controlled everything and you had to go through them. And so once you, you know, you give these, you know, brilliant and creative people the Lego blocks and you set them free, they’re going to build some pretty incredible things.
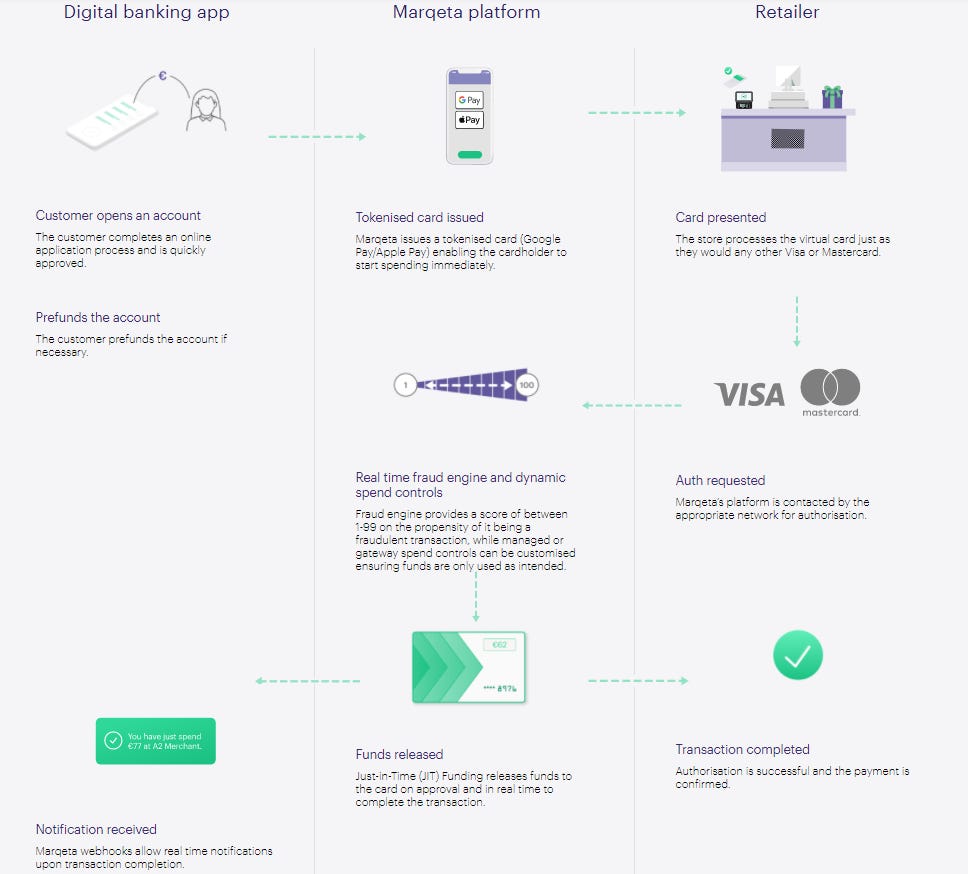
And again, consumer behavior in payments takes some time. So you don’t just launch something and everyone flocks. Like, it usually doesn’t work that way, because you’ve got to change their behavior. But more and more people started seeing the value, right? And they were delivering the value. And then you, you know, you start getting more and more momentum, and good things start to happen, and they start to evolve, right?
I think if you look at, like, buy now pay later, for example, is one of our fastest-growing use cases. You know, it’s a good-size business for us, and it’s growing incredibly fast. The last couple of quarters have all been over 50% growth on a year-over-year basis. And the transformation that’s happening there is quite interesting, where the original problem we helped solve for the buy now pay later companies was merchant scale, right — rolling out a product that’s more merchant facing, because you needed to click on the button on the checkout page. You know, there are tens and tens of millions of merchants. And that’s a very challenging endeavor to get the footprint you need. And we solved that problem with virtual card, and essentially eliminated that need for all those merchants to do, you know, technology integrations, but still allow them to accept this new form of payment.
And so that helped the buy now pay later companies’ scale. But then the last couple of years they’ve been shifting to be more of a consumer value proposition. So, in those early days, it was all about getting their mark on the website, right? And the merchant was pulling their business through. The emerging trend that’s now happening is, more and more they’re issuing the consumer the card and saying, a feature of the card is to be able to buy now pay later, and that card can be used anywhere that cards are accepted. So, I don’t have a merchant acceptance problem now — I can just engage the consumer to deliver my value proposition. And so, you know, those are also the things that have happened during this time — these businesses are also evolving, you know, as times change and they get bigger and they become, you know, again, more trusted and have more brand recognition. Their business models are evolving, and we, you know, do our best to make sure we’re on the forefront of that, and we enable them to make those evolutions and have that flexibility.
Lex Sokolin:
So, let’s transition to today. I’m really interested at maybe a somewhat prickly topic: public versus private markets. Like, as you said, Marqeta is one of the largest winners in this space, and it’s now a public company. It is generating more volume than ever before and has more business lines and kind of commercial traction than ever before. And yet, I think it’s so much harder to be a public company than a private one, because in the private world, you’re only valued based on sort of a conversation with venture investors. You might get 20 to 50 times revenue as your valuation. The story is kind of enough to get you through, and people are just chasing growth. And then you get to the public markets. And I think a lot of the public markets are just bigger. And so no matter how much venture backing you have and how many growth investors are behind you, you are going to run into people who are just like, I’m a banks investor and this is a bank, and I only look at this company through a spreadsheet, you know, and they don’t maybe appreciate the color and the richness of the struggle and the story.
What has been the experience within the company for, like, adjusting to that reality? Is there an operational reflection in terms of what the company can do, in terms of how it makes its choices? You know, and especially given your experience in investor relations and corporate finance and kind of like that core skill set of communicating with the public equity world, what is it like for a really hot fintech unicorn to jump into the sobering pool of the public markets?
Mike Milotich:
It’s an experience, right? The analogy I often use — you know, we were relatively young as a company when we went public. And so, the analogy I often use is that we’re a child star. We’ve been growing up in the public eye. And I think it’s a good analogy, because you have to adjust your behavior in terms of, yeah, how you communicate and how clearly you do that and how you do it on a consistent and regular basis. As opposed to when you’re private, there’ll be certain points or junctures or certain meetings where you have to be very articulate and communicate your case well, but those are more infrequent. Versus once you become public, every day you’re being evaluated and measured on a day-to-day basis. And so, the clarity with which you communicate and the consistency with which you do it becomes very, very important.
Once you embrace it, I guess it makes you stronger, right? So, the key is — and I think something that we’ve done well the last couple of years is to, rather than, you know, sort of say, you know, woe is me, I’ve got, it’s so hard. It’s more like that scrutiny and that competition — because essentially the market is, it’s supply and demand. So, there’s only so many investment dollars out there. You’re competing for them. That really makes you stronger and makes you better if you embrace it.
It’s a challenge. And I think that’s what we’ve done well, particularly because we really view that we have the ingredients to be a very big business. And so if we execute well — and so sort of accepting and embracing that challenge, I think, does make you better and helps you maybe prioritize and not, you know — one of the things I saw, for example, when I first joined that were more from our, you know, private, more startup roots, is trying to chase like seven things at one time, for example. That can be very challenging. You spread yourself thin. You tend to waste a lot of investment dollars, and it’s very hard to execute. Versus now, I would say we try to do three things at a time. And you have a list of, okay, once one of those is done, you’ve got the next one up, right? That you slot in, and allow you to focus and execute a lot better.
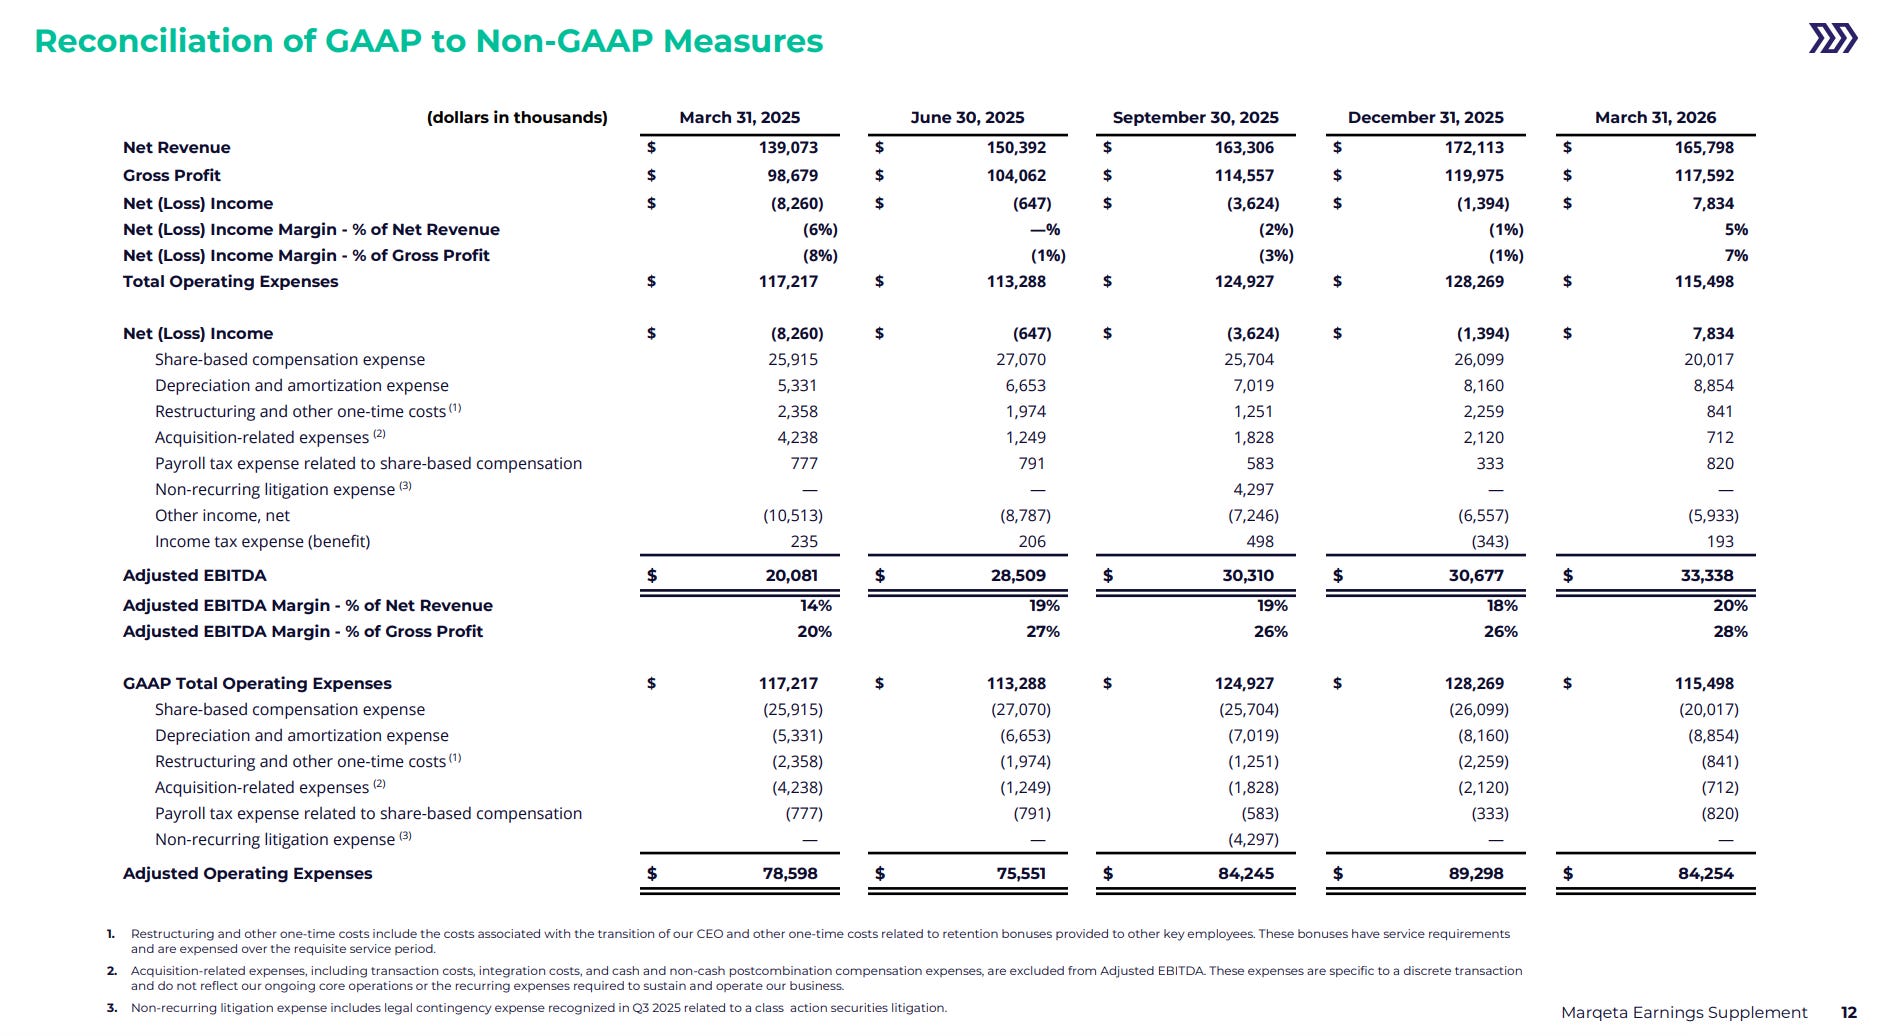
I also think that it’s served us well with customers, because they can see exactly the health of the business. So we can’t hide in terms of where we are financially. You know what we’re up to every quarter. We have to talk about what’s happening in the business and where we are and things we’re focused on. And I think for the most part that helps us with our customers and our prospects, because it’s very visible, you know, what we’re up to as a company and the strength of the business. Versus many of our competitors are either private or are a small piece of a much larger public machine, so there’s not a lot of visibility into what’s happening and how well they’re performing. And so, we’ve tried to embrace these things and turn it into a strength, rather than, you know, feeling sorry for ourselves, if you will, as the market fluctuates as it has, particularly in fintech, over the last few years.
Lex Sokolin:
Does it change how you think about risk for the company? You mentioned sort of finding focus and being more transparent, but in terms of, you know, going back to that question of a successful organizational structure and how much responsibility you give to individual product leads, or, you know, how you do budget allocations — has the discipline of being public changed that operating texture of the company?
Mike Milotich:
A little bit, I would say. It’s all about calculated risk, right? I think you can be a little bit — if you’re private, you know, no one’s going to know if, you know, if you try something and it really doesn’t work. And so, there’s something freeing about that. But also, that can, you know, lead to more variability. Like, sure, you can have home runs, but you also have a lot of strikeouts, right? Because you didn’t necessarily do as much work and sort of pre-planning and thoughtfulness before you just started running.
So, there’s good and bad. But I would say, you know, we still do a lot of innovative things. We’re always looking to push boundaries, both things we think of or things that, you know, customers or prospects may bring to us and we work on together. And I think it really just comes down to calculated risk: how do you really think through the things you’ve got to watch out for, and what are the gating mechanisms? So, what’s the progress? What are the milestones I’m going to be looking for to make sure we’re on the right track and this is leading to something — as opposed to, this is really just a science project that, you know, isn’t going to get traction or lead to something that really helps our customers grow their businesses. Because ultimately, we’re an enabler, and that’s what we’re looking to do.
So, I think it just gets you a little bit more disciplined in terms of, let’s really think through this, and let’s consistently evaluate the progress we’re making, and just be honest about it. And that’s worked well for us, where we can strike that balance between improving, you know, our profitability — because that’s the one thing, when we went public that was fine at that time, that, you know, we didn’t make money, but we were, you know, driving growth and causing disruption, and that was enough for shareholders. But that has changed.
And so, you know, over time, as we’ve gotten more and more scale, we get the benefits of that scale, and that shows up on the bottom line. But also, the discipline with which we’re operating means that if we pursue fewer things, but they become higher-probability successes, we actually are better off, not just on the top line of the business, but also how much of that trickles down to the bottom line in terms of profitability.
Lex Sokolin:
I spent a bit of time in equity research, so I apologize on the behalf of all analysts out there who think that they can manage a company better through spreadsheet assumptions than by actually running it. If we fast forward — and this is obviously like an imagination exercise, not anything specific — but you mentioned that there is a huge opportunity for the business in the future. And you know, that’s demonstrably true. There are several large payment networks that are each worth about half a trillion. You know, the payment processing companies that are in the hundreds of billions. At a moment of time when Marqeta is a $100 billion company, what does the world look like? Like, what are the things in the environment that have changed that you think get the company there?
Mike Milotich:
There’s a few. And I would say, you know, the seeds are already planted and being nurtured right now. So, there’s a few things happening. So one is, if I were to, I guess, summarize it, it’s non-banks providing financial services. And you said it earlier, embedded finance. Like, we’re still in the early days of that.
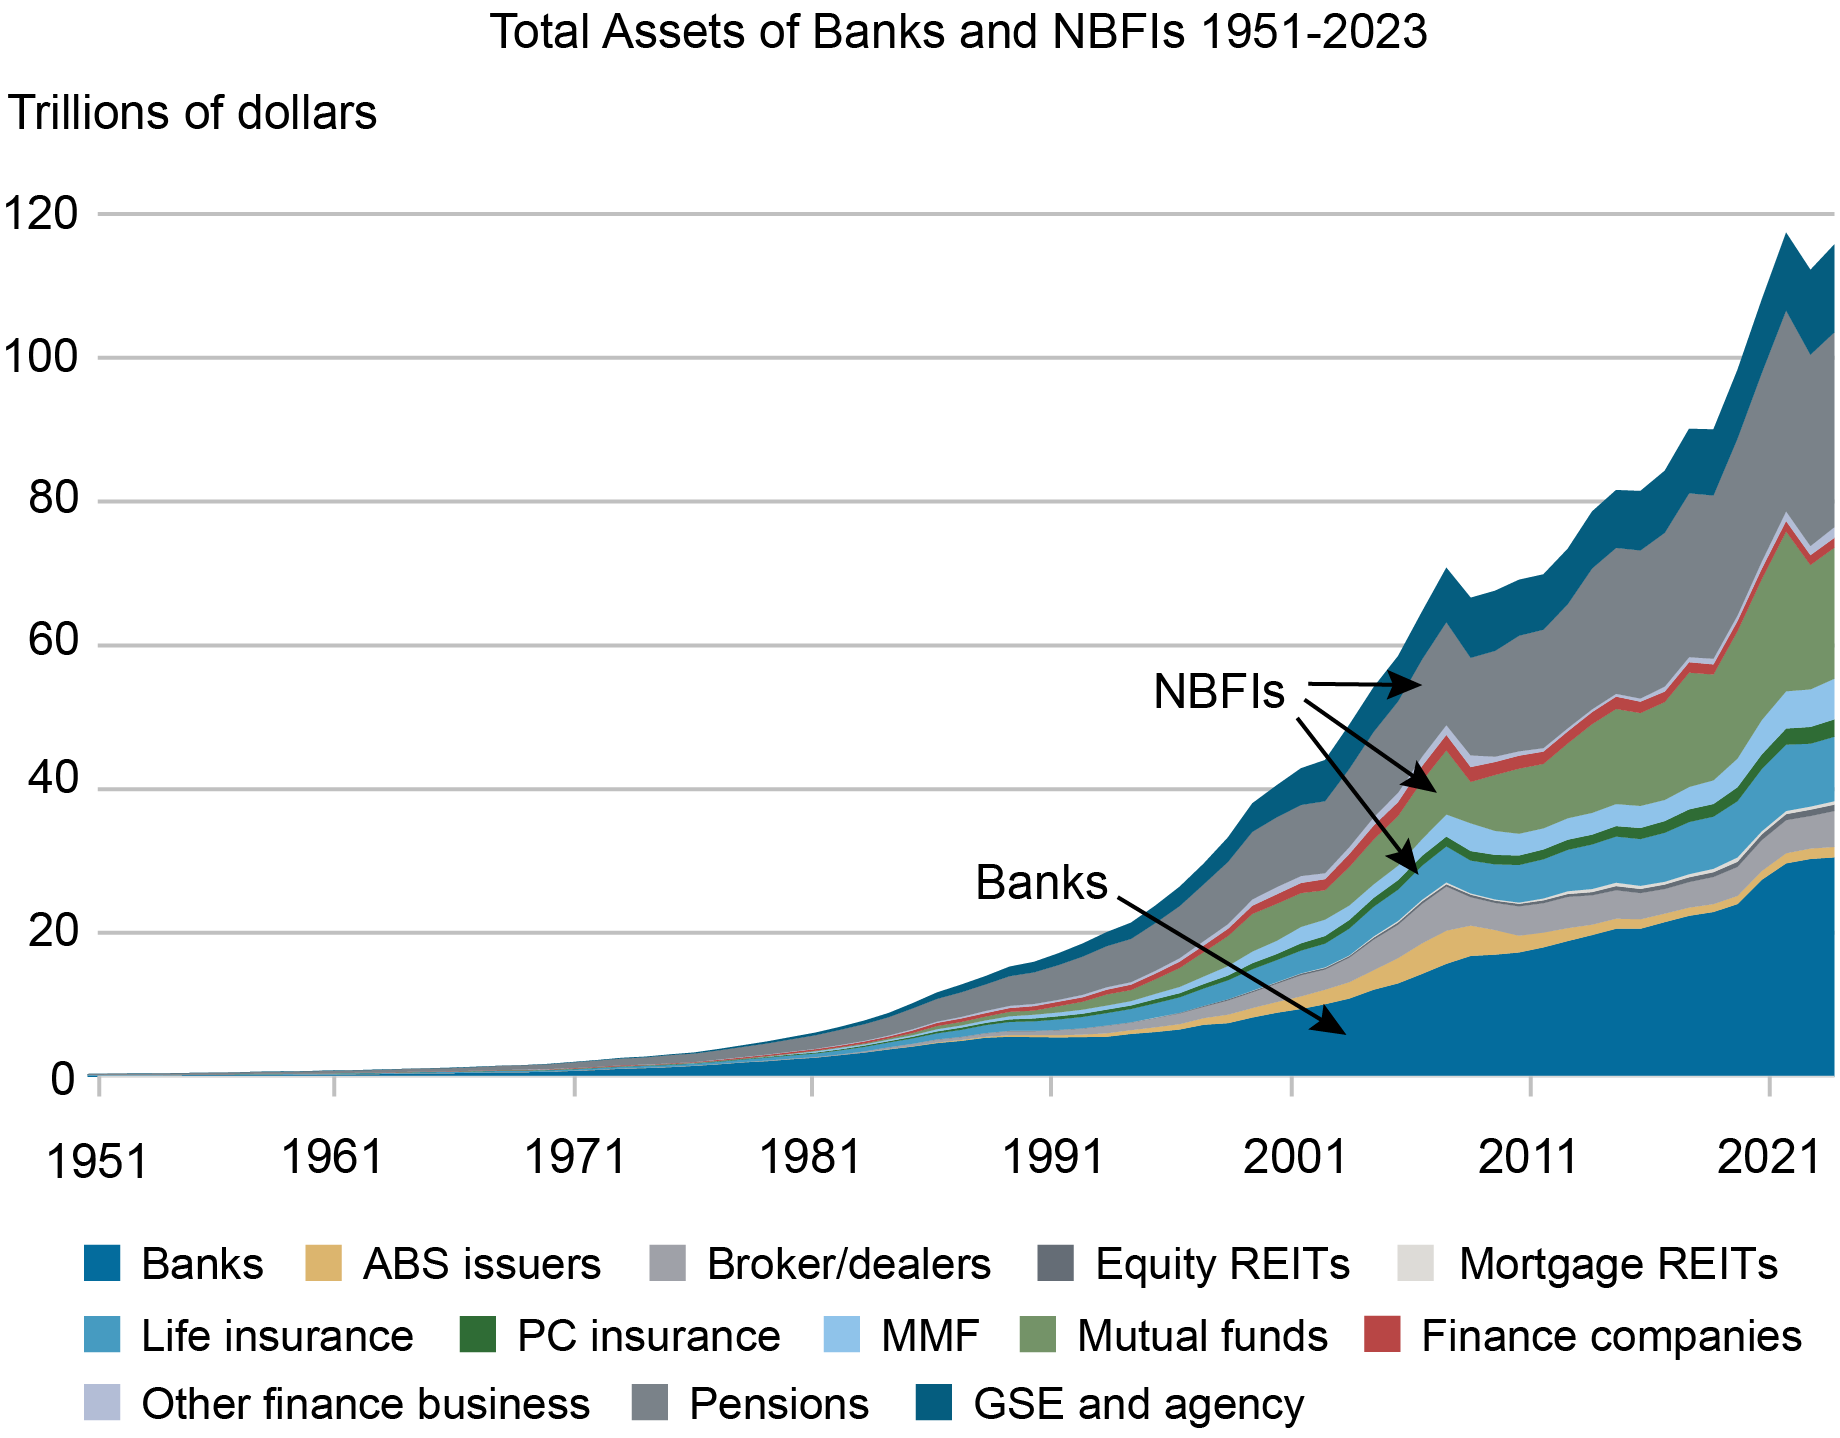
And what we see happening is, fintech showed what was possible, right? So that was the definition of fintech. And they showed what was possible. But a lot of the challenge that fintechs ran into is they had to build their business from scratch, and the cost of acquisition to build their business became unwieldy. But what’s happening now is, big companies that already have platforms that have tens of millions of users are saying, well, I could inject a financial product, like I saw fintechs do, and really drive engagement and loyalty. And so that’s one of the next waves. And a lot of our more legacy competitors — we have a diverse set of competitors, but the ones that are the biggest and have been around the longest, their platforms are really set up to serve banks. And so, there’s a real opportunity to serve this emerging business that’s being driven by non-financial-service companies.
The second thing I would say is, as those non-financial-service companies move into this space, they’re global already, almost by nature. So, if you think about the way banks work — banks are really local. Like, there are some multinational banks, but they’re more multinational on the commercial side in terms of treasury management and things like that. You know, there’s only a handful that are truly multinational on the consumer side. But most businesses, whether they’re large retailers or their tech platforms, are global. And so that ability to have one platform that can serve them across many different geographies and do that in a relatively seamless way is a big opportunity. And you see some of the neo-banks, I would say, are probably the furthest along in terms of being multinational, right? When you look at, you know, Revolut or Nubank, some of these, you know, businesses, they are going more multinational.
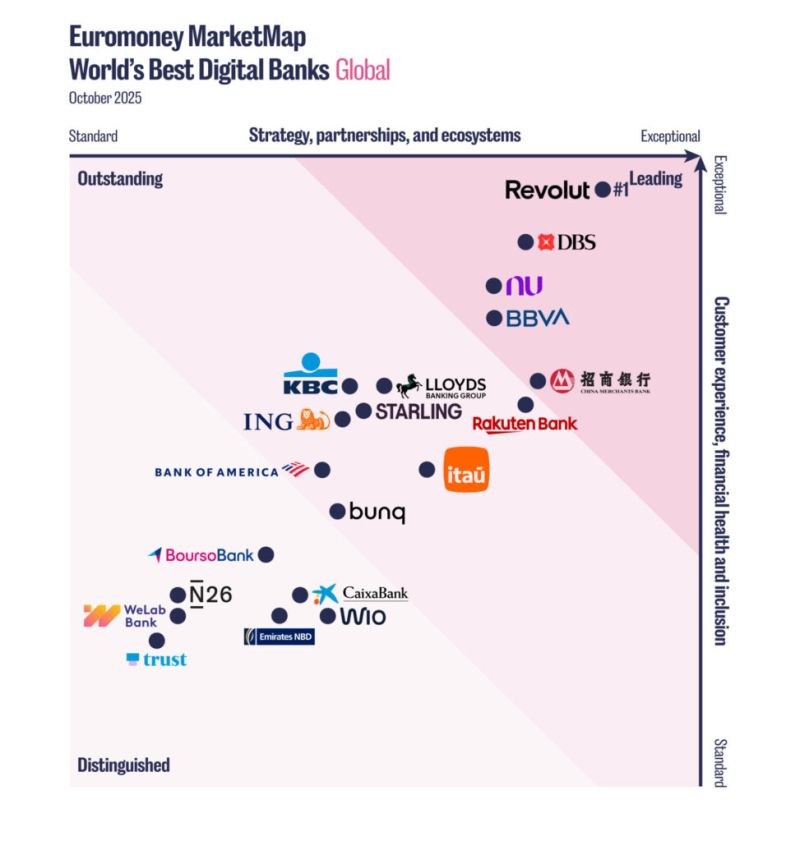
The other thing that I think will drive a lot of success for us is, as these fintechs and embedded-finance companies keep having success, they’re putting more and more pressure on the establishment, which is the banks, who, you know, still control the bulk of this business and have, you know, owned it since the beginning. There is more and more momentum for them to modernize, because they have to compete. And so, what I think is the exciting opportunity for Marqeta is that up until this point, we have mostly grown the pie. So, we’ve mostly served use cases that maybe weren’t on a card before, or servicing a customer base that, you know, couldn’t get kind of mainstream financial products. But I believe we’re on the verge of entering the era where there’s a modernization that comes to the industry, where we start displacing volume that is on platforms that are less capable and don’t have the flexibility and capabilities that Marqeta provides.
So that’s what we’re working towards. And there’s a number of ways we’ll do that in terms of different product categories. But if I were to think forward, in terms of what makes us a much bigger business, that’s what it is. Like, an example — I’ll just give you one example, and then I’m sure you’ll have other things you want to ask me — but personalization hasn’t really come to the card business and maybe most of financial services. Versus with everything being so much more digital now, many other aspects of your day-to-day interactions outside of payments are personalized. But that hasn’t come yet to payments. And we believe it is coming, and it requires, though, you know, real-time data and being able to analyze things in real time and respond. And so, you need modern technology to do this. But this would come in the form of rewards that are customized to you versus me. We might have the same card, but the way we get rewards on that card is different based on what’s valuable to us. And that’s a trend that, like, we believe is going to come to the card business. But it requires really modern technology to make that happen. And so those are the kinds of things that, you know, we can enable, and can help us, you know, fuel growth and become a much bigger company, you know, five years from now.
Lex Sokolin:
Last question to close us out. So, in that world, you’re a $100 billion company. You’ve got all these things going on. If you look at your volume, will more of it come from humans or from robots? And I use the word robots, you know, pretty liberally — algorithms, programmable money, software, right? But are we in a world where using a card, even if it’s a virtual card on a mobile phone, is sort of the equivalent of sending a letter by post? If you fast forward to this future where you’re at the scale that we’re talking about, everything you could do for humans has been done, and you look at your volume — is it going to be still people, or is it going to be this machine economy?
Mike Milotich:
Obviously, I don’t have a crystal ball, but the limited one I have maybe only gone out, say, ten years. I think more of it is still controlled by humans. I think there are things that, no doubt, agentic is going to help people do, and it’s still going to be human-controlled, but it might just be that you talk to it, or it prompts you, right? You’re still going to make the decision, right? But it might prompt you. You know, hey, you’re getting low on this — should I get more? And you say yes, right? So, I guess it depends on how you define it.
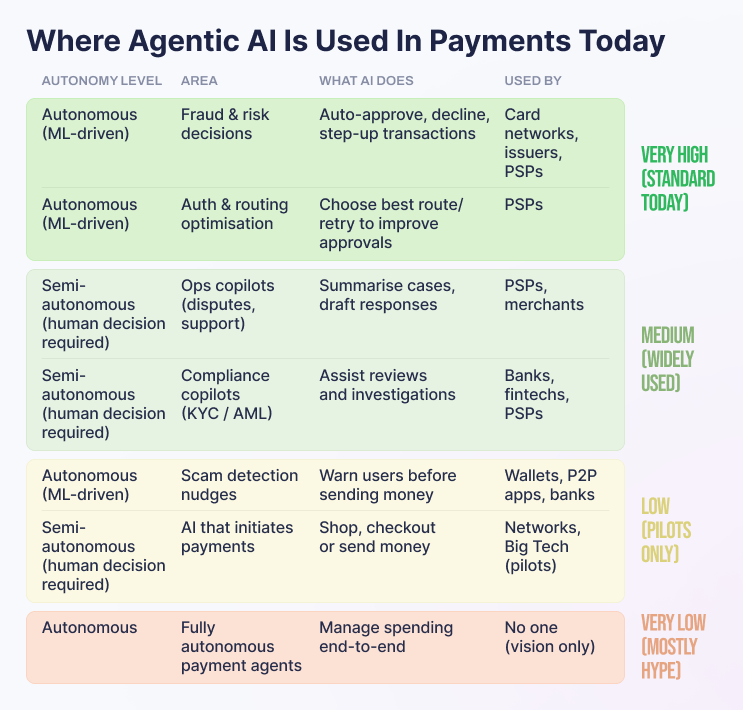
So, I think we’ll still have a lot of human-based decision making, just because it’s money, and it’s hard for people to completely relinquish control of how they use and spend their money. I just think that’s going to take a long time to get people comfortable with that. But will a lot of robots, to use your word, you know, sort of be guiding you through that and prompting you? I do think that, you know, five or ten years from now, there’ll be a lot more of that. That’ll make it a lot easier for you to make those decisions, as opposed to now, you have to do some work to make that happen.
Lex Sokolin:
Despite your experience as a financial professional in financial services, I think you’re still a romantic and believe in the human spirit, which is nice to see. If our listeners want to learn more about you or about Marqeta, where should they go?
Mike Milotich:
The easiest place to go — well, certainly about Marqeta — would be to go to Marqeta, and also podcasts like yourself and other, you know, fintech industry publications. That’s where, you know, we do power many of the fintech winners and disruptors. So that’s a great place to look. And I’m probably less interesting, so I’ll leave it at that.
Lex Sokolin:
Fantastic. Thanks so much for joining us today.
Mike Milotich:
Thank you for having me.
Postscript
Sponsor the Fintech Blueprint and reach over 200,000 professionals. 👉 Reach out here.
Read our Disclaimer here — this newsletter does not provide investment advice
For access to all our premium content and archives, consider supporting us with a subscription.


