
Gm Fintech Architects —
I’ve got a real treat for you today.
Together with the analytics company Artemis, the Bloomberg terminal for digital finance, we are launching the first-ever 👉 comparison analysis of Fintech & DeFi KPIs. If you ever wondered whether Robinhood or Uniswap is the better asset to invest in, you’ve come to the right place.
Summary: We put fintech equities and crypto tokens on the same page, literally. Across payments, neobanks, trading, lending, and prediction markets, we compare revenue, users, take rates, sector KPIs and valuation metrics. The results are surprising — Hyperliquid is 50%+ of Robinhood’s trading volume, DeFi protocol Aave has more loans outstanding than Klarna, stablecoin rails are growing MUCH faster than traditional payment providers, wallets like Phantom and Metamask user numbers rival neobanks like Nubank and Revolut. We find that valuations reflect this tension, with crypto assets priced either at steep discounts or extreme premiums depending on perceived future monetization. Ultimately, we argue the core question of convergence is whether crypto learns to build tollbooths or fintech adopts crypto’s open rails.
Topics: Block, PayPal, Adyen, Tron, Solana, Coinbase, Robinhood, Uniswap, Aave, Affirm, Klarna, Polymarket, DraftKings
To support this writing and access our full archive of newsletters, analyses, and guides to building in the Fintech & DeFi industries, see subscription options below.
Our Ecosystem: AI Venture Fund | AI Research | Lex Linkedin & Twitter | Sponsors
Report: The Two Financial Systems
For years, we’ve talked about crypto and fintech as parallel universes. One is regulated, audited, and trades on the NASDAQ. The other is permissionless and trades on decentralized and centralized exchanges. They share a language: revenue, volume, payments, lending, trading, but speak it with different accents.
That’s starting to change.
With Stripe acquiring Bridge, Robinhood launching prediction markets, and PayPal minting its own dollar, we’re starting to see the lines blurring. The question is how these worlds compare once they collide.
So we decided to run the experiment.
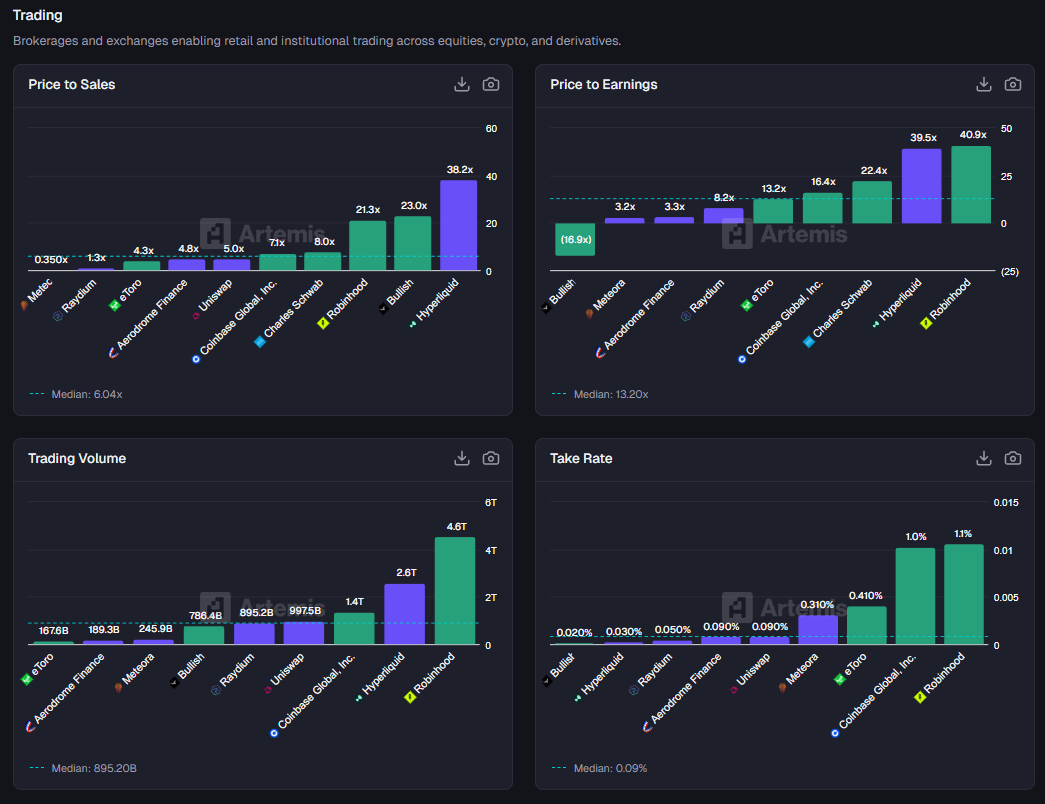
Take the fintech companies you know across payments processors, neobanks, BNPL lenders, and retail brokerages, and stack them against their crypto-native equivalents. We highlight the same fintech metrics you’re familiar with (P/S, ARPU, TPV, Number of Users, etc) on the same charts, with green bars for equities and purple bars for tokens.
A picture emerges of these two financial systems. Onchain finance protocols often match or exceed their fintech peers on volume and assets, but they capture a fraction of the economics. Crypto trades at high premiums or high discounts relative to fintech comps, depending on where you look, rarely in between. And the growth rates aren’t even close.
Payments: The money movement pipes
Let’s start with the biggest category in fintech — moving money from A to B.
On the green side, you have the giants.
Fiserv, the infrastructure layer no one talks about at parties, handles $320 billion.
Block (the company formerly known as Square) pushes $255 billion through Cash App and its merchant network.

On the purple side, you have annualized B2B payment volume estimated by the Artemis stablecoin team:
Tron moves $68B in stablecoins
Ethereum does $41.2B
BNB does $18.6B
Solana moves roughly $6.5B
The absolute numbers aren’t close. Stablecoin transfer volume across all major chains is roughly 2% of what the fintech payment processors handle. If you squint at the market share chart, the purple bars are a rounding error.
But here’s where it gets interesting — growth rates.
PayPal’s total payment volume grew just 6% last year. Block did 8%. Adyen, the European darling, managed 43%, which is strong by fintech standards. Now look at blockchains: Tron grew 493%, Ethereum grew 652%, BNB grew 648%, and Solana is growing the fastest at 755% YoY. Again, this is estimated B2B Payment Volume from the Artemis data team backed by research with McKinsey.
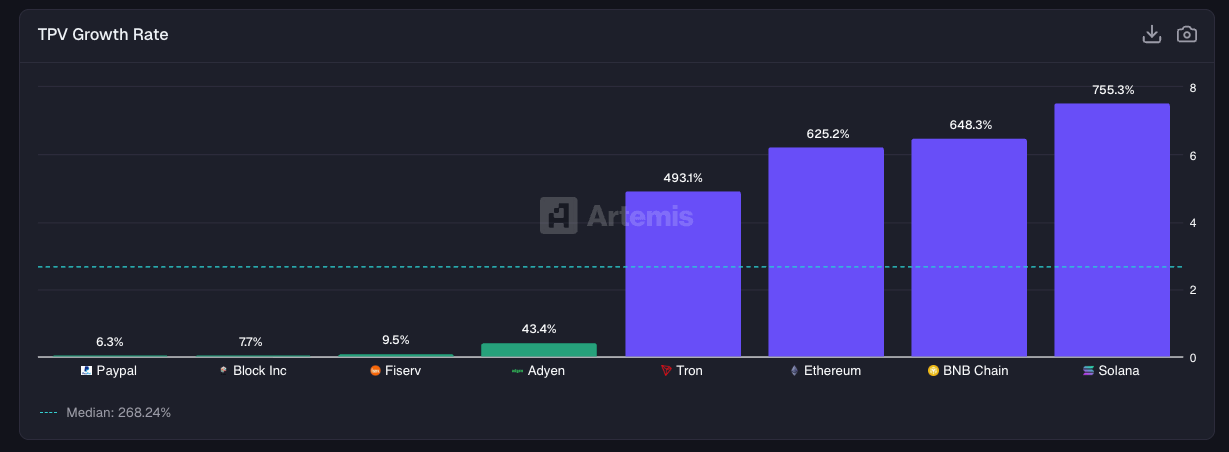
The stablecoin rails are growing MUCH faster than traditional fintech payments. However, they’re also starting from a much smaller place. Next, we ask who captures economics?
Fiserv takes 3.16% of every dollar it touches. Block takes 2.62%. PayPal takes 1.68%. Adyen, running a lower-margin enterprise model, takes 15 basis points.
These are real businesses with real revenue tied to payment volumes.
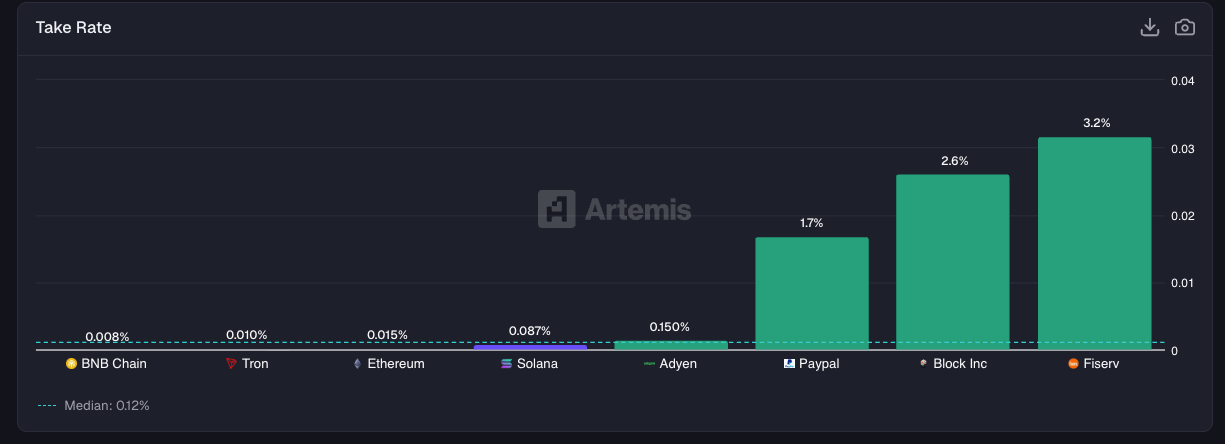
As for the blockchains, their take rate on stablecoin transfers and broadly asset transfers is significantly lower, ranging from ~1 bp to ~9 bps. Tron charges users TRX to cover stablecoin transfers and Ethereum, BNB, and Solana charge the end user gas fees or priority fees.
The chains are strong at facilitating transfers and moving assets, but do not take as large a cut as incumbent payment providers. Avoiding things like interchange and merchant fees is one reason why blockchains are able to claim massive efficiency advantages relative to existing payment providers. That said, there are plenty of onchain payment orchestrators that are happy to stack fees on top. This is indeed an opportunity for the facilitators to build economic value on top.
Neobanks: Wallets as the new bank accounts
On the fintech side for Neobanks, there are actual banks (or rent-a-charter banks) such as Revolut, Nubank, SoFi, Chime, Wise. These are entities with licenses, deposit insurance, and compliance departments.
On the crypto side, we see wallets and yield protocols such as MetaMask, Phantom, Ethena, and EtherFi. These are certainly not “banks”, but millions of people keep their assets here. And increasingly, this is where people earn yield on their savings. The functional comparison holds even if the regulatory wrapper doesn’t.
Starting with users:
Nubank has 93.5 million MAUs, making it the largest neobank on the planet, built on the back of Brazilian smartphone penetration and an overly complex banking system.
Revolut has 70 million across Europe and beyond.
Then comes MetaMask at 30 million, which makes it larger than Wise, SoFi, and Chime.
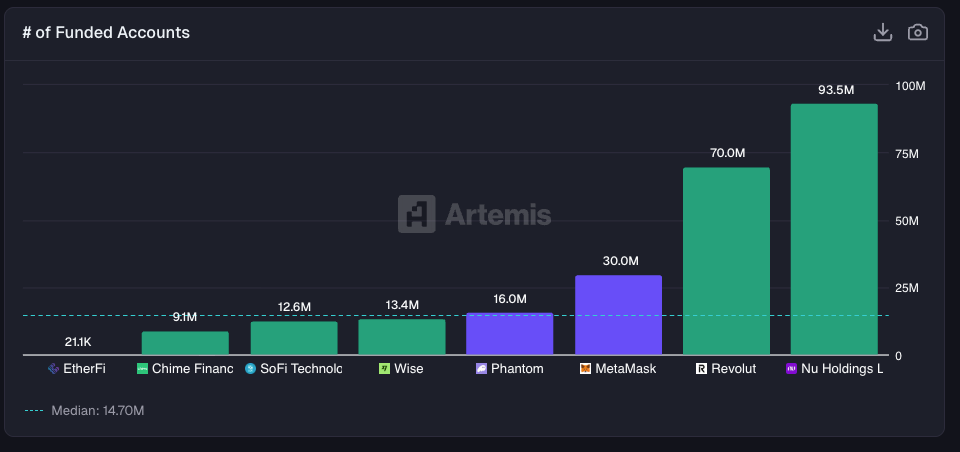
Most MetaMask users are not using the crypto wallet to pay rent, but to interact with DEXs or borrow/lend protocols. Phantom, another leading wallet, has 16MM monthly active users. Phantom started as the best Solana wallet, but quickly expanded to other chains and now offers its own stablecoin $CASH and debit card, tokenized equities, and prediction markets.
Now look at where the money sits.
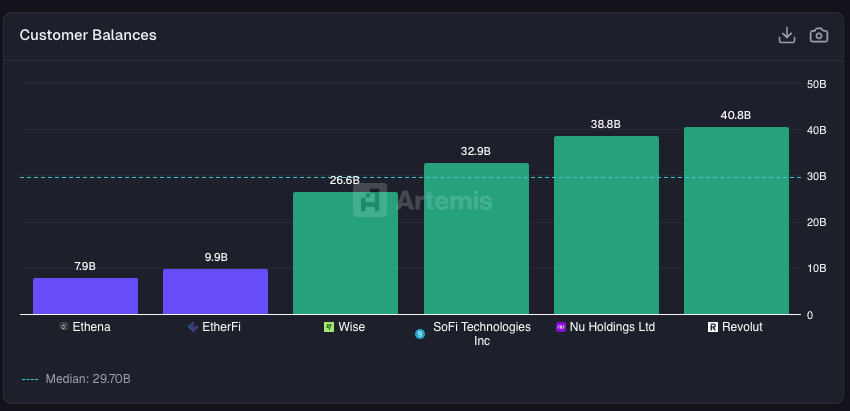
Revolut holds $40.8 billion in customer balances
Nubank has $38.8 billion
SoFi, $32.9 billion
These are real deposits earning net interest income.
Within crypto, there are strong analogies.
Ethena, a synthetic dollar protocol that didn’t exist two years ago, holds $7.9 billion
EtherFi, a liquid restaking protocol, has $9.9 billion
These aren’t deposits, but staked assets, yield-bearing positions, or liquidity parked in smart contracts — “Total Value Locked” in industry terms. But from the user’s perspective, the money is sitting somewhere, earning something.
The difference is how these platforms monetize deposits and what they can earn from users.
SoFi generates $264 in annual revenue per user. This makes sense given SoFi cross-sells aggressively across loans, investment accounts, and credit cards, and its users skew higher income.
Chime generates $227 per user, mostly from interchange.
Nubank, operating in Brazil, a lower-GDP-per-capita market, gets $151.
Revolut, despite its massive user base, earns just $60 per head.
EtherFi? $256 per user, which is comparable to SoFi. Unfortunately for the crypto upstart, EtherFi has 20,000 active users, and SoFi has 12.6 million. The DeFi protocol monetizes its tiny user base as effectively as the best neobanks monetize their massive ones.
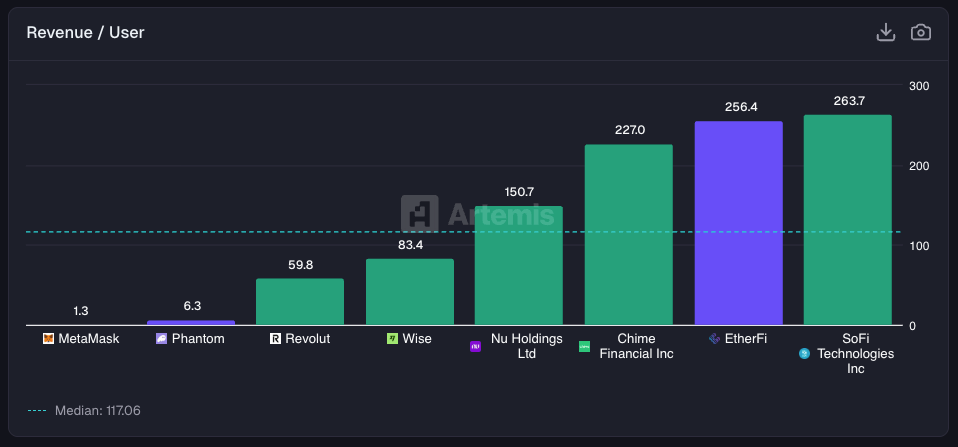
On the other hand, MetaMask did around $85MM of revenue last year, which amounts to about $3 in ARPU, less than Revolut in its early days. Ethena has $7.9 billion in TVL but a fraction of Nubank’s reach.
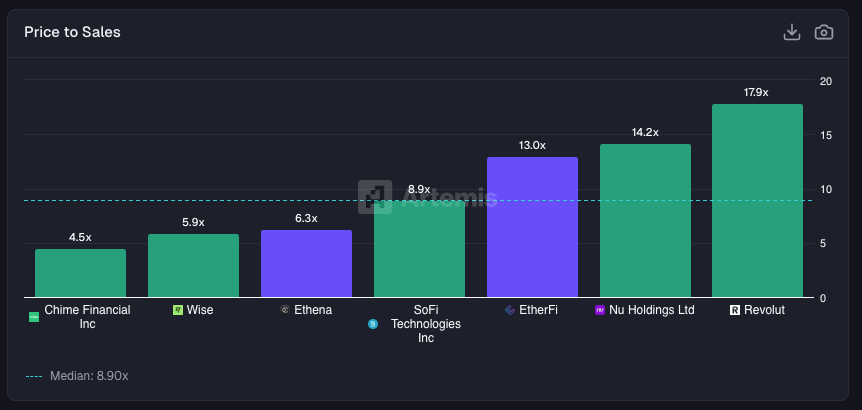
Valuations reflect this duality between growth and monetization. Revolut trades at 18x revenue, a premium for its positioning and optionality. EtherFi trades at 13x, Ethena at 6.3x, also roughly in line with SoFi and Wise. The markets surprisingly value DeFi / onchain banks similar to fintech banks.
The convergence thesis is that wallets become neobanks. We see this with MetaMask adding a debit card and Phantom integrating fiat on-ramps. We’re getting there. But when an onchain neobank like EtherFi earns more per user than Revolut, the gap is narrower than the narratives suggest.
Trading: Onchain DEXs rival traditional brokerage
Let’s shift to the capital markets.
We were surprised by how much volume onchain exchanges have relative to traditional brokerages.
Robinhood processed $4.6 trillion in trading volume over the last twelve months, driven mostly by stocks, options, and crypto. This is on $300B of assets, give or take.
Hyperliquid did roughly $2.6 trillion in spot and perpetual trading volume, driven mostly by crypto though equities and commodities are starting to take share.
Coinbase did $1.4 trillion, almost entirely crypto.
Charles Schwab, the old guard, doesn’t break out trading volume the same way, but its $11.6 trillion in assets under custody gives you a sense of the scale difference between new money and old money — about 40x the size of Robinhood.
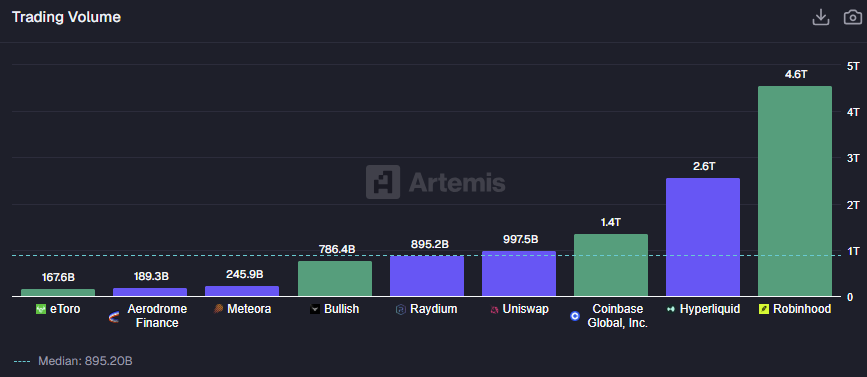
Other decentralized exchanges like Uniswap, the protocol that proved automated market makers could work, did just under $1 trillion in volume. Raydium, the leading Solana DEX, did $895 billion. Meteora and Aerodrome added another ~$435 billion between them. In aggregate, the major DEXs are processing volumes comparable to Coinbase. This was unthinkable three years ago.
We do not know, of course, how much of this volume includes wash trading vs. real activity, but it is the direction of the trend that matters. Further, while the volume convergence is real, the take rate is different between DEXs and traditional brokerages.
Robinhood takes 1.06% of every trade, mostly through payment for order flow and crypto spreads
Coinbase takes 1.03%, with high spot crypto fees still common within CEXs
Even eToro, the social trading platform that just went public, takes 41 basis points
The DEXs operate in a different universe.
Hyperliquid takes 3 basis points
Uniswap takes 9 basis points
Aerodrome takes 9 basis points
Raydium takes 5 basis points
Meteora, at 31 basis points, is the outlier
The decentralized exchanges are able to generate large amounts of volumes but because competition for LPs and traders is fierce, the take rates for these exchanges suffer. This is similar to how the actual exchanges, like NASDAQ and ICE, have a separate function from brokers that bring clients to their venues.
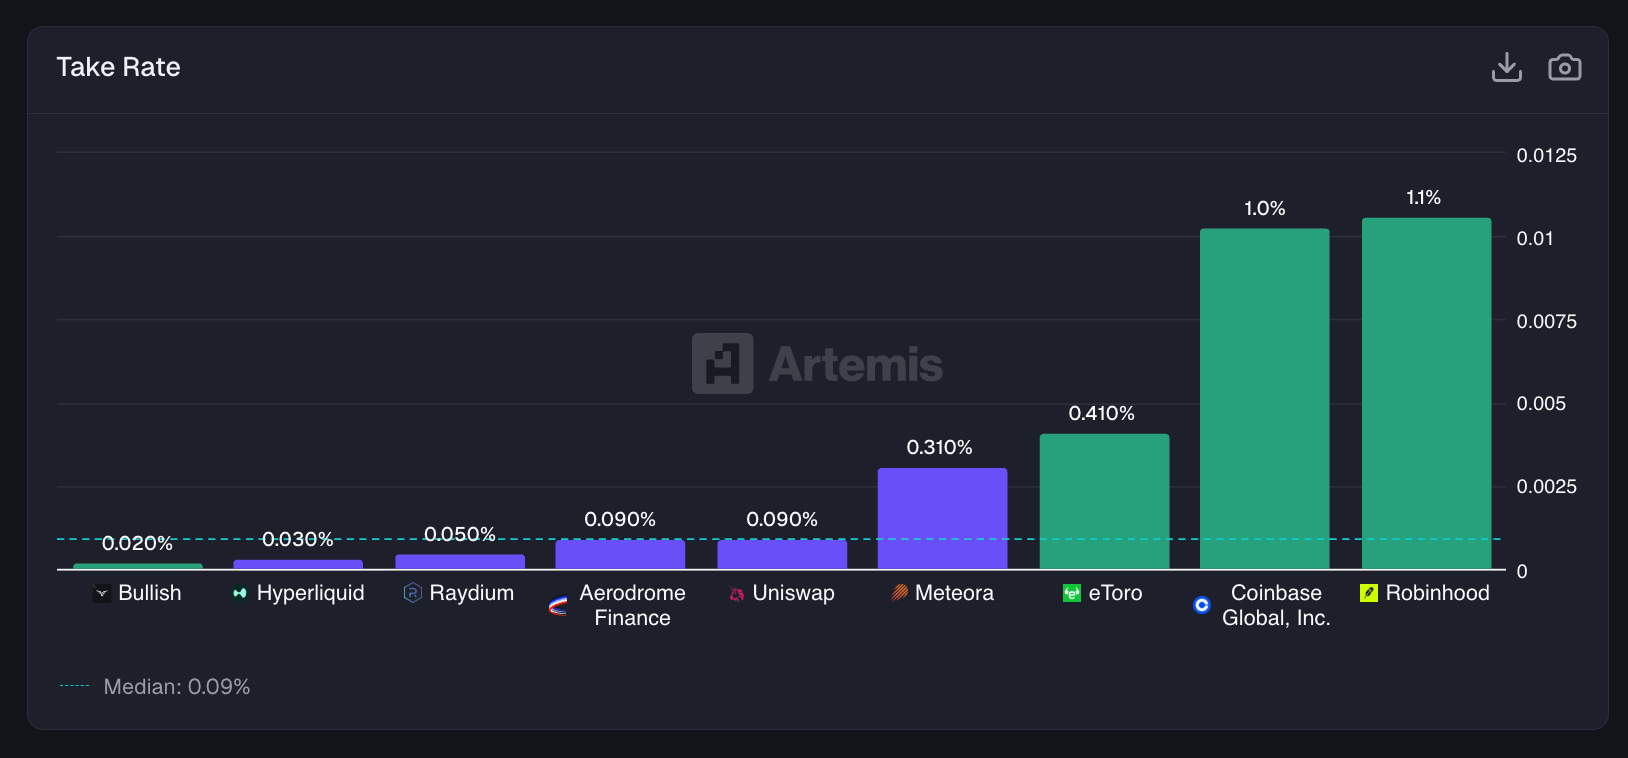
This is the DEX paradox. DEXs have built ta rading infrastructure that rivals centralized exchanges on volume, runs 24/7 with relatively no downtime, requires no KYC, and lets anyone list any asset. At 9 basis points on a trillion dollars, Uniswap generates roughly $900MM in fees and ~$29MM of revenue. At a 1% take rate on $1.4 trillion of volume, Coinbase generates $14 billion of revenue.
In terms of market valuations, the results are consistent with these issues.
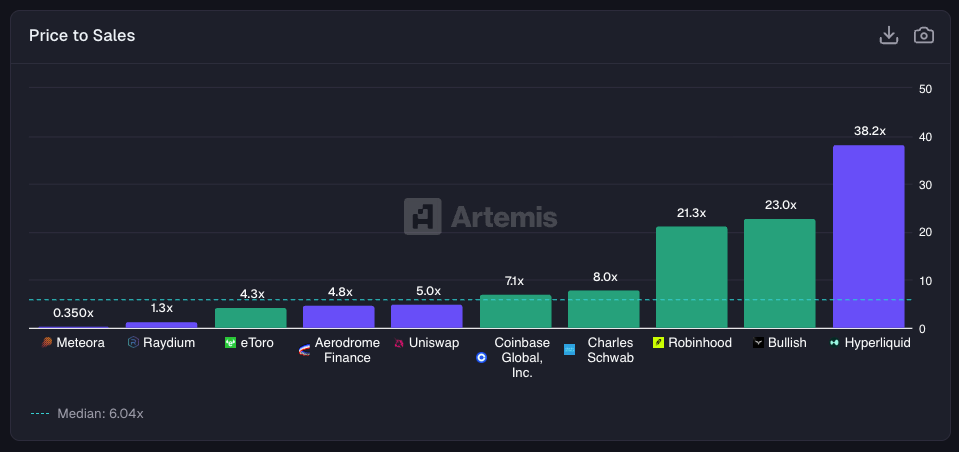
Coinbase trades at 7.1x sales
Robinhood trades at 21.3x, high for a brokerage, but justified by growth
Schwab trades at 8.0x, a mature multiple for a mature business
Uniswap trades at 5.0x fees
Aerodrome at 4.8x fees
Raydium at 1.3x fees
The markets are not valuing these protocols like high-growth tech companies, in part because of the lower take rates they generate relative to traditional brokerage firms.
The stock performance chart shows where sentiment has gone.
Robinhood is up ~5.7x from late 2024, riding the retail investing and crypto rally. Coinbase is up 20% during the same period. Uniswap, the protocol that launched a thousand DEX forks, is down 40%. The tokens haven’t captured as much value despite the amount of volume that flows through their DEXs, in part because they are a less clearly useful investment instrument. The one exception is Hyperliquid, which is up nearly the same amount as Robinhood during the same time period due to its massive rise.
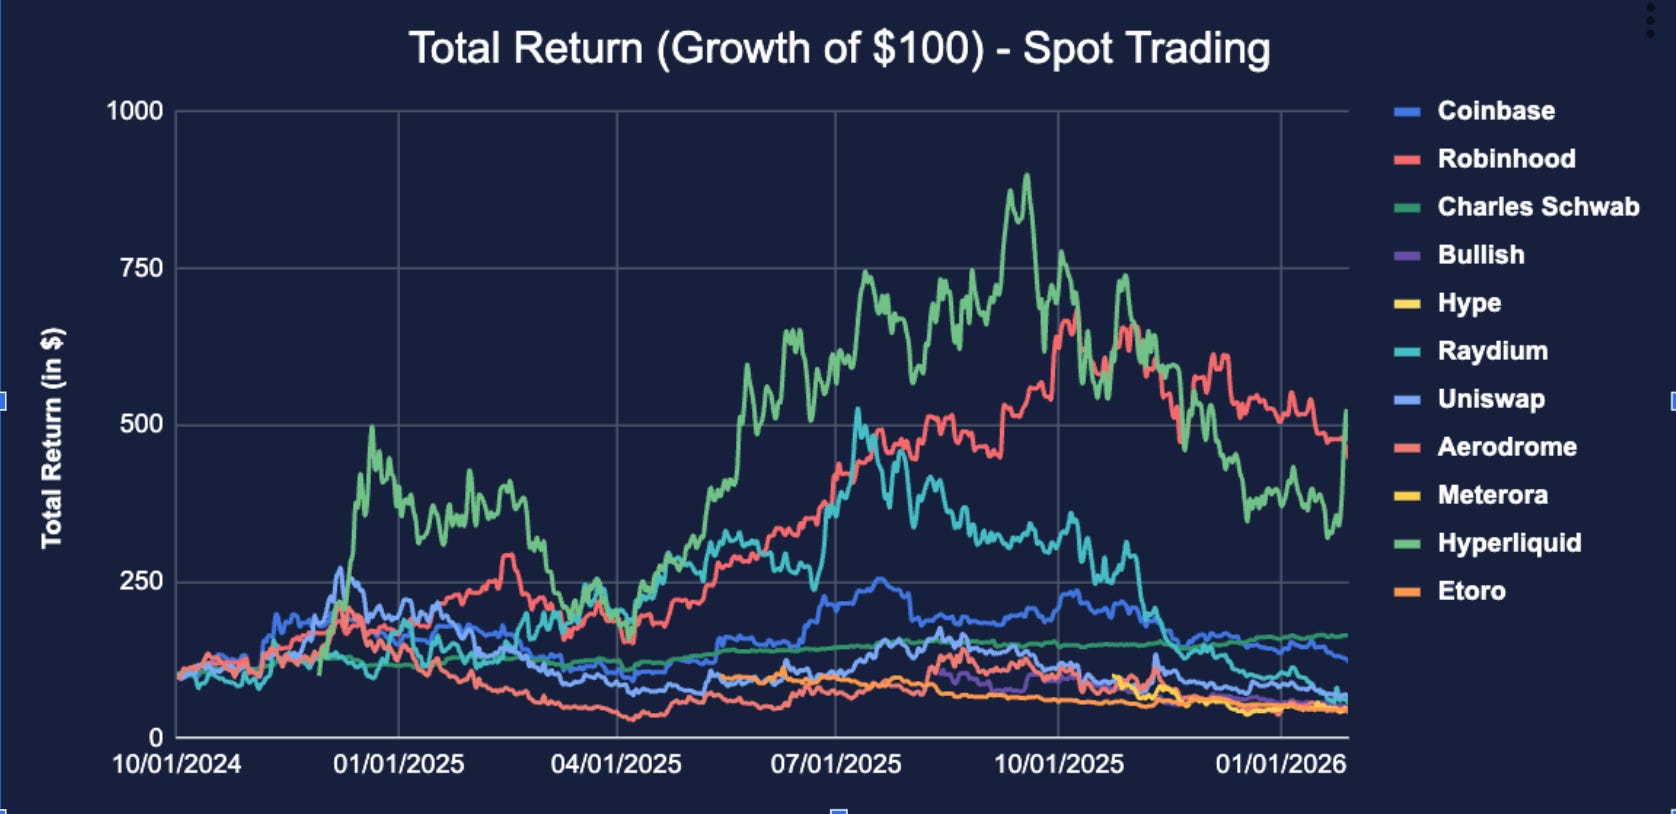
While historically DEXs haven’t been able to capture value and were viewed as public goods, projects like Uniswap are turning on their “fee switch” where fees are used to burn the UNI token and today does $32MM of annualized revenue.
We are hopeful that as more volume moves onchain, value accrues to DEX tokens, with Hyperliquid as a great example of what works. But for now, until there are Hyperliquid like value capture for token holders, DEX tokens will underperform their CEX equity counterparts.
Lending: Underwriting the next generation
Lending is where the comparison gets even more interesting. On the one side, you have fintech’s core lending product, unsecured consumer credit.
Affirm lets you split your Peloton into four payments
Klarna does the same for fast fashion
Lending Club pioneered peer-to-peer loans before pivoting to become an actual bank.
Funding Circle underwrites small businesses.
These companies make money by charging borrowers more than they pay depositors, and hoping the defaults don’t eat the spread.
On the other side, you have collateralized DeFi lending. Aave, Morpho, Euler. The borrower posts ETH, borrows USDC, and pays an algorithmically determined rate. If the collateral drops too far, the protocol sells it automatically. No collections calls or charge-offs.
These are fundamentally different businesses that happen to share a name.
Start with the loan books. Aave has $22.6 billion in loans outstanding. That’s more than Klarna ($10.1B), Affirm ($7.2B), Funding Circle ($2.8B), and Lending Club ($2.6B) combined. The largest DeFi lending protocol has a bigger loan book than the largest BNPL player. Let that sink in.
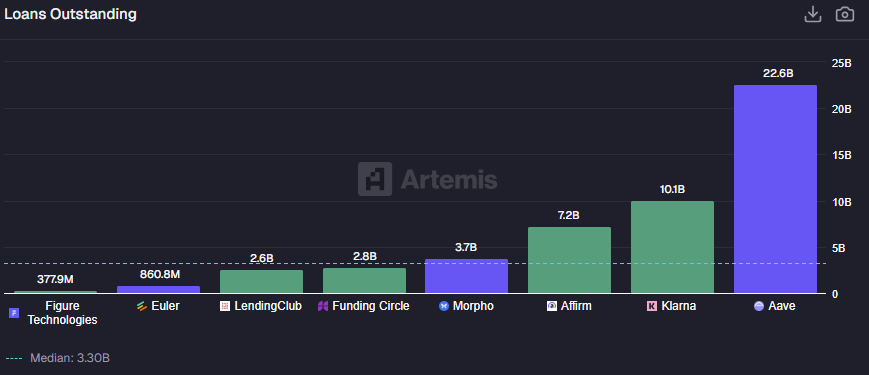
Morpho adds another $3.7 billion. Euler, which relaunched after its 2023 exploit, has $861 million. The DeFi lending stack, in aggregate, rivals the entire publicly traded digital lending sector, all within roughly four years. But the economics are inverted.
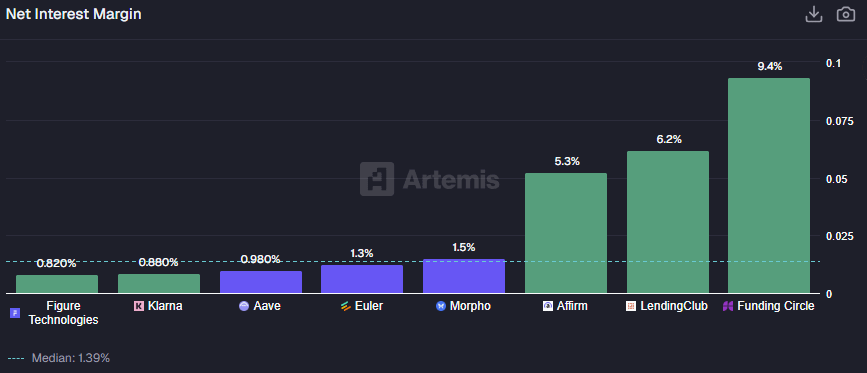
Funding Circle operates at a 9.35% “net interest margin” (due to its private credit-like business model). Lending Club runs at 6.18%. Affirm, despite being a BNPL company rather than a traditional lender, pulls 5.25%. These are fat spreads, compensation for the credit risk these companies absorb by actually performing underwriting.
On the crypto side, Aave’s net interest margin is a mere 0.98%. Morpho runs at 1.51%. Euler at 1.30%. The DeFi protocols generally earn less than what fintech lenders earn, despite having larger loan books.
DeFi lending is overcollateralized by design. To borrow $100 on Aave, you typically post $150 or more in collateral. The protocol isn’t taking credit risk. It’s taking liquidation risk, which is a different beast entirely. The borrower is paying for leverage and liquidity, not for the privilege of accessing credit they couldn’t otherwise get.
Fintech lenders are doing the opposite. They’re extending unsecured credit to consumers who want to buy now and pay later. The spread compensates for the people who never pay at all. This shows up in the loss numbers from actual defaults, managing which is the core job of underwriting.
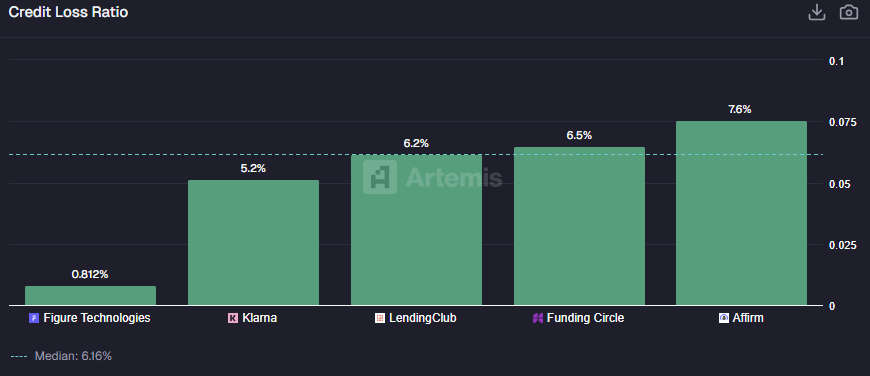
So which model is better? Depends on what you’re optimizing for.
Fintech lending serves borrowers who need money they don’t have,and takes genuine underwriting risk. It’s also brutal. The early digital lenders (OnDeck, Lending Club, Prosper) have been through multiple near-death experiences. Affirm’s stock is down ~60% from its highs despite the business actually working, often because the underwriting revenue is priced at a SaaS multuple, rather than accommodating for the inevitably losses down the line.
DeFi lending is a leverage business. It serves borrowers who already have assets but want liquidity without selling, like a margin account. There’s no credit decision, other than the quality of collateral. It’s capital efficient, scalable, and earns thin margins on enormous volume. It’s also only useful to people who are already onchain with a large amount of assets to earn yield on those assets or want additional leverage.
Prediction Markets: Who knows?
Lastly, we look at prediction markets.
These projects are the newest battleground between fintech and DeFi, and also the strangest. For decades, they were an academic curiosity, loved by economists but hated by regulators. The Iowa Electronic Markets ran small-scale election forecasts. Intrade briefly flourished before getting shut down. Most were called gambling or sports betting.
The idea that you could trade on real-world outcomes, and that those markets would produce better forecasts than polls or pundits, was mostly theoretical.
That all changed in 2024, and accelerated during the second Trump administration. Polymarket processed over a billion dollars in election betting. Kalshi won its lawsuit against the CFTC and launched political contracts to US users. Robinhood, never one to miss a trend, added event contracts. DraftKings, already running a de facto prediction market through daily fantasy sports, watched from the sidelines with a $15.7 billion market cap and $5.5 billion in revenue.
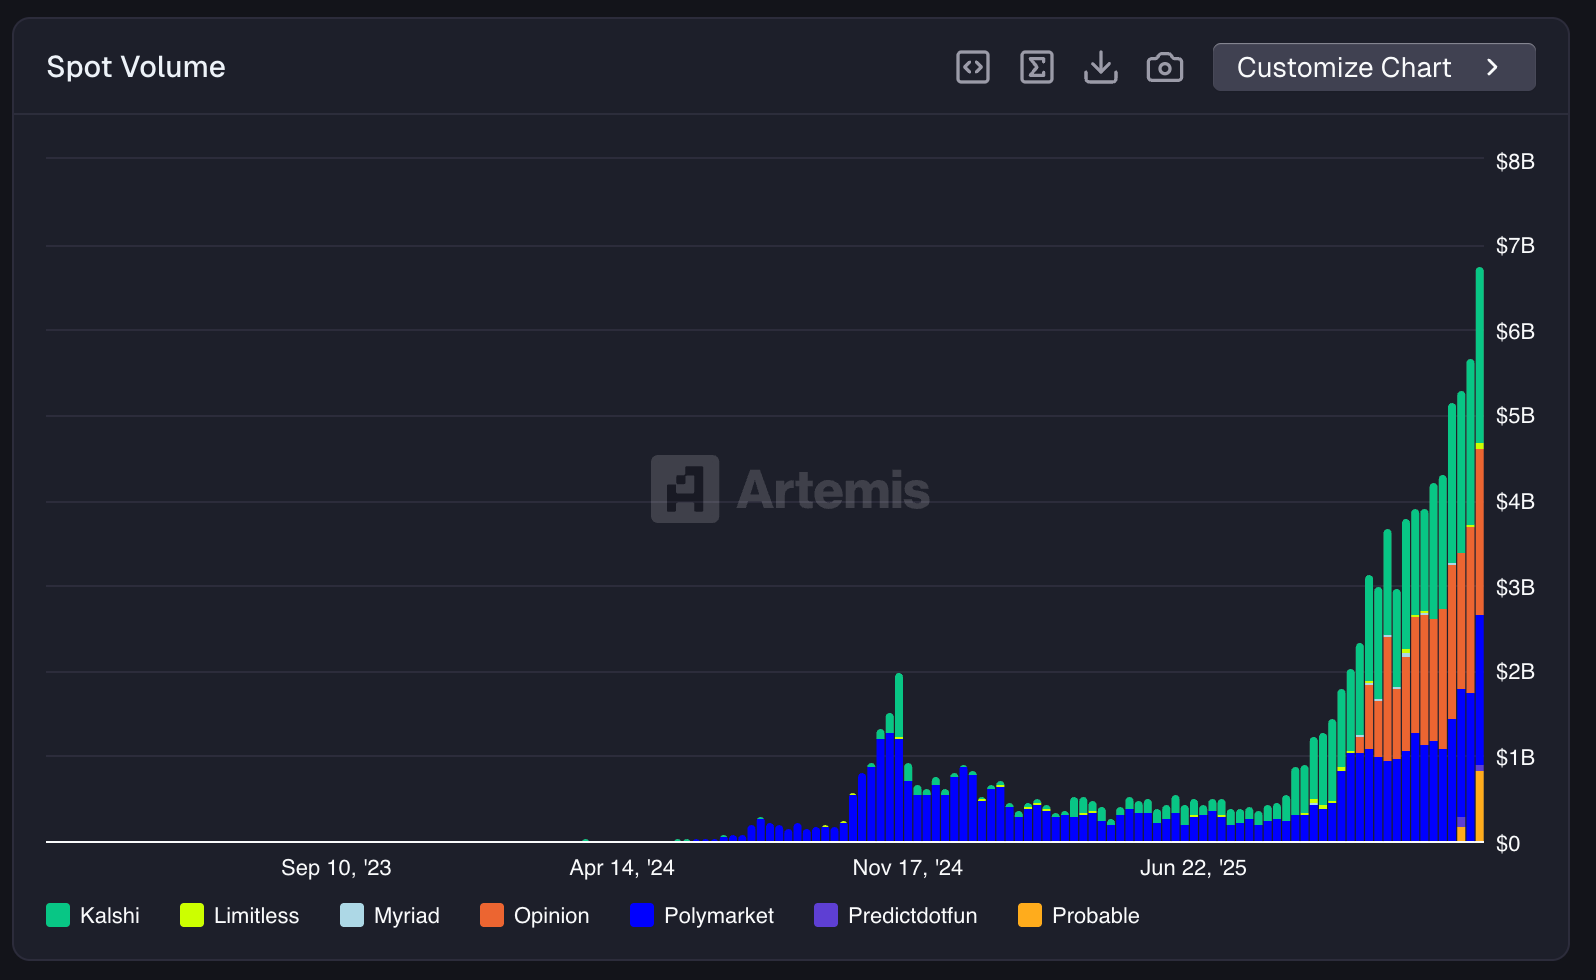
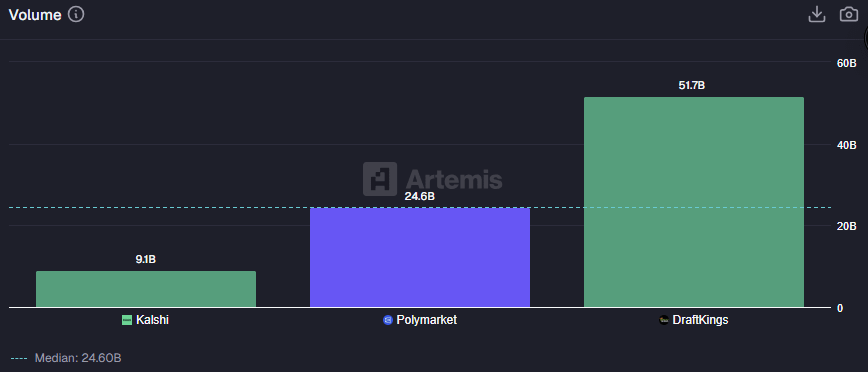
The category went from niche to mainstream in about eighteen months, with prediction markets doing ~$7B of weekly volume, hitting yet another all-time high.
DraftKings did $51.7 billion in trading volume over the last twelve months. Polymarket did $24.6 billion, roughly half, despite being a crypto-native protocol that US users technically aren’t supposed to access. Kalshi, the regulated American alternative, managed $9.1 billion. On pure volume, Polymarket is competitive. It built a liquid, global prediction market on Polygon while Kalshi was fighting in court.
Looking at revenue, the comparison falls apart.
DraftKings generated $5.46 billion in revenue last year, while Kalshi only pulled in $264 million. Polymarket made $38 million annualized revenue run rate after turning taker fees for 15 minute crypto markets.
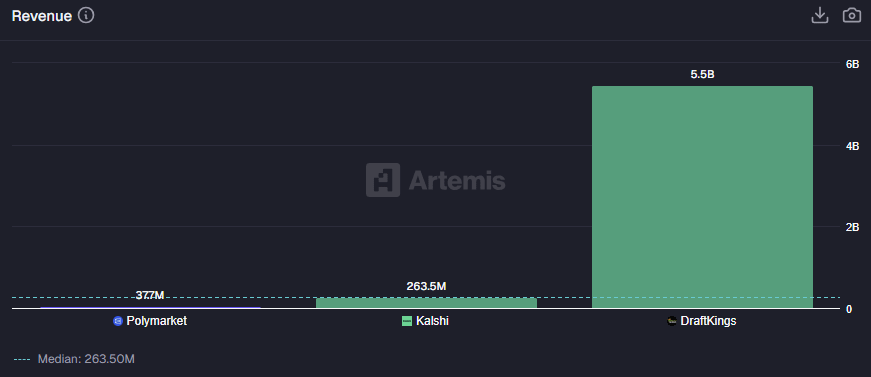
The gap is take rates (or the “hold” in sports betting parlance).
DraftKings keeps 10.57% of every dollar wagered. This is the sports betting model: the house takes a cut, offers odds, and manages risk.
Kalshi takes 2.91%, a thinner margin appropriate for a financial exchange.
Crypto native Polymarket takes 0.15%. On $24.6 billion in volume, it captures very little, for now.
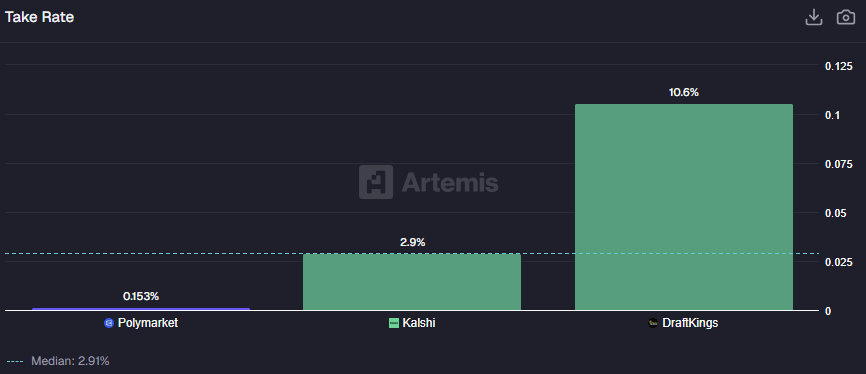
This is the DEX dynamic all over again. Polymarket isn’t focused on value capture, instead providing the infrastructure for prediction markets to exist that matches buyers and sellers and settles contracts onchain. It does not employ oddsmakers, nor does it manage a balance sheet or take the other side of your bet. While the efficiency is remarkable, monetization isn’t the focus.
Investors clearly believe that Polymarket will be able to monetize —
Polymarket is valued at $9B, a 240x sales multiple
Kalshi, at $11 billion on $264 million in revenue, trades at 42x
DraftKings trades at 2.9x
VCs literally cannot stop throwing money at these platforms, as “legacy” operators like DraftKings and Flutter (FanDuel) see their stocks plunge.
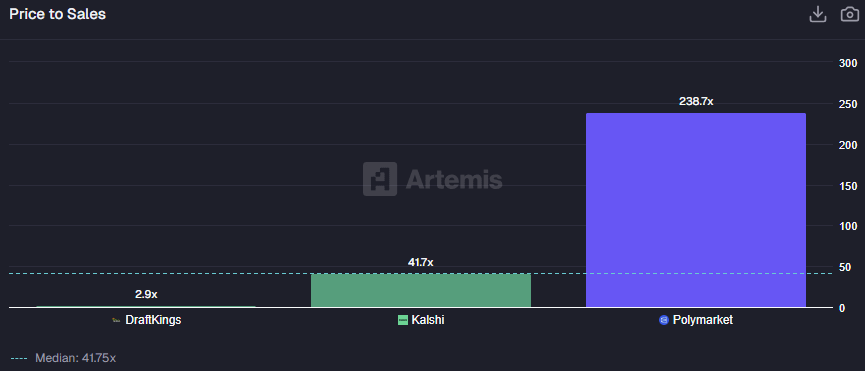
Polymarket’s valuation assumes it will either turn on monetization in a massive way or become something much larger than a prediction market. At >200x revenue, you’re not buying a business. You’re buying a call option on an entirely new financial primitive. Maybe Polymarket becomes the default venue for hedging any real-world event. Maybe it adds more sports, earnings, weather, or anything with a binary outcome. Maybe it captures a larger % instead of 0.15% and suddenly generates billions.
This is the convergence question in its purest form. Does the future belong to regulated exchanges with take rates and compliance departments? Or to permissionless protocols that let anyone bet on anything, anywhere, with no margin for the house?
The Convergence
A few years back, we would not have been able to compare DeFi and Fintech head-to-head. Yet here we are.
Crypto has built a financial infrastructure that rivals fintech on volume, users, and assets. Stablecoin rails are more global than traditional payment players. Aave’s loan book is bigger than Klarna’s. Polymarket volumes rivals that of Draftkings. The technology works, and products have found large audiences.
But there’s a catch. Crypto doesn’t capture as much value as traditional fintech counterparts when it comes to take rate. The pattern is consistent across every category we examined. Crypto builds the most efficient open infrastructure, and distributes economic capture as a result.
This is either a bug or a feature, depending on your perspective. If you believe financial services are destined to become commoditized utilities, crypto is simply accelerating the inevitable. If you believe businesses need revenue to survive, most tokens have a problem in capturing value.
The convergence is happening regardless. Banks are piloting tokenized deposits, NYSE is looking into tokenized equity trading, Stablecoin Supply hit an all-time high at $300B+. The fintech incumbents see what’s coming — they’re not going to ignore it. They’re going to absorb it.
The question for the next decade is simple: Does crypto learn to build tollbooths, or does fintech learn to use crypto’s roads? Our bet is both.
About Artemis
Artemis is building the AI investment research platform for tokens / equities / stablecoins / DATs. We recently published a stablecoin payments report with McKinsey and we’re a team of investors and engineers from Ribbit Capital, Venmo, and Insight Partners that love crypto / fintech and fundamental investing. Check out Artemis here.
🚀 Postscript
Sponsor the Fintech Blueprint and reach over 200,000 professionals.
👉 Reach out here.Check out our AI newsletter, the Future Blueprint, 👉 here.
Read our Disclaimer here — this newsletter does not provide investment advice

Let's goooo
Great read.
I suggest an additional statement to your
`Does crypto learn to build tollbooths, or does fintech learn to use crypto’s roads? Our bet is both.``
`Does crypto learn to build tollbooths, or does fintech cannibalize its business model with one that has substantially lower take rates? Our bet is both.`